Saturday, September 05

Tom Jones Otuka Brother YaMadamboss YaShaya Sekuru Gudo Hanzi Makaseka Sekuru Murata Pavakafa

Tom Jones Otuka Brother YaMadamboss  YaShaya Sekuru Gudo Hanzi Makaseka Sekuru Murata Pavakafa
 

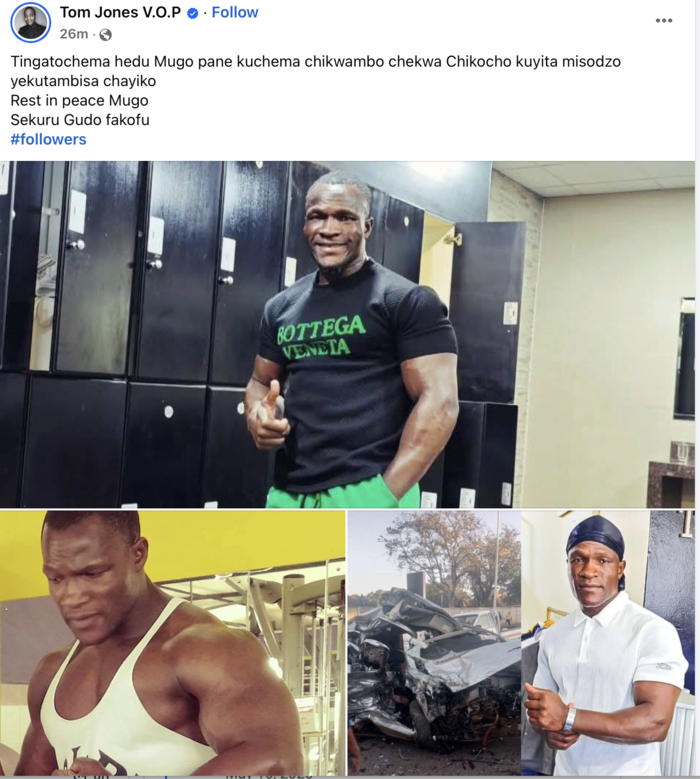
Tingatochema hedu Mugo pane kuchema chikwambo chekwa Chikocho kuyita misodzo yekutambisa chayiko 
Rest in peace Mugo
Sekuru Gudo fakofu 
#followers

Ndikunzwawo kuda kumbopemberera nhasi sekupembererawo kwamakamboyitawo baba vangu vaMurata vashaya, rufu harusekanwe mangwana chiri kwenyu saka dzungu ramayita ndereyi nhasi zvamati wundundu seGudo rabatwa chibharo pembererayika tione handiti rufu rwunosekesa here nyoka dzechinzara nzara tinotiwo kwamuri mamama vigayi chikwambo chenyu makanyarara fokorooo🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣🤣
#followers


  • Share:

Info News

Class Action Settlement: How Claims, Payments, and Deadlines Work

class action settlement, settlement claim form, class action payment, class action settlement check, settlement administrator, class action deadline

rnrn

Class Action Settlement: How Claims, Payments, and Deadlines Work

rnrn

A class action settlement can be confusing. You may receive a notice saying you are eligible for money, credit, identity monitoring, repairs, or another benefit.

rnrn

But what does it actually mean?

rnrn

Do you have to file a claim?

rnrn

When will payment arrive?

rnrn

What happens if you do nothing?

rnrn

Understanding the settlement process helps you avoid missing deadlines or giving up rights without realizing it.

rnrn

What Is a Class Action Settlement?

rnrn

A class action settlement is an agreement to resolve a lawsuit brought on behalf of a group.

rnrn

The company may agree to provide compensation or other relief, while often denying wrongdoing.

rnrn

The settlement usually needs court approval. The court reviews whether the settlement is fair, reasonable, and adequate for the class.

rnrn

What Is a Settlement Notice?

rnrn

A settlement notice explains your rights.

rnrn

It may arrive by:

rnrn

Email
rnPostcard
rnLetter
rnWebsite notice
rnOnline ad
rnPublication notice

rnrn

The notice usually explains:

rnrn

Who is included
rnWhat the lawsuit claimed
rnWhat the settlement provides
rnHow to file a claim
rnHow to opt out
rnHow to object
rnDeadlines
rnHearing date
rnContact information

rnrn

Read it carefully.

rnrn

What Is a Claim Form?

rnrn

A claim form is the document you submit to request settlement benefits.

rnrn

It may ask for:

rnrn

Name
rnAddress
rnEmail
rnPhone number
rnProof of purchase
rnAccount number
rnTransaction dates
rnLoss amount
rnPayment preference
rnSignature or certification

rnrn

Only submit accurate information.

rnrn

Do You Always Need Proof?

rnrn

Not always.

rnrn

Some settlements require documentation. Others allow claims without proof, but payments may be smaller.

rnrn

Examples of proof include:

rnrn

Receipts
rnInvoices
rnBank statements
rnEmails
rnProduct serial numbers
rnRepair records
rnScreenshots
rnAccount records

rnrn

If you have proof, submit it when allowed.

rnrn

How Are Payments Calculated?

rnrn

Payments may depend on:

rnrn

Settlement fund size
rnNumber of valid claims
rnDocumented losses
rnPlan of allocation
rnAdministrative costs
rnAttorney fees
rnCourt-approved deductions
rnClaim category

rnrn

Sometimes advertised payment amounts are only estimates. If many people file claims, individual payments may be lower.

rnrn

Why Payments Take Time

rnrn

Class action payments may take months or longer.

rnrn

Reasons include:

rnrn

Court approval process
rnObjection period
rnAppeals
rnClaim review
rnFraud screening
rnAddress verification
rnPayment processing
rnSecond distribution planning

rnrn

The FTC explains that when possible it uses money collected from defendants to provide refunds, and remaining funds may sometimes support a second round of payments.

rnrn

What Does It Mean to Opt Out?

rnrn

Opting out means you exclude yourself from the settlement.

rnrn

If you opt out:

rnrn

You usually receive no settlement benefit
rnYou may keep the right to sue separately
rnYou must follow the opt-out instructions
rnYou must meet the deadline

rnrn

People with large individual damages should consider legal advice before deciding.

rnrn

What Does It Mean to Object?

rnrn

Objecting means you stay in the class but tell the court you disagree with part of the settlement.

rnrn

You may object to:

rnrn

Settlement amount
rnAttorney fees
rnRelease terms
rnClaim process
rnNotice method
rnPayment formula

rnrn

Objecting is different from opting out.

rnrn

What Happens If You Do Nothing?

rnrn

Doing nothing may mean:

rnrn

You receive no payment
rnYou remain bound by the settlement
rnYou give up rights to sue separately
rnYou lose the chance to object or opt out

rnrn

This depends on the notice. Always read the specific instructions.

rnrn

How to Avoid Settlement Scams

rnrn

Scammers often copy the language of real settlements.

rnrn

Be careful if someone:

rnrn

Asks you to pay to receive money
rnPromises guaranteed payment
rnDemands gift cards or wire transfers
rnThreatens legal action
rnRequests unnecessary sensitive information
rnUses a fake website
rnClaims special access

rnrn

The FTC warns that it never asks people to pay to file a claim or get a refund.

rnrn

Final Thoughts

rnrn

A class action settlement can provide money or other benefits, but deadlines matter.

rnrn

Read the notice. Confirm the website is official. File a claim if required. Keep records. Be careful with scams.

rnrn

And before opting out or signing away important rights, consider speaking with a qualified attorney.

rn

SEO Meta Title Credit Repair vs Credit Counseling: Compare Your Options

When credit problems become stressful, two options often appear in search results: credit repair and credit counseling. They sound similar, but they are not the same service. Credit repair focuses on disputing inaccurate, incomplete, or unverifiable information on credit reports. Credit counseling focuses on budgeting, debt repayment, and financial education. Knowing the difference can help you avoid scams and choose the right help.

Credit repair companies often advertise help with removing negative items from credit reports. Legitimate credit repair is based on your legal right to dispute inaccurate information. If a late payment, collection, account balance, personal detail, or account status is wrong, you can dispute it with the credit bureaus and the company that furnished the information.

However, accurate negative information usually cannot be removed simply because it hurts your score. Late payments, collections, bankruptcies, and charge-offs may remain on credit reports for legally allowed periods if they are accurate. Be cautious with any company that promises a specific score increase, guaranteed removals, or a new credit identity.

Credit counseling is different. A nonprofit credit counseling agency can review income, expenses, debts, and goals. Counselors may help build a budget, explain credit reports, suggest repayment strategies, and discuss whether a debt management plan makes sense. A debt management plan may consolidate payments through the counseling agency and sometimes reduce interest rates or fees with participating creditors.

Credit counseling can be useful when the main problem is debt affordability. If you are making minimum payments, falling behind, or using one card to pay another, a counselor can help create a structured plan. Credit repair alone will not solve unaffordable debt.

Credit repair can be useful when the main problem is inaccurate reporting. For example, an account that does not belong to you, a debt listed twice, an incorrect late payment, a paid account still shown as unpaid, or outdated information may be disputable. You can file disputes yourself for free, but some people hire help because they do not want to manage the paperwork.

Before paying for credit repair, understand your rights. In the United States, credit repair companies must follow federal rules, including restrictions on misleading claims and upfront fees. You should receive a written contract, cancellation rights, and clear information about what the company will do. If a company pressures you, asks you to lie, tells you to dispute everything, or suggests using a different Social Security number, walk away.

A strong credit rebuilding plan often includes both cleanup and behavior changes. Start by pulling credit reports from the major bureaus. Review personal information, open accounts, closed accounts, collections, public records, inquiries, balances, and payment history. Highlight anything inaccurate and gather supporting documents.

Next, pay every current bill on time. Payment history is a major scoring factor. Set up reminders or autopay for minimum payments. Then focus on credit utilization, which is the percentage of available revolving credit being used. Lower balances can help improve scores over time.

Avoid opening too many new accounts at once. New inquiries and new accounts can lower scores temporarily. Instead, build a steady pattern: pay on time, reduce balances, keep older accounts in good standing, and monitor reports for errors.

If you have no active credit, a secured credit card or credit-builder loan may help, but fees and terms matter. Choose products from reputable banks or credit unions and avoid high-fee cards that drain your budget.

The right choice depends on the root problem. Choose credit repair if the issue is inaccurate reporting. Choose credit counseling if the issue is debt management, budgeting, or missed payments. Use both if you have errors and unaffordable debt. Most importantly, avoid anyone promising instant results. Real credit improvement takes accurate reporting, consistent payments, lower debt, and time.