Thursday, October 08

Olinda Chapel Takes A Swipe @ Zuva Habane

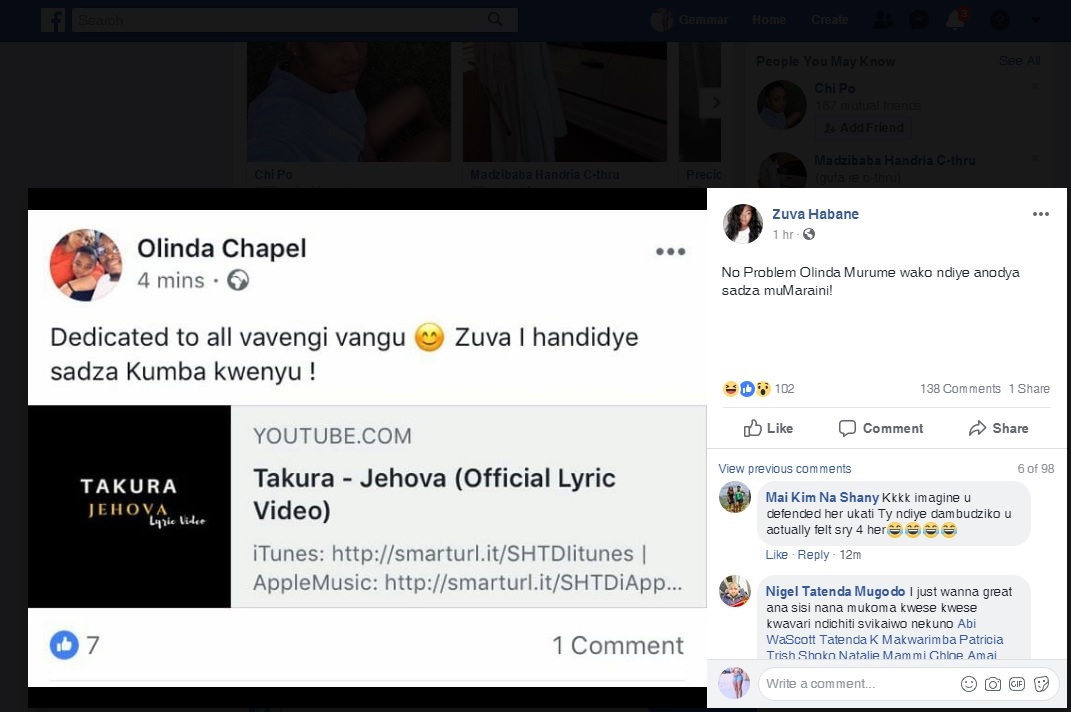
The Zimbabwean facebook community was shocked when out of thousands who commented on Tytan Cheating on his wife Olinda Chapel. She posted a comment attacking Zuva Habane. If you watch any of Zuva's lives or posts she was defending Olinda for the most part. 

Olinda posted a comment telling Zuva Habane "Handidye sadza Kumba Kwako" Zuva in her classic way responded simply by saying "No Problem Olinda Murume wako ndiye anodya sadza mumaraini!"

This is a developing story  we will keep you updated. 

  • Share:

Info News

High-Yield Savings vs CDs: Emergency Cash Comparison

Emergency cash should be safe, accessible, and separated from everyday spending. That is why many people compare high-yield savings accounts and certificates of deposit. Both can pay interest, both can be offered by banks or credit unions, and both can be useful. But they are not designed for the same purpose.

A high-yield savings account is a deposit account that typically pays a higher interest rate than a traditional savings account. It is designed for liquidity. You can usually transfer money when needed, making it a good option for emergency funds, short-term savings, tax reserves, travel funds, and upcoming bills.

A certificate of deposit, or CD, is a time deposit. You agree to leave money with the bank or credit union for a set term, such as a few months or several years. In exchange, the institution may offer a fixed rate. If you withdraw early, you may pay an early withdrawal penalty. That makes CDs less flexible than savings accounts but potentially useful for money you do not need immediately.

The first question is purpose. If the money is truly for emergencies, access matters more than chasing the highest rate. A job loss, car repair, medical bill, or home repair may require quick cash. A high-yield savings account is usually better for the core emergency fund because it keeps money available.

CDs can work for extra cash beyond the basic emergency fund. For example, if you want to earn interest on money set aside for a future down payment, tuition bill, or planned purchase, a CD can help lock in a rate. Some savers use a CD ladder, dividing money among several CDs with different maturity dates. This creates periodic access while still earning fixed rates.

Interest rate risk matters. A high-yield savings rate can change at any time. When market rates fall, the account yield may fall too. A CD rate is usually fixed for the term, which can be helpful if rates decline after you open it. But if rates rise, your money may be locked into a lower rate unless you accept a penalty or use special CD types.

Liquidity is the biggest difference. Savings accounts usually allow easier transfers, although banks may have transaction policies and processing times. CDs restrict access until maturity. Before opening a CD, ask how the early withdrawal penalty is calculated and whether partial withdrawals are allowed.

Fees should also be reviewed. Some savings accounts have monthly maintenance fees, minimum balance requirements, excessive transaction fees, or transfer limitations. Many online banks offer no monthly fee, but you should still read the account agreement. CDs may have fewer monthly fees but can have penalties for early withdrawal.

Safety depends on where the money is held. Bank deposits may be insured by the FDIC, and credit union deposits may be insured by the NCUA, within applicable limits and ownership categories. Always confirm that the institution is insured and understand coverage limits if you keep large balances.

Convenience is another factor. A high-yield online savings account may pay more than a traditional local bank, but transfers to your checking account may take time. Some people keep one month of expenses at their local bank and the rest in a higher-yield account. This balances access and return.

Taxes should not be ignored. Interest from savings accounts and CDs is generally taxable. The institution may issue a tax form, but you are responsible for reporting income according to tax rules. A tax professional can help with your specific situation.

A practical approach is to keep the first layer of emergency cash in checking or a linked savings account, the main emergency fund in high-yield savings, and longer-term cash goals in CDs or treasury-style alternatives if appropriate. The best mix depends on how stable your income is, how many dependents you support, and how quickly you might need the money.

High-yield savings and CDs are not rivals; they are tools. Savings accounts solve access. CDs solve rate certainty for money that can sit. When you match the account to the purpose, your cash can stay safer, more organized, and more productive.

Medicare Part D Plans: How Prescription Drug Coverage Works

Medicare Part D plans, prescription drug plans, Medicare drug coverage, Part D cost, Medicare prescription coverage, best Medicare Part D plan

rnrn

Medicare Part D Plans: Prescription Drug Coverage Explained

rnrn

Prescription drug costs can be one of the biggest concerns for people on Medicare.

rnrn

Medicare Part D helps pay for prescription medications. It is offered by private companies approved by Medicare.

rnrn

Medicare says Part D helps pay for brand-name and generic drugs, and it is optional coverage available to everyone with Medicare.

rnrn

Who Needs Medicare Part D?

rnrn

You may need Part D if you have Original Medicare and want prescription drug coverage.

rnrn

You may also receive drug coverage through a Medicare Advantage plan that includes Part D.

rnrn

Even if you do not take prescriptions now, Medicare says you should consider drug coverage to avoid a possible late enrollment penalty if you join later without creditable coverage.

rnrn

What Do Part D Plans Cover?

rnrn

Part D plans cover prescription medications, but each plan has its own formulary.

rnrn

A formulary is the list of covered drugs.

rnrn

Plans may organize drugs into tiers such as:

rnrn

Preferred generic
rnGeneric
rnPreferred brand
rnNon-preferred brand
rnSpecialty drugs

rnrn

The tier affects your cost.

rnrn

What to Check Before Choosing a Part D Plan

rnrn

Your Exact Medications

rnrn

List every medication, including:

rnrn

Drug name
rnDosage
rnQuantity
rnFrequency
rnPreferred pharmacy
rnGeneric or brand preference

rnrn

Small differences can change your annual cost.

rnrn

Pharmacy Network

rnrn

Some plans have preferred pharmacies where your cost may be lower.

rnrn

Check:

rnrn

Retail pharmacy pricing
rnPreferred pharmacy pricing
rnMail-order options
rnOut-of-network pharmacy rules

rnrn

Restrictions

rnrn

A plan may require:

rnrn

Prior authorization
rnStep therapy
rnQuantity limits

rnrn

These rules can affect access and cost.

rnrn

2026 Part D Out-of-Pocket Cap

rnrn

For 2026, Medicare says yearly out-of-pocket costs for Part D-covered prescription drugs are capped at $2,100. Once that cap is reached, you do not pay copayments or coinsurance for covered Part D drugs for the rest of the calendar year.

rnrn

This is important for people with expensive medications.

rnrn

Part D Late Enrollment Penalty

rnrn

If you go without Part D or other creditable prescription drug coverage for too long after becoming eligible, you may owe a late enrollment penalty.

rnrn

Medicare says the 2026 late enrollment penalty is calculated using 1% of the national base beneficiary premium, which is $38.99 in 2026, multiplied by the number of full uncovered months.

rnrn

Extra Help for Drug Costs

rnrn

Extra Help is a Medicare program for people with limited income and resources. It helps pay Part D premiums, deductibles, coinsurance, and other costs. Medicare says people receiving Extra Help also do not pay a Part D late enrollment penalty while they have Extra Help.

rnrn

Common Part D Mistakes

rnrn

Avoid:

rnrn

Choosing by premium only
rnNot checking your exact medications
rnIgnoring preferred pharmacy pricing
rnMissing enrollment deadlines
rnAssuming all plans cover all drugs
rnNot reviewing the plan each year
rnIgnoring prior authorization rules
rnFailing to apply for Extra Help if eligible

rnrn

How Often Should You Review Your Part D Plan?

rnrn

Review your Part D plan every year.

rnrn

Plans can change:

rnrn

Premiums
rnDeductibles
rnFormularies
rnDrug tiers
rnPharmacy networks
rnRestrictions
rnCopays

rnrn

Even if your plan worked last year, it may not be the best choice next year.

rnrn

Final Thoughts

rnrn

Medicare Part D can help reduce prescription drug costs, but the right plan depends on your medications and pharmacy.

rnrn

Before enrolling, compare formularies, drug tiers, pharmacy pricing, deductibles, and total annual cost.

rnrn

The best Part D plan is not always the cheapest monthly premium. It is the one that lowers your real prescription costs.

rn