2020 is a year many want to forget and never wish to remember. 2020 has been such a wierd year and with social media numbers dont lie. Zimbolivenews researched social media numbers and trends for the most talked about and most popular Zimbabwean Celebrities and the numbers showed that Ginimbi was the most popular Zimbabwean Celebrity for 2020, Ginimbi had a huge following on Instagram and his lives during the lock down made him more popular and his death made him the most popular personality for 2020 in Zimbabwe.
Prophet Passion Java boosted his popularity when he entertained Zimbabweans and gave musicians employment with his Garamumba Iwe Series . Journalist Hopewell Chin'ono who pulled in huge number when he was arrested and the #zimbabweanlivesmatter and #freehopewellchinono hashtags trended for over a month.
2020 Zimbabwe Most Popular Celebrity Winner Genius "Ginimbi" Kadungure
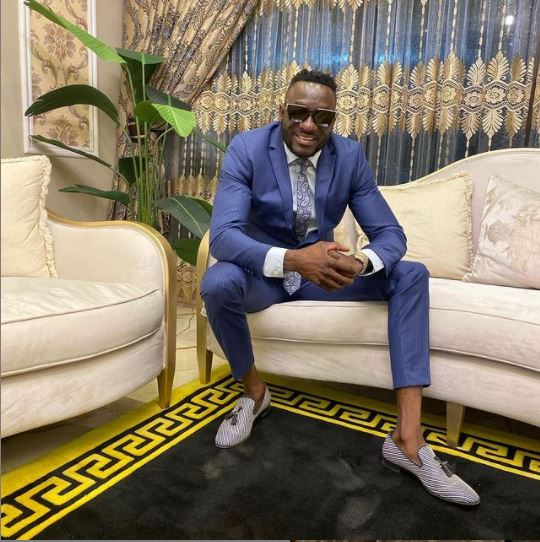
2nd Place 2020 Zimbabwe Most Popular Celebrity Prophet Passion Java
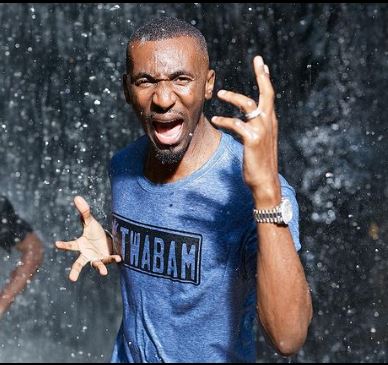
3rd 2020 Zimbabwe Most Popular Celebrity Hopewell Chin'ono
Related Story
BUSINESSMAN Genius "Ginimbi" Kadungure, who died on the spot along Liberation Legacy Way in Harare, ordinarily known by many as Borrowdale Road, when his speeding Rolls Royce collided head-on with a Honda Fit, veered off the road and hit a tree before catching fire, was with two foreigners who had come for the Saturday night party.
Limumba Karim from Malawi and a Mozambican, who was only identified as Elisha and the birthday girl, Mitchelle "Moana" Umali were burnt beyond recognition after the doors of the Rolls Royce jammed on impact and it took many hours for police and the Fire Brigade to retrieve their remains from the wreckage.
Yesterday, Ginimbi's sister, Nelia, said her brother was having fun at Dreams Nightclub and had invited his other two friends -- Karim and Elisha -- to celebrate Moana's birthday.
I did not meet the two who were involved in an accident with my brother. I only heard him saying he was going to Moana's party with friends.
"The next thing I get a phone call that my brother was involved in an accident. I am still in shock and it is scary. I arrived at the scene and saw the remains of my brother and his friends. "I am hurt. We were now four in our family thus, my sister Juliet, myself, Ginimbi and my father Anderson. The funeral wake will be at his Domboshawa home," she said.
Tinotenda Marimo, popularly known as "Dj Rimo", who was Ginimbi's close friend, described the accident as a shock. "It seems mukomana (Ginimbi) was speeding. I am trying to think of how the car exploded and hit the tree. Usually that is his time of going home after partying, the wee hours of Sunday. I am saddened and at a loss for words," he said.
Ginimbi's friends, family and other local celebrities and businesspeople gathered at the accident scene as they tried to comprehend what could have happened. Notable faces included comedienne Madam Boss, Albert Ndabambi, Jackie Ngarande, Thompson Dondo, Keen Mubaiwa and Wanisai Mtandwa (Mahwindo) among others.
One security guard identified as Martin said that he was patrolling the area when he witnessed the accident.
"I always see Ginimbi at this hour (5am) when I finish work and he will be driving to his Domboshava house. Today he had his Rolls Royce and was speeding as usual. I heard a bang and I rushed to investigate. I saw him trying to open the doors with a view to rescuing his friends.
"He was struggling to breathe and was visibly shaking. Genius was shouting for help. When I arrived, the car exploded. "The fire was scary and we could not do anything to help.
"Some neighbours gathered at the scene of the accident. We unsuccessfully tried to put out the fire using water buckets and tree branches," he said.
Ginimbi's manager identified as Shally said she was deeply hurt.
"I feel like hell. I don't even know which words to even use. Genius Kadungure has been called by God. He is no more. He was in a terrible accident around 5am and he died on the spot with three of his friends in the car, Karim, Elisha and Moana," she said.
Moana's father Mr Ishamel Amuli said he last saw his daughter early last year and was distressed and worried about her partying behaviour.
Speaking at the funeral wake in Highfield, Mr Amuli (58) told The Herald that his relationship with Moana went sour in 2017 when she left her husband.
"In 2017, Mitchelle had problems with her husband, who came to drop their child in Domboshava. Mitchelle later came to pick her daughter and I sat down with her, telling her that I wasn't happy with her behaviour. I heard a lot about my daughter that she had become a party animal and was featuring in several musical videos. I got angry and slapped her twice and she left home for good.
"Last year I saw her, but we never talked much. I am a Muslim and what she was doing was against our religion. Now how do I tell my elders at church and how will she be buried? We are now at her mother's house in Highfield because I did not fully pay lobola for her mother. I still owe in-laws, but that is a story for another day," he said. Mr Amuli said he broke up with Moana's mother while his daughter was still a toddler.
"I quit my job to look after my children. I had five children and Mitchelle was the second born and only girl. She had a daughter named Tyra. I stay in Domboshava in Chirombo Village. I used to hear some neighbours telling me that my daughter was at Ginimbi's house. Today, was told that she had a birthday party at a night club in Harare and she died on her way back," he said.
Mr Amuli broke down during the interview. Moana's funeral wake is at Number 547 Engineering, Highfield.
Burial arrangements will be announced after post-mortem.
Moana featured in several musical videos which include Takura's popular track "Zvemoyo", Enzo Ishall's "Mwenje" and Freeman's video "Muridzo".
Apart from being video vixen, she was a fitness trainer.
Burial arrangements for Ginimbi, Karim and Elisha were by last night yet to be announced.
Info News
SEO Meta Title Credit Repair vs Credit Counseling: Compare Your Options
When credit problems become stressful, two options often appear in search results: credit repair and credit counseling. They sound similar, but they are not the same service. Credit repair focuses on disputing inaccurate, incomplete, or unverifiable information on credit reports. Credit counseling focuses on budgeting, debt repayment, and financial education. Knowing the difference can help you avoid scams and choose the right help.
Credit repair companies often advertise help with removing negative items from credit reports. Legitimate credit repair is based on your legal right to dispute inaccurate information. If a late payment, collection, account balance, personal detail, or account status is wrong, you can dispute it with the credit bureaus and the company that furnished the information.
However, accurate negative information usually cannot be removed simply because it hurts your score. Late payments, collections, bankruptcies, and charge-offs may remain on credit reports for legally allowed periods if they are accurate. Be cautious with any company that promises a specific score increase, guaranteed removals, or a new credit identity.
Credit counseling is different. A nonprofit credit counseling agency can review income, expenses, debts, and goals. Counselors may help build a budget, explain credit reports, suggest repayment strategies, and discuss whether a debt management plan makes sense. A debt management plan may consolidate payments through the counseling agency and sometimes reduce interest rates or fees with participating creditors.
Credit counseling can be useful when the main problem is debt affordability. If you are making minimum payments, falling behind, or using one card to pay another, a counselor can help create a structured plan. Credit repair alone will not solve unaffordable debt.
Credit repair can be useful when the main problem is inaccurate reporting. For example, an account that does not belong to you, a debt listed twice, an incorrect late payment, a paid account still shown as unpaid, or outdated information may be disputable. You can file disputes yourself for free, but some people hire help because they do not want to manage the paperwork.
Before paying for credit repair, understand your rights. In the United States, credit repair companies must follow federal rules, including restrictions on misleading claims and upfront fees. You should receive a written contract, cancellation rights, and clear information about what the company will do. If a company pressures you, asks you to lie, tells you to dispute everything, or suggests using a different Social Security number, walk away.
A strong credit rebuilding plan often includes both cleanup and behavior changes. Start by pulling credit reports from the major bureaus. Review personal information, open accounts, closed accounts, collections, public records, inquiries, balances, and payment history. Highlight anything inaccurate and gather supporting documents.
Next, pay every current bill on time. Payment history is a major scoring factor. Set up reminders or autopay for minimum payments. Then focus on credit utilization, which is the percentage of available revolving credit being used. Lower balances can help improve scores over time.
Avoid opening too many new accounts at once. New inquiries and new accounts can lower scores temporarily. Instead, build a steady pattern: pay on time, reduce balances, keep older accounts in good standing, and monitor reports for errors.
If you have no active credit, a secured credit card or credit-builder loan may help, but fees and terms matter. Choose products from reputable banks or credit unions and avoid high-fee cards that drain your budget.
The right choice depends on the root problem. Choose credit repair if the issue is inaccurate reporting. Choose credit counseling if the issue is debt management, budgeting, or missed payments. Use both if you have errors and unaffordable debt. Most importantly, avoid anyone promising instant results. Real credit improvement takes accurate reporting, consistent payments, lower debt, and time.
High-Yield Savings vs CDs: Emergency Cash Comparison
Emergency cash should be safe, accessible, and separated from everyday spending. That is why many people compare high-yield savings accounts and certificates of deposit. Both can pay interest, both can be offered by banks or credit unions, and both can be useful. But they are not designed for the same purpose.
A high-yield savings account is a deposit account that typically pays a higher interest rate than a traditional savings account. It is designed for liquidity. You can usually transfer money when needed, making it a good option for emergency funds, short-term savings, tax reserves, travel funds, and upcoming bills.
A certificate of deposit, or CD, is a time deposit. You agree to leave money with the bank or credit union for a set term, such as a few months or several years. In exchange, the institution may offer a fixed rate. If you withdraw early, you may pay an early withdrawal penalty. That makes CDs less flexible than savings accounts but potentially useful for money you do not need immediately.
The first question is purpose. If the money is truly for emergencies, access matters more than chasing the highest rate. A job loss, car repair, medical bill, or home repair may require quick cash. A high-yield savings account is usually better for the core emergency fund because it keeps money available.
CDs can work for extra cash beyond the basic emergency fund. For example, if you want to earn interest on money set aside for a future down payment, tuition bill, or planned purchase, a CD can help lock in a rate. Some savers use a CD ladder, dividing money among several CDs with different maturity dates. This creates periodic access while still earning fixed rates.
Interest rate risk matters. A high-yield savings rate can change at any time. When market rates fall, the account yield may fall too. A CD rate is usually fixed for the term, which can be helpful if rates decline after you open it. But if rates rise, your money may be locked into a lower rate unless you accept a penalty or use special CD types.
Liquidity is the biggest difference. Savings accounts usually allow easier transfers, although banks may have transaction policies and processing times. CDs restrict access until maturity. Before opening a CD, ask how the early withdrawal penalty is calculated and whether partial withdrawals are allowed.
Fees should also be reviewed. Some savings accounts have monthly maintenance fees, minimum balance requirements, excessive transaction fees, or transfer limitations. Many online banks offer no monthly fee, but you should still read the account agreement. CDs may have fewer monthly fees but can have penalties for early withdrawal.
Safety depends on where the money is held. Bank deposits may be insured by the FDIC, and credit union deposits may be insured by the NCUA, within applicable limits and ownership categories. Always confirm that the institution is insured and understand coverage limits if you keep large balances.
Convenience is another factor. A high-yield online savings account may pay more than a traditional local bank, but transfers to your checking account may take time. Some people keep one month of expenses at their local bank and the rest in a higher-yield account. This balances access and return.
Taxes should not be ignored. Interest from savings accounts and CDs is generally taxable. The institution may issue a tax form, but you are responsible for reporting income according to tax rules. A tax professional can help with your specific situation.
A practical approach is to keep the first layer of emergency cash in checking or a linked savings account, the main emergency fund in high-yield savings, and longer-term cash goals in CDs or treasury-style alternatives if appropriate. The best mix depends on how stable your income is, how many dependents you support, and how quickly you might need the money.
High-yield savings and CDs are not rivals; they are tools. Savings accounts solve access. CDs solve rate certainty for money that can sit. When you match the account to the purpose, your cash can stay safer, more organized, and more productive.


