Saturday, October 17

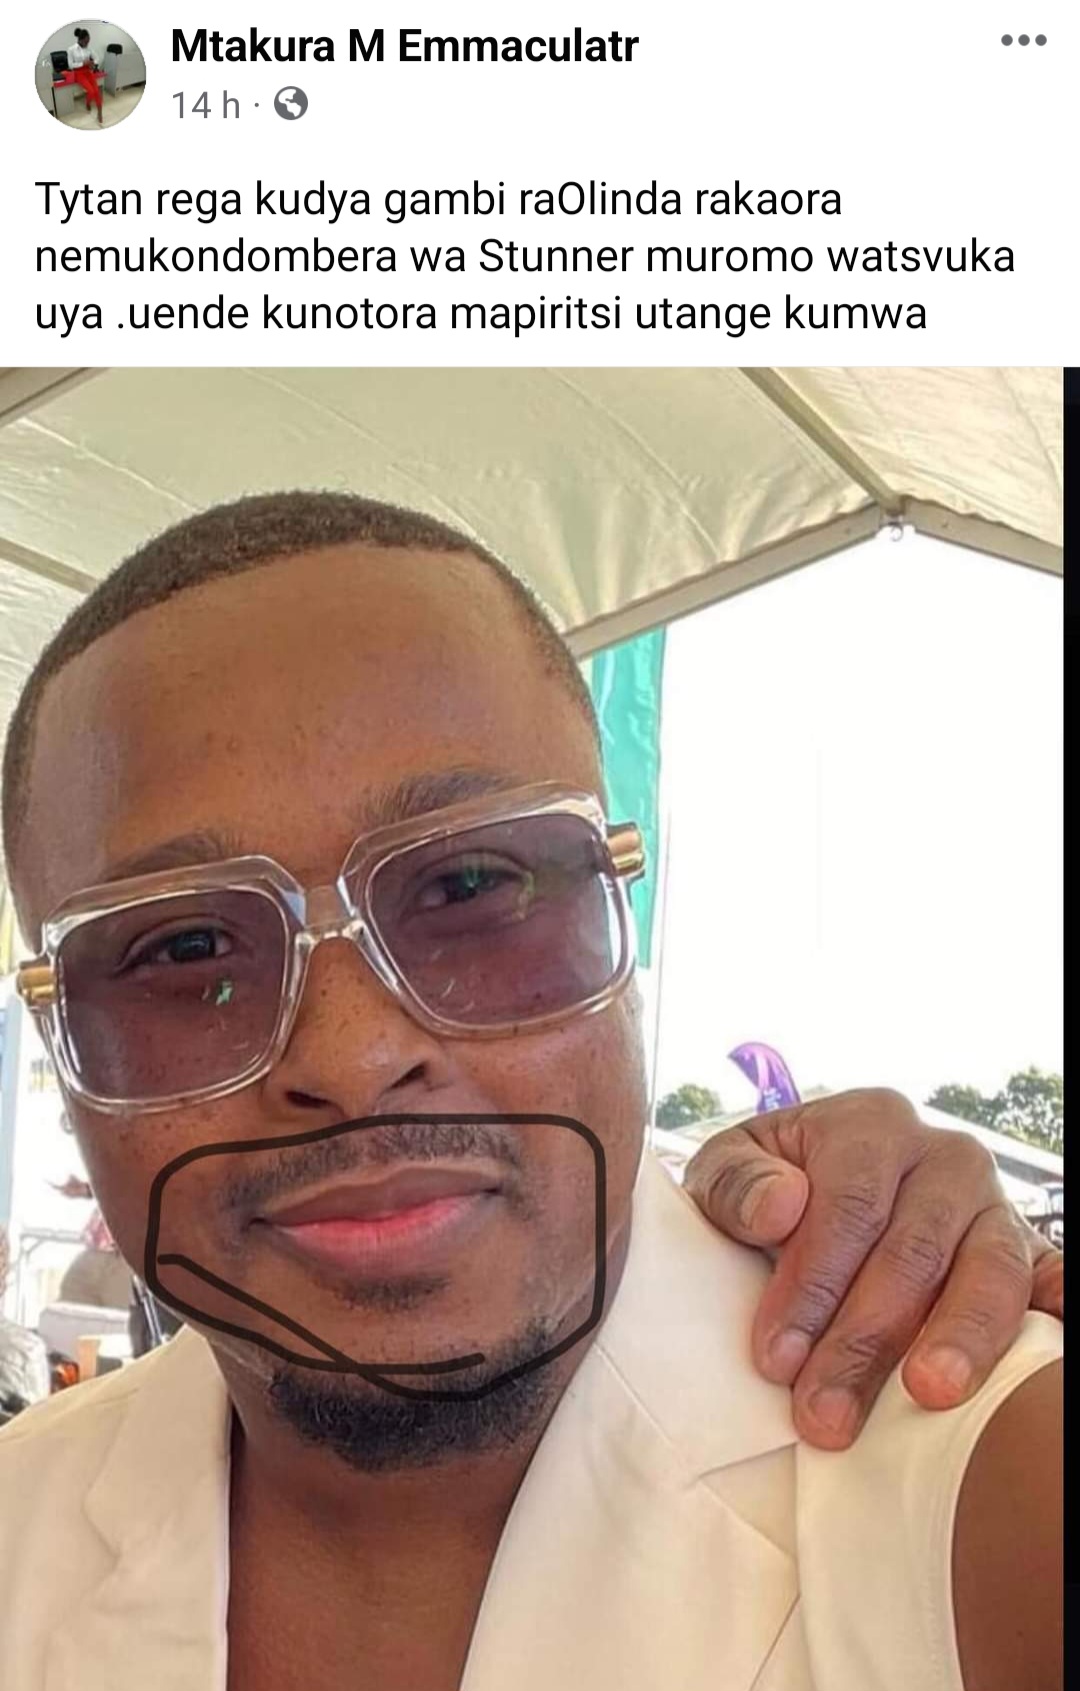
Tytan Onzi Ngaambomira Zvekudya Gambi Miromo Yokwapuka

Tytan rega kudya gambi raOlinda rakaora nemukondombera wa Stunner muromo watsvuka uya .uende kunotora mapiritsi utange kumwaHaisi hiv chete inofunura miromo munhu kana ane ma acids miromo inokwapuka chero sugar inozviita saka tisangoti akwapuka miromo muzvezve,,,, muchatadzisa vanhu kuenda kuzvipatara kunorapwa achingoti pamwe i aids yandibataSome naturally vakangodaro vamwe ndovatsvuka miromo nekumwa ma zvibhodhoroKumashure kweghost kunemunhu hako anofema, anotofamba ,anofanira kunge anemoyo ,anofanira kunzwa hana ichirova kuti apa ndazonyanyawo apa chero ndiri ghost hangu asi apa ndanyanya.

  • Share:

Info News

Assisted Living Costs: How Families Can Plan For Senior Care

Assisted living can provide seniors with housing, meals, personal care, medication support, social activities, and help with daily tasks. But the cost can be a major concern for families.

rnrn

Assisted living costs vary based on location, facility type, room size, care needs, and services included. Some communities charge a base monthly fee, while others add costs for medication management, bathing assistance, memory care, transportation, or special medical needs.

rnrn

Families should ask what is included in the monthly price. Meals, housekeeping, laundry, utilities, activities, and basic care may be included, but higher levels of care may cost extra.

rnrn

Memory care is usually more expensive than standard assisted living because it provides specialized support for people with Alzheimer’s disease or dementia.

rnrn

Medicare usually does not pay for long-term assisted living room and board. Medicaid may help in some states for eligible individuals, but rules vary. Long-term care insurance may also help if the policy includes assisted living benefits.

rnrn

Families may pay through retirement savings, pensions, Social Security, home sale proceeds, long-term care insurance, or family contributions.

rnrn

Before choosing a facility, visit in person. Pay attention to cleanliness, staff attitude, safety, food quality, resident activities, and how residents are treated.

rnrn

Ask about staffing levels, emergency procedures, medication policies, move-out rules, price increases, and care assessments.

rnrn

Planning early can reduce stress. Waiting until a crisis happens may limit choices and increase pressure.

rnrn

Assisted living is not just about cost. It is about safety, dignity, comfort, and quality of life. The right community can help seniors stay independent while getting the support they need.

rnrn

Families should compare options carefully and choose a place that fits both care needs and budget.

rn

Mortgage Refinancing Options Homeowners Should Consider in 2026

Understanding Mortgage Refinancing

rnrn

Mortgage refinancing allows homeowners to replace their existing home loan with a new mortgage that offers updated terms, lower interest rates, or improved financial flexibility. Millions of homeowners refinance their mortgages to reduce monthly payments, shorten loan terms, or access home equity for major expenses.

rnrn

As interest rates fluctuate in 2026, refinancing continues to attract homeowners looking for long-term savings opportunities. Even a small reduction in interest rates can save borrowers thousands of dollars over the life of a loan. Refinancing can also help borrowers transition from adjustable-rate mortgages to more stable fixed-rate loan structures.

rnrn

Homeowners considering refinancing should evaluate their financial goals carefully before applying. Some borrowers focus on reducing monthly payments, while others prioritize paying off mortgages faster or consolidating debt using home equity.

rnrn

Benefits of Refinancing Your Mortgage

rnrn

One of the biggest benefits of mortgage refinancing is lower monthly payments. Reduced interest rates can significantly improve household cash flow, allowing homeowners to save more money or manage other financial obligations more comfortably.

rnrn

Refinancing may also shorten the loan repayment period. Some homeowners switch from 30-year mortgages to 15-year loans to reduce long-term interest expenses and build home equity faster.

rnrn

Cash-out refinancing is another popular option. This allows homeowners to borrow against accumulated home equity to finance renovations, education expenses, business investments, or debt consolidation.

rnrn

Factors to Consider Before Refinancing

rnrn

Although refinancing offers many advantages, homeowners should carefully compare lender fees, closing costs, and loan terms before making decisions. Refinancing costs may include appraisal fees, loan origination charges, title insurance, and legal expenses.

rnrn

Credit scores play a major role in refinancing approval and interest rates. Borrowers with stronger credit profiles generally qualify for more competitive terms and lower rates.

rnrn

Timing is also important. Homeowners planning to move within a short period may not benefit enough from refinancing savings to justify upfront costs.

rnrn

Final Thoughts

rnrn

Mortgage refinancing remains a powerful financial tool for homeowners seeking lower payments, improved loan terms, or greater financial flexibility. Careful planning and lender comparison can help borrowers maximize savings and avoid unnecessary expenses.

rnrn

By understanding refinancing options and evaluating long-term goals, homeowners can make smarter financial decisions that support long-term stability and wealth growth.

rn