Wednesday, October 07

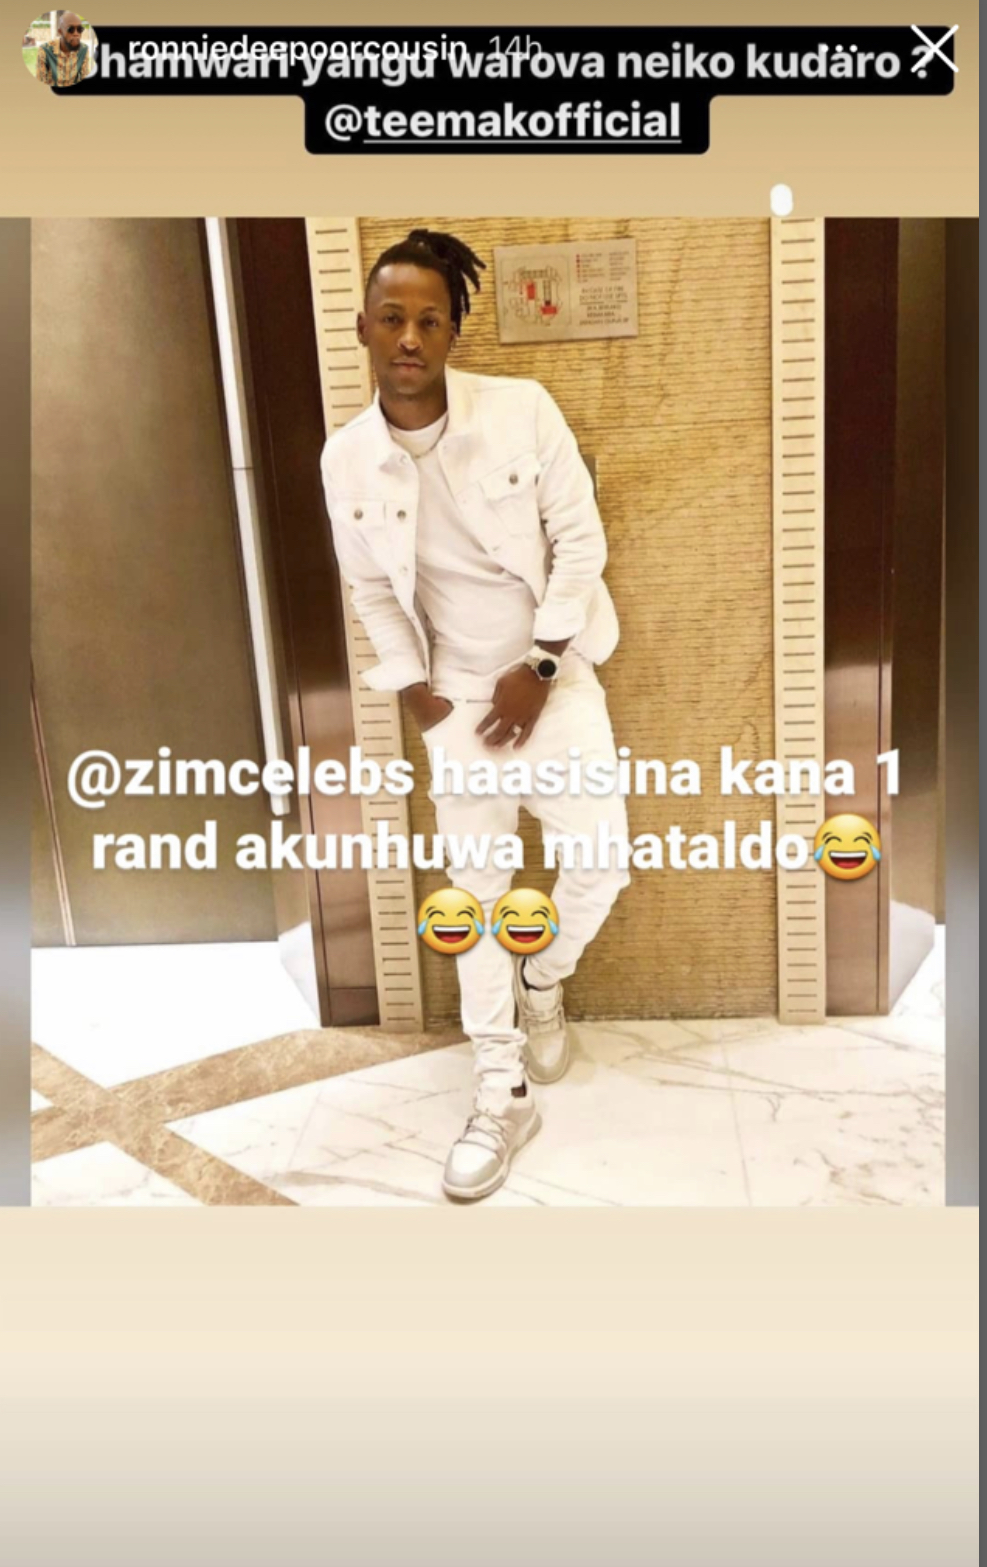
Socialite RonnieDee Blasts Teemak Haasisina Kana 1 Rand Akunhuwa Mhataldo

Socialite RonnieDee is not holding back his feelings for Teemak who was exposed as a scammer a few months back. Teemak was exposed for scamming over 350K from Zimbabweans with his Forex Trading business. Teemak is accused of scamming friends and  Zimbabwean government officials. 

RonnieDee who announced that Teemak scammed him $2000 USD which Teemak borrowed but never returned. RonnieDee posted the following on his Instagram.

Related Story 

DJTowers & RonnieDee Beak Their Silent Teemak Taona Chipunza Imbavha He Is Stealing Money From People

DJTowers and RonnieDee have broken thier silence about Teemak Taona Chipunza scaming Zimbabweans with his forex trading scam. DJTowers who is responcible for making Teeman kfamous and getting a car for it has not commented on the issue until today. RonnieDee shared his thoughts and DJTowers told fans i total agree with what Roonie is saying. watc hthe video below.

Teemak is accused of stealing over $350k from Zimbabwean all over the diaspora by scamming them to invest in his fake investment trading scheme. Investros have been trying to recover thier funds for months. Teemak has been hiding for the last few month and has deactivated all his social media accounts.

Related Story

A youthful Zimbabwean man, who always dresses in white attire to signify his supposed wealth, has courted trouble after allegedly duping scores of Zimbabweans living locally and abroad through an investment scam.


24-year-old Taona Oswald Chipunza – better known as Teemak in music circles –duped unsuspecting investors that include cabinet ministers, high net worth earners, church leaders and ordinary folk alike. Chipunza is said to have assured his alleged victims, dotted around the globe, of massive financial windfall on their investment. However, the scheme, with all the marks of serious foreign exchange fraud, collapsed spectacularly at the end of June.

Those based in the United States, Germany, Malaysia, United Arab Emirates, South Africa and China say they have lodged police reports in their various jurisdictions, desperately hoping to draw the attention of Interpol.

“We need to stop this boy before he strikes again,” one disgruntled client said by telephone from the US. Chipunza, though, insists that his hedge-fund, as well as the investment vehicles he runs, are above board.

However, what has left the investors shaken is that a quick search revealed that the entities are not registered with state regulators, and have no legitimate earnings.


In his defence, Chipunza says the money owed to individuals had not been paid at the initially promised date of July 31 as he was behind on trading targets.

  • Share:

Info News

Mortgage Refinancing: Lower Your Payments and Save More Over Time

Mortgage refinancing is one of the most effective financial strategies homeowners can use to reduce monthly payments, lower interest rates, or access home equity. By replacing your existing mortgage with a new loan that has better terms, you can potentially save thousands of dollars over the life of your loan. Whether you're looking for low interest mortgage rates, cash-out refinancing options, or fixed-rate home loans, understanding how refinancing works is essential before making a decision.

rnrn

Refinancing is especially popular when interest rates drop or when a homeowner’s credit score improves. Many borrowers take advantage of refinancing to switch from an adjustable-rate mortgage (ARM) to a fixed-rate mortgage, providing long-term financial stability. Others use cash-out refinancing to tap into their home’s equity, allowing them to fund renovations, consolidate debt, or invest in other opportunities. While refinancing offers many benefits, it’s important to carefully evaluate your goals and financial situation to ensure it’s the right move.

rnrn

How Mortgage Refinancing Works

rnrn

When you refinance your mortgage, you essentially take out a new loan to pay off your existing one. The new loan comes with updated terms, including a new interest rate, repayment period, and monthly payment. Lenders will evaluate your financial profile, including your credit score, income, debt-to-income ratio, and home value, to determine eligibility.

rnrn

The process typically involves submitting an application, providing documentation, and undergoing a home appraisal. Once approved, the new loan replaces your current mortgage, and you begin making payments under the new terms. Many homeowners search for best mortgage refinance lenders to ensure they secure the most favorable deal.

rnrn

Benefits of Refinancing Your Mortgage

rnrn

One of the biggest advantages of refinancing is the opportunity to secure a lower interest rate. Even a small reduction in your rate can lead to significant savings over time. Lower monthly payments can free up cash flow, making it easier to manage other financial responsibilities.

rnrn

Another benefit is the ability to shorten your loan term. For example, switching from a 30-year mortgage to a 15-year loan allows you to pay off your home faster and reduce total interest costs. Additionally, cash-out refinancing gives homeowners access to funds for major expenses, often at lower interest rates than personal loans or credit cards.

rnrn

When Is the Right Time to Refinance?

rnrn

Timing plays a critical role in refinancing decisions. Homeowners should consider refinancing when interest rates are significantly lower than their current rate. A general rule of thumb is that reducing your rate by at least 1% can make refinancing worthwhile.

rnrn

Improving your credit score can also help you qualify for better loan terms. If your financial situation has improved since you first obtained your mortgage, refinancing could provide substantial savings. Additionally, homeowners planning to stay in their property long-term are more likely to benefit from refinancing, as it takes time to recover closing costs.

rnrn

Costs and Considerations

rnrn

While refinancing offers many benefits, it’s important to consider the associated costs. These may include application fees, appraisal fees, and closing costs, which can range from 2% to 5% of the loan amount. Calculating your break-even point—the time it takes to recover these costs—is essential before proceeding.

rnrn

Borrowers should also be cautious about extending their loan term, as this can increase the total amount of interest paid over time. Working with a trusted mortgage refinancing company can help you evaluate your options and make an informed decision.

rnrn

Final Thoughts

rnrn

Mortgage refinancing can be a powerful tool for improving your financial situation, but it requires careful planning and research. By understanding the process, comparing lenders, and evaluating your long-term goals, you can make a decision that aligns with your needs. Whether you’re looking to reduce monthly payments or access equity, refinancing offers opportunities for greater financial flexibility.

rnrn


rnrn

Financial experts recommend working with licensed mortgage lenders, certified financial advisors, and reputable home loan providers when considering refinancing options. Professional guidance ensures better loan terms and long-term financial stability.

rn

SEO Meta Title Health Insurance for Self-Employed: Plan Comparison Guide

Self-employed workers face a different health insurance challenge than employees with a company plan. Freelancers, consultants, rideshare drivers, small business owners, real estate agents, and independent contractors must compare coverage, costs, networks, and tax issues on their own. The best plan is not always the cheapest monthly premium. It is the plan that fits your health needs, budget, doctors, prescriptions, and risk tolerance.

Start with the total yearly cost, not just the premium. The monthly premium is the amount you pay to keep coverage active, but it is only one part of the expense. You also need to review the deductible, copays, coinsurance, out-of-pocket maximum, prescription costs, and whether your preferred doctors are in network. A low premium plan can be expensive if you need frequent care and the deductible is high.

Plan networks matter. Health maintenance organization plans may have lower premiums but may require you to use a narrower network and choose a primary care doctor. Preferred provider organization plans may offer more flexibility but often cost more. Exclusive provider organization plans and point-of-service plans have their own rules. Before enrolling, search the insurer's current provider directory and confirm directly with important doctors because directories can change.

Prescription coverage can make or break a plan. Review the formulary, which is the insurer's list of covered drugs. Check whether your medications are generic, preferred brand, non-preferred brand, or specialty tier. Also look for prior authorization, step therapy, and quantity limits. A plan with a lower premium can become costly if a key medication is not covered well.

If you rarely visit the doctor and mainly want protection against major medical bills, a higher deductible plan may be worth considering. Some high-deductible plans can be paired with a health savings account if they meet specific rules. A health savings account may offer tax advantages, but eligibility and contribution limits can change, so verify current rules with a qualified tax professional or official sources.

If you expect surgery, pregnancy care, ongoing prescriptions, specialist visits, physical therapy, or regular mental health care, a higher premium plan with lower out-of-pocket costs may be smarter. The best comparison is to estimate your likely yearly medical use and calculate what you would pay under each plan.

Self-employed people should also review subsidies and tax deductions. Depending on income and household size, marketplace plans may qualify for premium tax credits. Income estimates are important because overestimating or underestimating can affect costs and reconciliation at tax time. Self-employed health insurance deductions may also be available, but rules depend on your business structure, profit, other coverage access, and tax situation.

Do not ignore dental and vision coverage. Marketplace medical plans may not include adult dental or vision benefits. If those services matter to you, compare standalone plans or discount programs. Also review whether children need pediatric dental coverage.

Short-term health plans, health care sharing ministries, and limited benefit plans may look attractive because of lower monthly costs, but they may not cover pre-existing conditions, essential health benefits, prescriptions, maternity care, mental health, or major claims the way comprehensive health insurance does. Read exclusions carefully before choosing a nontraditional option.

Open enrollment deadlines are important. You usually need a qualifying life event to enroll outside the regular window. Examples may include losing other coverage, moving, marriage, divorce, birth, adoption, or certain income changes. Rules vary, so check official marketplace guidance for your state.

When comparing plans, make a simple worksheet with columns for premium, deductible, out-of-pocket maximum, primary care copay, specialist copay, urgent care, emergency room, prescription tiers, network type, key doctors, key medications, and estimated annual cost. This turns a confusing decision into a side-by-side comparison.

Health insurance is a financial planning decision as much as a medical decision. Self-employed workers need coverage that protects their health and their business income. A plan that keeps care accessible can prevent a medical issue from becoming a financial crisis.