Thursday, October 08

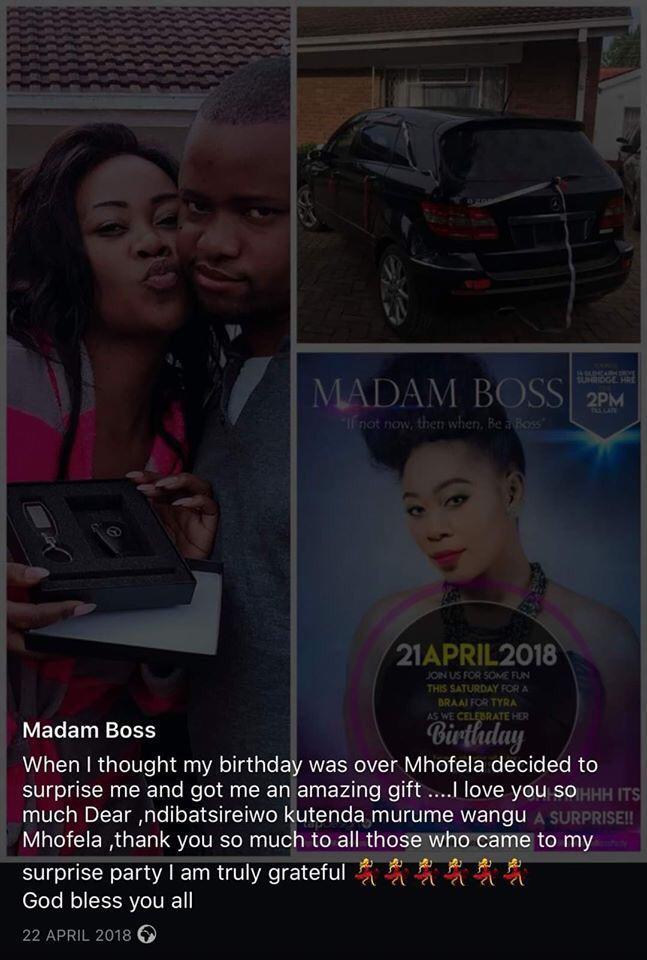
Prophet Passion Java Bought Me The Car Not Mhofela : Madam Boss Admits

Popular comedian Tyra “Madam Boss” Chikocho has confirmed claims that the controversial Prophet Passion Java bought her a car after she had visited his church service. On a telephone interview with this publication today, Chikocho lambasted everyone who was speaking ill about her pertaining the car as she narrated her first encounter with the prophet which led to the car being bought for her.

“I was invited at his church event by a friend and l sited in the front row when l saw the Prophet entered dishing out cars l think to people who had remained loyal to his church whilst he was out of the country.

“When he approached me he said l am surprised that Madam Boss has come to church please what can l do for you. I jokingly made a gesture of a car and he said to me you will get a car within a week and I surely got one,” she said.

The car issue recently came to light after socialite Laura Tatenda Tsonzi shared a post dissing Prophet Passion saying he does not know how to keep a secret.

“…varikuti mota ndeya 2018 yes its true ndeya 2018 yaimbova secrete by manje Java haagoni pakati secrete pacho….one way or the other anobuditsa chete,” read part of the post.

Chikocho, however, scolded everyone who is speculating that she had sexual affair with the man of God in order to get the car saying that they are misinformed and she didn’t care.

“ I don’t have anything against Prophet Passion  and just because he is not liked by many doesn’t make me deny gifts coming from him,” she added.

The musician-cum-comedian said that she is not offended by the fact that people are walking around saying she prostituted for the car whilst she counts herself lucky to have gotten the gift from Java.

“ Zvekunzi madam boss ihure hazvisi zvinew one , who doesn’t know that l had been constantly been called a hure…mapedestrian mazhinji ndoari kutaura kuti Madam Boss vakahurira mota,” she said.

Known in various circles as a comedian, musician, corporate brand ambassador fashionist, Tyra Chikocho is a housewife married to Ngoni Munetsiwa and the two have a daughter.

Madam Boss Had tried to make it as if Mhofel bought the car for her birthday when  it was actually prophet passion who paid for the car

  • Share:

Info News

High-Yield Savings vs CDs: Emergency Cash Comparison

Emergency cash should be safe, accessible, and separated from everyday spending. That is why many people compare high-yield savings accounts and certificates of deposit. Both can pay interest, both can be offered by banks or credit unions, and both can be useful. But they are not designed for the same purpose.

A high-yield savings account is a deposit account that typically pays a higher interest rate than a traditional savings account. It is designed for liquidity. You can usually transfer money when needed, making it a good option for emergency funds, short-term savings, tax reserves, travel funds, and upcoming bills.

A certificate of deposit, or CD, is a time deposit. You agree to leave money with the bank or credit union for a set term, such as a few months or several years. In exchange, the institution may offer a fixed rate. If you withdraw early, you may pay an early withdrawal penalty. That makes CDs less flexible than savings accounts but potentially useful for money you do not need immediately.

The first question is purpose. If the money is truly for emergencies, access matters more than chasing the highest rate. A job loss, car repair, medical bill, or home repair may require quick cash. A high-yield savings account is usually better for the core emergency fund because it keeps money available.

CDs can work for extra cash beyond the basic emergency fund. For example, if you want to earn interest on money set aside for a future down payment, tuition bill, or planned purchase, a CD can help lock in a rate. Some savers use a CD ladder, dividing money among several CDs with different maturity dates. This creates periodic access while still earning fixed rates.

Interest rate risk matters. A high-yield savings rate can change at any time. When market rates fall, the account yield may fall too. A CD rate is usually fixed for the term, which can be helpful if rates decline after you open it. But if rates rise, your money may be locked into a lower rate unless you accept a penalty or use special CD types.

Liquidity is the biggest difference. Savings accounts usually allow easier transfers, although banks may have transaction policies and processing times. CDs restrict access until maturity. Before opening a CD, ask how the early withdrawal penalty is calculated and whether partial withdrawals are allowed.

Fees should also be reviewed. Some savings accounts have monthly maintenance fees, minimum balance requirements, excessive transaction fees, or transfer limitations. Many online banks offer no monthly fee, but you should still read the account agreement. CDs may have fewer monthly fees but can have penalties for early withdrawal.

Safety depends on where the money is held. Bank deposits may be insured by the FDIC, and credit union deposits may be insured by the NCUA, within applicable limits and ownership categories. Always confirm that the institution is insured and understand coverage limits if you keep large balances.

Convenience is another factor. A high-yield online savings account may pay more than a traditional local bank, but transfers to your checking account may take time. Some people keep one month of expenses at their local bank and the rest in a higher-yield account. This balances access and return.

Taxes should not be ignored. Interest from savings accounts and CDs is generally taxable. The institution may issue a tax form, but you are responsible for reporting income according to tax rules. A tax professional can help with your specific situation.

A practical approach is to keep the first layer of emergency cash in checking or a linked savings account, the main emergency fund in high-yield savings, and longer-term cash goals in CDs or treasury-style alternatives if appropriate. The best mix depends on how stable your income is, how many dependents you support, and how quickly you might need the money.

High-yield savings and CDs are not rivals; they are tools. Savings accounts solve access. CDs solve rate certainty for money that can sit. When you match the account to the purpose, your cash can stay safer, more organized, and more productive.

Medicare Advantage Plans: Benefits, Costs, Networks, and What to Know Before Enrolling

Medicare Advantage plans, Medicare Part C, best Medicare Advantage plans, Medicare Advantage coverage, Medicare Advantage cost, Medicare HMO, Medicare PPO

rnrn

Medicare Advantage Plans: What You Need to Know

rnrn

Medicare Advantage plans are one of the most popular Medicare coverage choices. They are also one of the most misunderstood.

rnrn

A Medicare Advantage plan, also called Part C, is an alternative way to receive Medicare benefits. These plans are offered by private insurance companies approved by Medicare.

rnrn

Medicare explains that Medicare Advantage plans provide Part A and Part B benefits, and they are generally offered by private companies that contract with Medicare.

rnrn

What Does Medicare Advantage Cover?

rnrn

Medicare Advantage plans must provide Medicare Part A and Part B benefits. Many plans also include prescription drug coverage, often called MAPD coverage.

rnrn

Some plans may also offer extra benefits, depending on the plan and service area.

rnrn

These may include:

rnrn

Dental
rnVision
rnHearing
rnFitness benefits
rnOver-the-counter allowance
rnTransportation
rnWellness programs
rnMeal benefits after hospital stays

rnrn

Benefits vary. Always read the plan documents.

rnrn

Types of Medicare Advantage Plans

rnrn

Medicare lists several types of Medicare Advantage plans, including HMO, PPO, PFFS, SNP, and MSA plans.

rnrn

HMO Plans

rnrn

Health Maintenance Organization plans usually require you to use network providers, except in emergencies. You may need referrals for specialists.

rnrn

PPO Plans

rnrn

Preferred Provider Organization plans usually give more flexibility than HMOs. You may pay less in network and more out of network.

rnrn

SNP Plans

rnrn

Special Needs Plans are designed for people with certain diseases, specific care needs, or certain financial situations.

rnrn

PFFS Plans

rnrn

Private Fee-for-Service plans determine how much they pay providers and how much you pay when receiving care.

rnrn

MSA Plans

rnrn

Medical Savings Account plans combine a high-deductible plan with a medical savings account.

rnrn

Medicare Advantage Costs

rnrn

Costs vary by plan and location.

rnrn

You may pay:

rnrn

Monthly premium
rnPart B premium
rnDeductible
rnPrimary care copay
rnSpecialist copay
rnHospital copay
rnDrug copays
rnCoinsurance
rnOut-of-network costs
rnMaximum out-of-pocket amount

rnrn

A $0 premium plan does not mean free health care. You may still have copays, coinsurance, drug costs, and network rules.

rnrn

Why Provider Networks Matter

rnrn

Provider networks are one of the biggest Medicare Advantage issues.

rnrn

Before enrolling, confirm:

rnrn

Your primary doctor accepts the plan
rnYour specialists are in network
rnYour preferred hospital is covered
rnYour pharmacy is preferred
rnYour medications are covered
rnYou understand referral rules

rnrn

Do not rely only on old provider lists. Confirm directly with the provider and the plan.

rnrn

Prescription Drug Coverage

rnrn

Many Medicare Advantage plans include Part D drug coverage.

rnrn

Check:

rnrn

Medication formulary
rnDrug tier
rnPreferred pharmacies
rnMail-order pricing
rnPrior authorization
rnStep therapy
rnCoverage restrictions

rnrn

Medicare Part D helps pay for brand-name and generic drugs, but coverage details vary by plan.

rnrn

Medicare Advantage Pros

rnrn

Potential advantages include:

rnrn

Bundled coverage
rnPossible drug coverage included
rnExtra benefits
rnAnnual out-of-pocket limit
rnCoordinated care
rnLower monthly premium options
rnLocal plan support

rnrn

Medicare Advantage Cons

rnrn

Potential disadvantages include:

rnrn

Provider networks
rnPrior authorization
rnReferral rules
rnOut-of-network costs
rnPlan changes each year
rnLimited travel flexibility
rnDifferent rules by county

rnrn

A plan that works well for one person may not work well for another.

rnrn

Who May Like Medicare Advantage?

rnrn

Medicare Advantage may be attractive for people who:

rnrn

Want bundled coverage
rnUse doctors in the plan network
rnPrefer lower monthly premiums
rnWant dental, vision, or hearing extras
rnDo not travel often for care
rnAre comfortable with plan rules

rnrn

Who May Want to Compare Carefully?

rnrn

Compare carefully if you:

rnrn

Travel frequently
rnUse many specialists
rnHave expensive medications
rnNeed out-of-network flexibility
rnReceive care across multiple states
rnHave complex medical conditions
rnPrefer Original Medicare provider access

rnrn

Final Thoughts

rnrn

Medicare Advantage plans can be a good fit for many people, but you must compare carefully.

rnrn

Do not choose based only on premium or extra benefits. Check doctors, hospitals, prescriptions, referrals, out-of-pocket limits, and plan rules.

rnrn

The right Medicare Advantage plan should match your real health care life.

rn