Monday, October 05

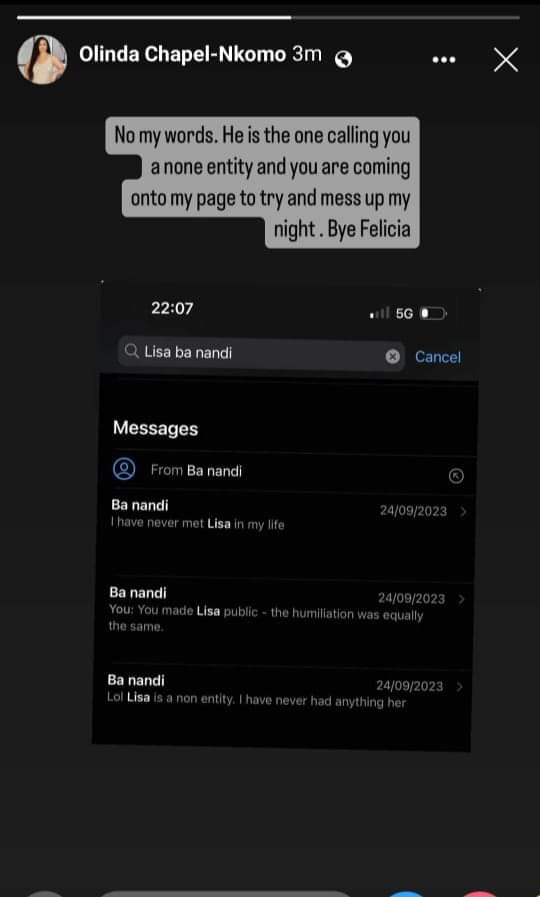
Olinda Hazvina Kumira Mushe Ofumura Lisa Chihure Chake Na Tytan Ma Message Aitumirwa Zvese

Olinda Haasi Kufara nechihure cha tytan na Lisa in the UK  Opopota zvekuti .Olinda chapero atanga zvaksre nehusiku huno here?

  • Share:

Info News

Solar Energy Solutions in 2026: How to Save Money and Invest in Renewable Power

Introduction

rnrn

Solar energy is rapidly becoming one of the most popular renewable energy solutions. Homeowners and businesses searching for “solar panel installation” are often ready to invest in long-term savings.

rnrn
rn

How Solar Energy Works

rnrn

Solar panels convert sunlight into electricity using photovoltaic cells.

rnrn
rn

Benefits

rnrn
    rn
  • Lower electricity bills
  • rn
  • Environmental sustainability
  • rn
  • Government incentives
  • rn
rnrn
rn

Costs and ROI

rnrn

Initial investment can be high, but long-term savings offset costs.

rnrn
rn

Choosing a Solar Provider

rnrn

Look for certifications, warranties, and experience.

rnrn
rn

Future Trends

rnrn

Battery storage and smart grids.

rnrn
rn

FAQ

rnrn

Are solar panels worth it?
rnYes, especially with incentives.

rn

Home Equity Loan vs HELOC: Which One Is Better?

Homeowners who have built equity may be able to borrow against their home. Two common options are a home equity loan and a home equity line of credit, also called a HELOC.

rnrn

A home equity loan gives you a lump sum of money with a fixed interest rate and fixed monthly payments. This can be useful for one-time expenses such as home renovations, medical bills, debt consolidation, or major repairs.

rnrn

A HELOC works more like a credit card. You get access to a credit line and can borrow as needed during the draw period. HELOCs often have variable interest rates, which means your payment can change over time.

rnrn

The best choice depends on your needs. If you know exactly how much money you need and want predictable payments, a home equity loan may be better. If you want flexibility and do not need all the money at once, a HELOC may be a better fit.

rnrn

Both options use your home as collateral. This means if you cannot repay the loan, your home could be at risk. That is why you should borrow carefully.

rnrn

Home equity financing may be used for home improvements, which can increase property value. However, using home equity for vacations, luxury purchases, or short-term spending can be risky.

rnrn

Before applying, compare interest rates, fees, repayment terms, minimum payments, and closing costs. Also ask whether the rate is fixed or variable.

rnrn

Your credit score, income, debt, home value, and available equity will affect approval.

rnrn

A home equity loan and HELOC can both be powerful financial tools, but they should be used responsibly. The right choice depends on whether you need stability, flexibility, or a combination of both.

rn