Monday, September 14

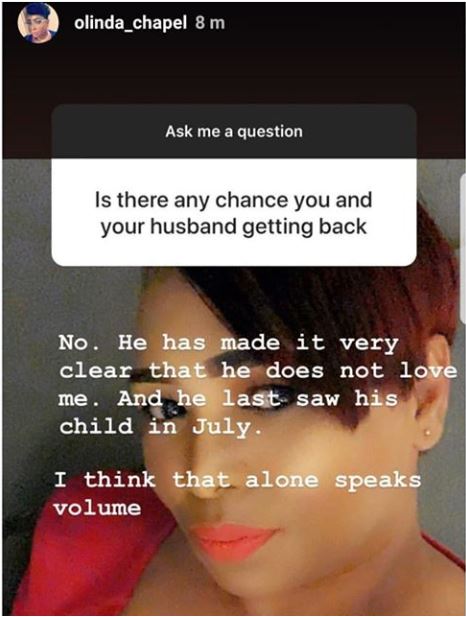
Olinda Chapel Its 100% Over I Will Never Go Back To Tytan

Olinda Chapel posted on her Instagram confirming that its 100% over between her and her husband for 6 months Tytan. Olinda confirmed that there was no reconciliation in the works.

  • Share:

Info News

Best Mortgage Refinance Companies for Homeowners With Equity

rn
rn

Mortgage refinancing activity is rising again in 2026.

rnrn

Homeowners with strong equity positions are searching for ways to lower payments, reduce interest costs, or access cash for major expenses.

rnrn

But refinancing is not always automatically smart.

rnrn

The details matter.

rnrn

Why Homeowners Refinance

rnrn

People refinance for several reasons.

rnrn

These include:

rnrn
    rn
  • Lower interest rates
  • rn
  • Debt consolidation
  • rn
  • Home renovations
  • rn
  • Cash-out refinancing
  • rn
  • Shorter loan terms
  • rn
rnrn

The right refinance strategy depends heavily on financial goals.

rnrn

What Lenders Evaluate

rnrn

Mortgage refinance companies usually review:

rnrn
    rn
  • Credit scores
  • rn
  • Home equity
  • rn
  • Debt-to-income ratios
  • rn
  • Employment history
  • rn
  • Property value
  • rn
rnrn

Borrowers with strong equity often qualify for better rates.

rnrn

Risks of Refinancing

rnrn

Refinancing can create problems if borrowers ignore:

rnrn
    rn
  • Closing costs
  • rn
  • Extended loan terms
  • rn
  • Adjustable-rate risks
  • rn
  • Reduced home equity
  • rn
rnrn

Lower monthly payments do not always mean lower long-term costs.

rnrn

Final Takeaway

rnrn

The best mortgage refinance companies help borrowers balance interest savings, long-term financial goals, and loan flexibility.

rnrn

A refinance should improve financial stability instead of creating new debt pressure.

rnrn

FAQ

rnrn

What credit score is needed to refinance?

rnrn

Requirements vary, though stronger credit usually improves rates.

rnrn

Is refinancing worth it in 2026?

rnrn

It depends on interest rates, equity levels, and long-term financial goals.

rn
rn
rnrn


rn

Assisted Living Costs: How Families Can Plan For Senior Care

Assisted living can provide seniors with housing, meals, personal care, medication support, social activities, and help with daily tasks. But the cost can be a major concern for families.

rnrn

Assisted living costs vary based on location, facility type, room size, care needs, and services included. Some communities charge a base monthly fee, while others add costs for medication management, bathing assistance, memory care, transportation, or special medical needs.

rnrn

Families should ask what is included in the monthly price. Meals, housekeeping, laundry, utilities, activities, and basic care may be included, but higher levels of care may cost extra.

rnrn

Memory care is usually more expensive than standard assisted living because it provides specialized support for people with Alzheimer’s disease or dementia.

rnrn

Medicare usually does not pay for long-term assisted living room and board. Medicaid may help in some states for eligible individuals, but rules vary. Long-term care insurance may also help if the policy includes assisted living benefits.

rnrn

Families may pay through retirement savings, pensions, Social Security, home sale proceeds, long-term care insurance, or family contributions.

rnrn

Before choosing a facility, visit in person. Pay attention to cleanliness, staff attitude, safety, food quality, resident activities, and how residents are treated.

rnrn

Ask about staffing levels, emergency procedures, medication policies, move-out rules, price increases, and care assessments.

rnrn

Planning early can reduce stress. Waiting until a crisis happens may limit choices and increase pressure.

rnrn

Assisted living is not just about cost. It is about safety, dignity, comfort, and quality of life. The right community can help seniors stay independent while getting the support they need.

rnrn

Families should compare options carefully and choose a place that fits both care needs and budget.

rn