Tuesday, September 29

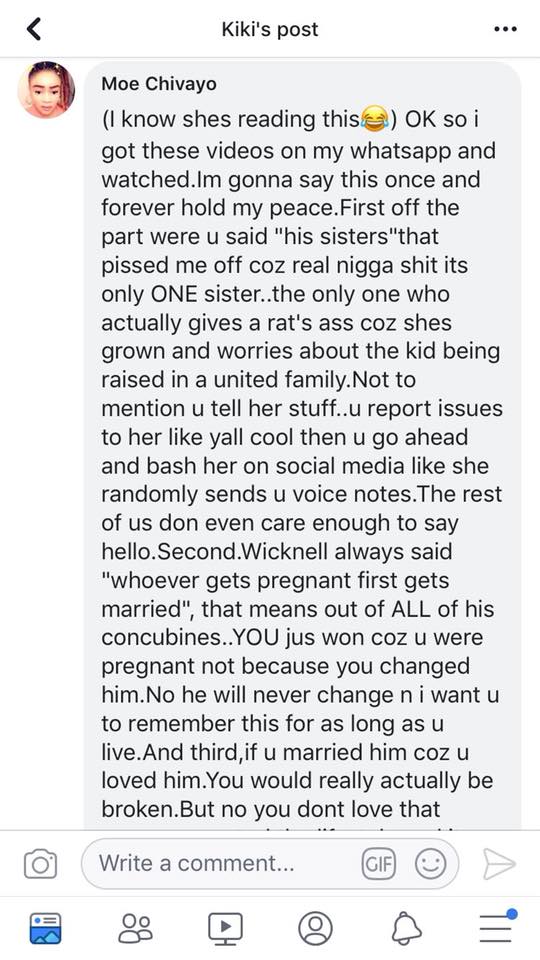
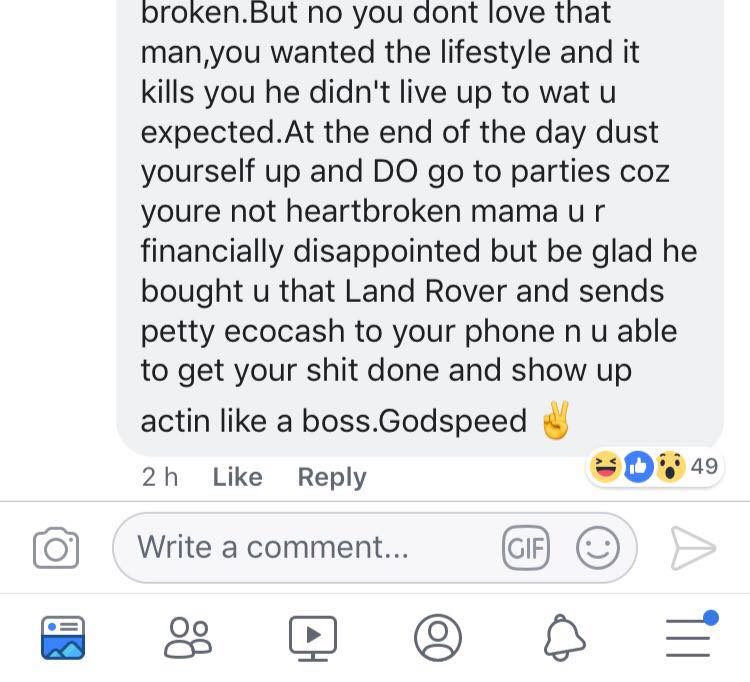
Moe Chivayo Puts Sir Wicknells Wife on Blast

The Zimbabwean Facebook community was in shock over the weekend when Moe Chivayo the sister on Business Tycon Sir Wicknell posted the messages below on her social media.

The messges are directed to Sir Wicknel wife Sonja Madzikanda. Zimbolivenews is shocked to why Moe posted this on social media. Read the statements  below and cooment if you know whats going on between the 2 sister in laws.

  • Share:

Info News

Divorce Attorney: How to Protect Your Assets

Divorce Attorney: How to Protect Your Assets

Divorce can be emotional, stressful, and financially difficult. If you own property, retirement accounts, a business, or shared debts, hiring a divorce attorney may help protect your financial future.

A good divorce lawyer can explain your rights and help you understand how property division works. In many divorces, couples must divide homes, bank accounts, vehicles, retirement funds, credit card debt, and other assets. Without proper guidance, one person may accept an unfair agreement.

Why Asset Protection Matters

An asset protection divorce strategy can help identify what is marital property and what may be separate property. Marital property usually includes assets gained during the marriage. Separate property may include assets owned before marriage, inheritance, or gifts, depending on state law.

A family law attorney can also help with hidden assets, business valuation, spousal support, child support, and custody-related financial issues.

Divorce Settlement Tips

Before agreeing to a divorce settlement, gather bank statements, tax returns, mortgage documents, retirement account statements, insurance policies, and debt records. Full financial disclosure is important.

Final Thoughts

Divorce is not only about ending a marriage. It is also about protecting your future. A divorce attorney can help you make informed decisions and avoid costly mistakes.

Home Equity Loan vs. HELOC: Which Option Is Better?

Homeowners who have built equity may be able to borrow against their home through a home equity loan or a home equity line of credit, commonly called a HELOC. Both options use the home as collateral, but they work differently.

rnrn

A home equity loan provides a lump sum of money that is repaid over a set term with regular monthly payments. Many home equity loans have fixed interest rates, which makes payments predictable. This can be useful for one-time expenses such as a major home improvement project, debt consolidation, or a large planned purchase.

rnrn

A HELOC works more like a credit card. The lender gives you access to a line of credit, and you can borrow as needed during the draw period. HELOCs often have variable interest rates, meaning the payment can rise or fall over time. This flexibility can be useful for ongoing projects or uncertain expenses.

rnrn

The main advantage of a home equity loan is stability. You know how much you borrowed, what your payment is, and when the loan will be paid off. The main disadvantage is that you receive the full amount upfront, even if you do not need all of it immediately.

rnrn

The main advantage of a HELOC is flexibility. You can borrow only what you need, when you need it. The main risk is that variable rates can make payments unpredictable. Some borrowers may also be tempted to keep borrowing, which can increase debt.

rnrn

Before choosing either option, consider the risk. Because the loan is secured by your home, failure to repay could put your home at risk. Borrowing against home equity should be done carefully and for a clear financial purpose.

rnrn

Compare interest rates, fees, repayment terms, draw periods, closing costs, and whether the rate is fixed or variable. Also ask whether there are annual fees, early closure fees, or minimum withdrawal requirements.

rnrn

Home equity borrowing may make sense for improvements that increase property value or for consolidating high-interest debt with a clear repayment plan. It may not be wise for unnecessary spending or short-term lifestyle purchases.

rnrn

The best option depends on your goals. Choose a home equity loan if you need a fixed amount and predictable payment. Choose a HELOC if you need flexible access to funds over time.

rnrn

Before borrowing, compare lenders and review the full cost carefully.

rn