Monday, September 21

Ketina Onzi You are A Bully Na Swiden Ukatengera Munhu Chikafu Doesn't mean Akutoita Zvaunoda Iwewe Ngochani Yecholocho Not Happy Hanzi Ketty Unotenga Hushamwari

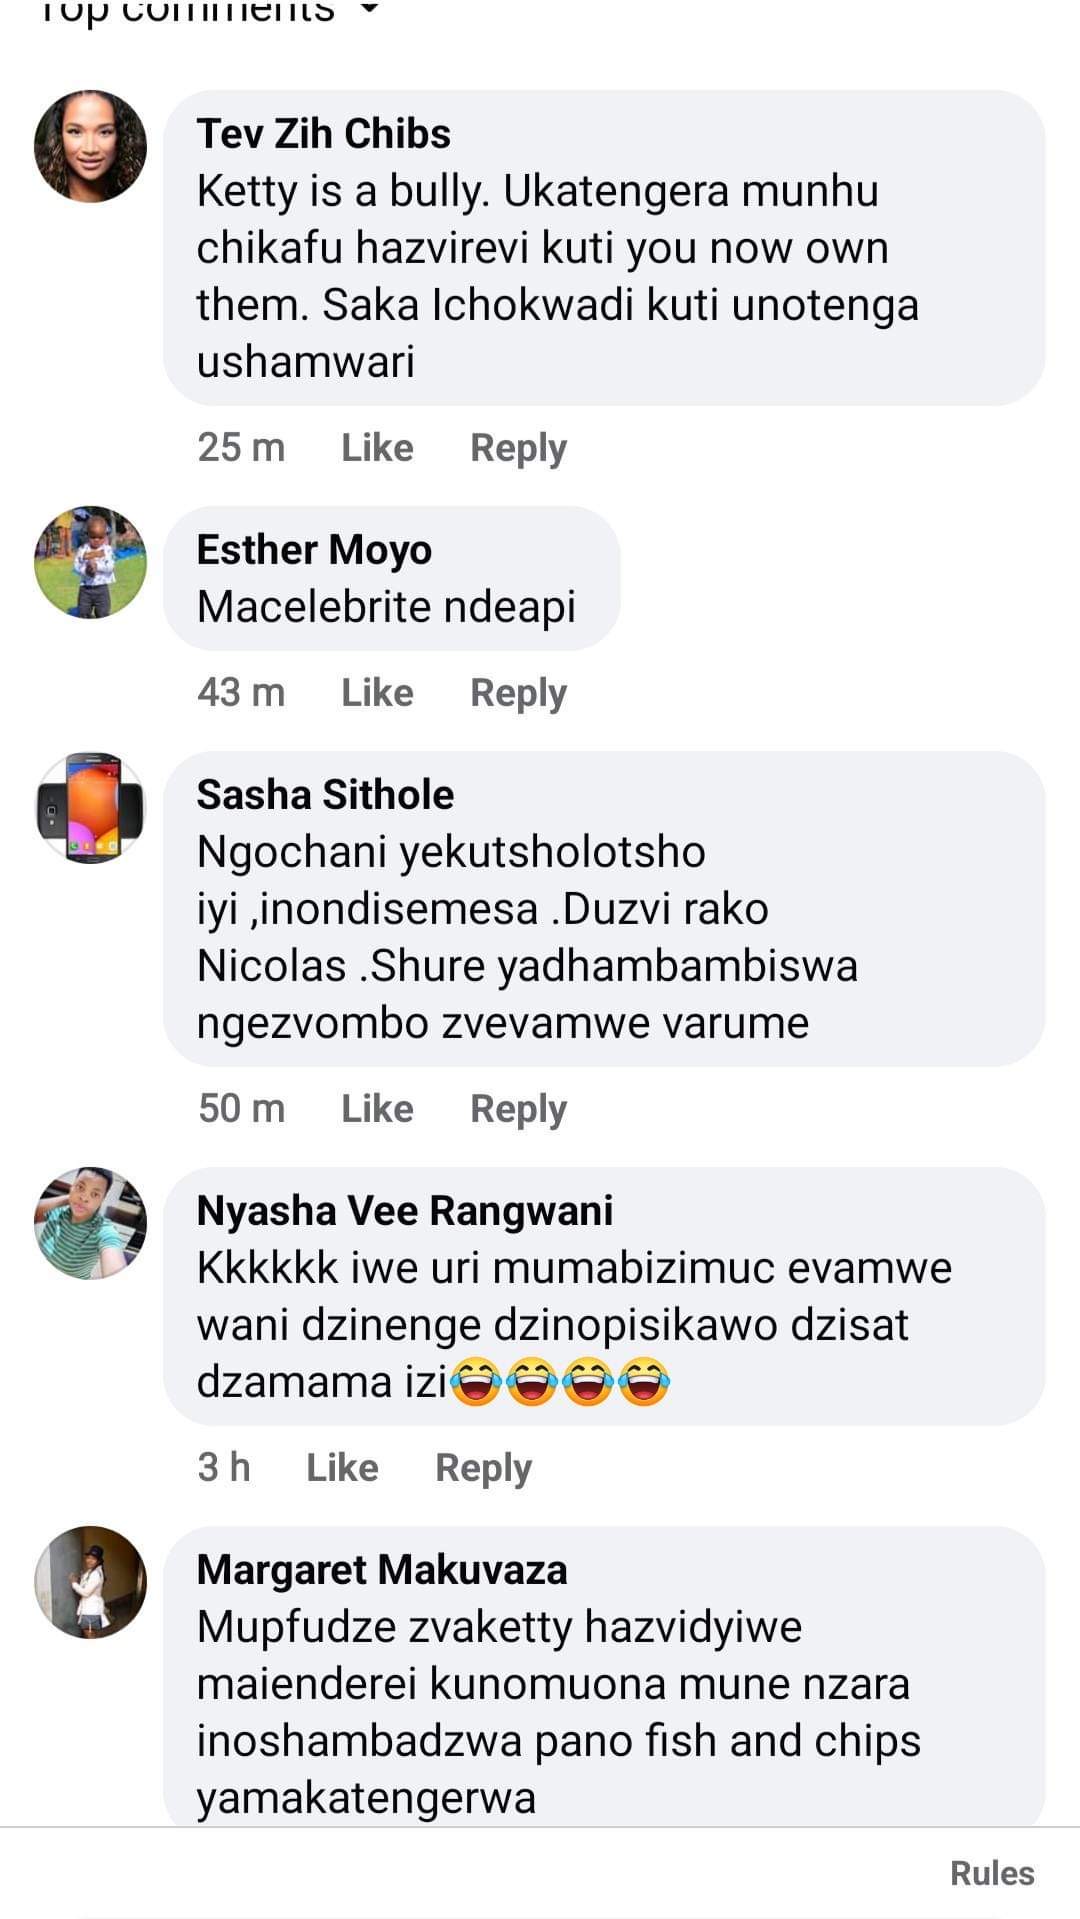
Ketty is a bully. Ukatengera munhu chikafu hazvirevi kuti you now own them. Saka Ichokwadi kuti unotenga ushamwariMupfudze zvaketty hazvidyiwe maienderei kunomuona mune nzara inoshambadzwa pano fish and chips yamakatengerwaNgochani yekutsholotsho iyi ,inondisemesa .Duzvi rako Nicolas .Shure yadhambambiswa ngezvombo zvevamwe varume

  • Share:

Info News

Remote Jobs That Pay Well: How to Build a High-Income Career from Home

Remote work has moved from being a niche option to a mainstream career path. Today, thousands of companies are hiring globally, making it possible to earn a strong income without ever stepping into an office. If you’re searching for remote jobs that pay well, the opportunities are broader than ever—but knowing where to look and what skills to build is key.

rnrn

For many people, remote work isn’t just about convenience. It’s about flexibility, independence, and access to better-paying opportunities that may not exist locally. Whether you’re in the U.S., Nigeria, Zimbabwe, or anywhere else, remote work opens the door to earning in stronger currencies and working with global clients.

rnrn

Why Remote Work Is Growing So Fast

rnrn

Companies have realized that remote teams can be just as productive—if not more—than traditional office setups. This shift has led to increased hiring across industries such as tech, marketing, customer service, and finance.

rnrn

For workers, the benefits are clear. There’s no commute, more control over your schedule, and the ability to work from anywhere. This combination has made remote work one of the most desirable career paths today.

rnrn

High-Paying Remote Jobs to Consider

rnrn

Not all remote jobs pay the same. Some roles offer significantly higher income potential, especially if you have in-demand skills.

rnrn

1. Software Development

rnrn

Developers are among the highest-paid remote workers. Skills in web development, mobile apps, and cloud systems are in high demand.

rnrn

2. Digital Marketing

rnrn

Roles such as SEO specialists, content marketers, and social media managers are widely available and can pay well with experience.

rnrn

3. Freelance Writing and Content Creation

rnrn

Businesses constantly need content, making writing a flexible and scalable income option.

rnrn

4. Customer Support (Specialized)

rnrn

While entry-level roles may pay less, specialized support roles (tech, SaaS, finance) offer higher salaries.

rnrn

5. Data Analysis and AI Roles

rnrn

Companies rely on data to make decisions, creating strong demand for analysts and AI specialists.

rnrn

How to Get Started with Remote Work

rnrn

Getting your first remote job can feel challenging, but it becomes easier with the right approach.

rnrn

Start by identifying your skills. Even if you don’t have technical expertise, there are many entry-level roles available. Next, create a strong online presence—this includes a professional resume, LinkedIn profile, and portfolio if applicable.

rnrn

Job platforms and freelance websites are great places to begin. Focus on building experience, even if it means starting with smaller projects.

rnrn

Skills That Increase Your Earning Potential

rnrn

To move into higher-paying roles, you need to develop valuable skills. These include:

rnrn

Communication and collaboration
rnTime management
rnTechnical skills (depending on your field)
rnProblem-solving

rnrn

Continuous learning is essential. The more skills you acquire, the more opportunities you can access.

rnrn

Common Mistakes to Avoid

rnrn

One common mistake is applying to too many jobs without tailoring your application. Quality matters more than quantity.

rnrn

Another mistake is undervaluing your skills. Many beginners accept very low pay, which can make it harder to increase rates later.

rnrn

Consistency is also key. Remote work often requires persistence before results appear.

rnrn

Final Thoughts

rnrn

Remote jobs that pay well are not just a trend—they are the future of work. With the right skills, mindset, and strategy, you can build a stable and rewarding career from anywhere in the world.

rnrn

Authority Insight Section (SEO Boost)

rnrn

Career experts recommend building skills through online certifications, professional training platforms, and global freelance marketplaces to increase earning potential in remote work.

rn

SEO Meta Title Debt Consolidation Loans: Pros, Cons, and Comparison Tips

Debt consolidation can sound like an easy solution: combine several debts into one payment and possibly lower the interest rate. For some borrowers, that can be helpful. For others, it only moves debt around while the balance continues to grow. The difference depends on the loan terms, fees, spending habits, income stability, and payoff discipline.

A debt consolidation loan is usually a personal loan used to pay off credit cards, medical bills, store cards, payday loans, or other unsecured debts. After the old balances are paid, the borrower makes one fixed monthly payment to the new lender. The main appeal is simplicity. One due date, one payment, and one payoff timeline can make budgeting easier.

The biggest potential benefit is a lower interest rate. Credit cards often charge variable rates that can rise over time. A fixed-rate personal loan may offer a predictable payment and a defined end date. If the new loan has a lower rate and you avoid new debt, consolidation can reduce interest costs and speed up payoff.

However, the monthly payment is not the only number to review. A longer repayment term can lower the monthly payment while increasing total interest paid. For example, stretching debt over several years may feel easier each month but cost more overall. Always compare total repayment, not just the payment amount.

Fees matter too. Some lenders charge origination fees, late fees, returned payment fees, or prepayment penalties. An origination fee may be deducted from the loan amount, which means you receive less money than expected. Compare the annual percentage rate because it includes certain finance charges and gives a better apples-to-apples view than the interest rate alone.

Credit score impact can go in different directions. Applying for a loan may create a hard inquiry. Opening a new account can reduce the average age of credit. However, paying down credit card balances may improve credit utilization, which can help some borrowers over time. The biggest factor remains making on-time payments.

The main risk is running up the old credit cards again. If you consolidate balances and continue using cards without a budget, you may end up with the consolidation loan plus new credit card debt. Before taking a loan, create a spending plan and decide whether to close cards, lower limits, or keep cards open but unused.

Not everyone qualifies for a low rate. Lenders may review credit score, income, debt-to-income ratio, employment history, payment history, and existing balances. Borrowers with stronger credit often receive better terms. If the offers are high-interest, consolidation may not save money.

Alternatives include a balance transfer credit card, nonprofit credit counseling, a debt management plan, negotiating with creditors, budgeting changes, side income, or a structured debt snowball or debt avalanche method. Balance transfers may offer promotional rates, but fees and deadlines matter. Missing the promotional payoff date can lead to higher interest.

Before choosing any offer, write down every debt: creditor, balance, interest rate, minimum payment, due date, and payoff priority. Then compare three scenarios: keeping current payments, using a consolidation loan, and using another strategy. A simple spreadsheet can reveal whether consolidation truly saves money.

Ask lenders these questions: Is the rate fixed or variable? What is the APR? Are there origination fees? Is there a prepayment penalty? What is the total repayment amount? When are funds sent? Can the lender pay creditors directly? What happens if I miss a payment? Are there hardship options?

Debt consolidation works best when it is part of a larger debt payoff plan. The loan should create a clear path out of debt, not a temporary break from the pressure. If the payment fits the budget, the rate is lower, and the borrower stops adding new balances, consolidation can be a useful tool. If not, it may delay the real problem.