Friday, October 16

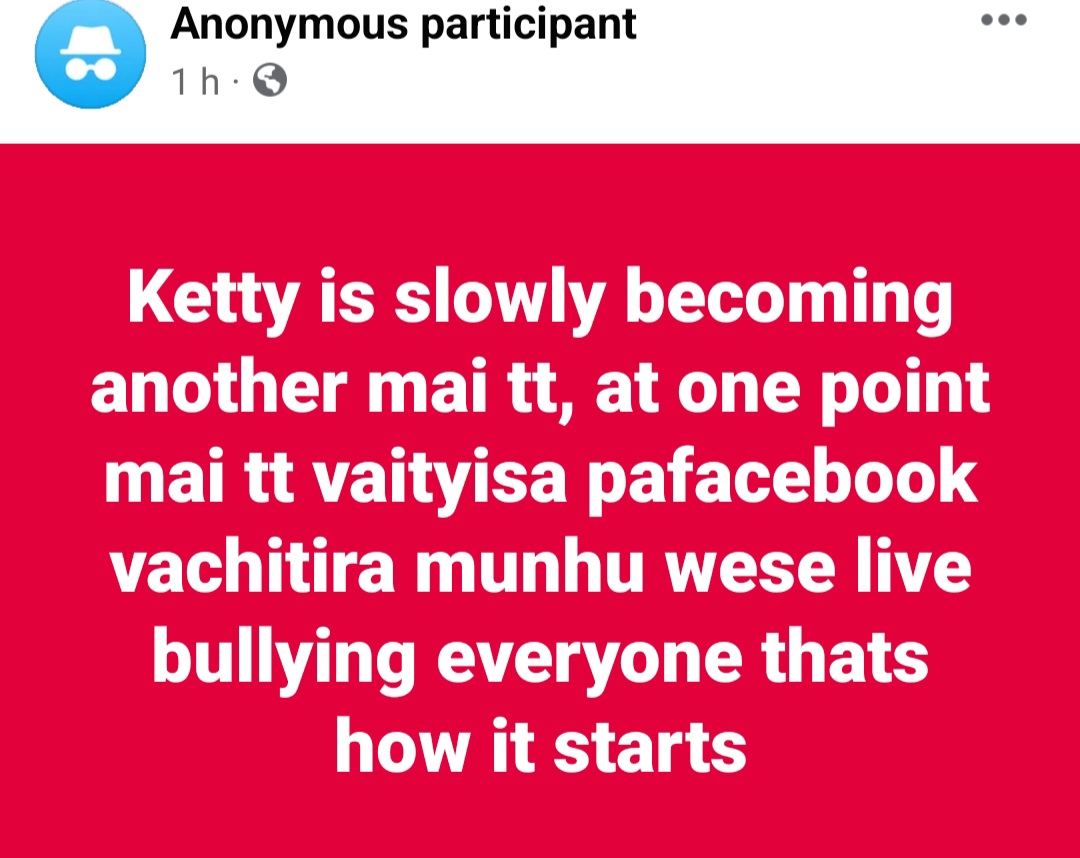
Ketina Is Now Becoming Another Maitt Bullying Kuda Kutyisa Social Media Yese

Ketty is slowly becoming another mai tt, at one point mai tt vaityisa pafacebook vachitira munhu wese live bullying everyone thats how it startsShe did not start it now but kudara echituka munhu worse who was against mbavha yenyika

  • Share:

Info News

Digital Banking and Financial Technology Are Changing Global Finance

Digital banking and financial technology platforms are transforming the way consumers manage money and conduct transactions. Mobile banking apps, online payment systems, cryptocurrency platforms, and digital lending services are making financial services more accessible and convenient worldwide.

rnrn

Consumers can now transfer money, apply for loans, invest, and pay bills directly from smartphones. Financial technology companies are helping small businesses accept online payments and reach international customers more easily. Mobile banking has become especially important in developing countries where traditional banking infrastructure may be limited.

rnrn

Security and convenience remain major priorities for digital finance providers. Financial institutions are investing heavily in fraud detection systems, encryption technology, and biometric security features to protect customer information and transactions.

rnrn

Experts predict financial technology innovation will continue expanding globally as consumers demand faster, safer, and more convenient financial services. Digital finance is expected to play a major role in future economic growth and financial inclusion initiatives worldwide.

rn

Home Equity Loan vs. HELOC: Which Option Is Better?

Homeowners who have built equity may be able to borrow against their home through a home equity loan or a home equity line of credit, commonly called a HELOC. Both options use the home as collateral, but they work differently.

rnrn

A home equity loan provides a lump sum of money that is repaid over a set term with regular monthly payments. Many home equity loans have fixed interest rates, which makes payments predictable. This can be useful for one-time expenses such as a major home improvement project, debt consolidation, or a large planned purchase.

rnrn

A HELOC works more like a credit card. The lender gives you access to a line of credit, and you can borrow as needed during the draw period. HELOCs often have variable interest rates, meaning the payment can rise or fall over time. This flexibility can be useful for ongoing projects or uncertain expenses.

rnrn

The main advantage of a home equity loan is stability. You know how much you borrowed, what your payment is, and when the loan will be paid off. The main disadvantage is that you receive the full amount upfront, even if you do not need all of it immediately.

rnrn

The main advantage of a HELOC is flexibility. You can borrow only what you need, when you need it. The main risk is that variable rates can make payments unpredictable. Some borrowers may also be tempted to keep borrowing, which can increase debt.

rnrn

Before choosing either option, consider the risk. Because the loan is secured by your home, failure to repay could put your home at risk. Borrowing against home equity should be done carefully and for a clear financial purpose.

rnrn

Compare interest rates, fees, repayment terms, draw periods, closing costs, and whether the rate is fixed or variable. Also ask whether there are annual fees, early closure fees, or minimum withdrawal requirements.

rnrn

Home equity borrowing may make sense for improvements that increase property value or for consolidating high-interest debt with a clear repayment plan. It may not be wise for unnecessary spending or short-term lifestyle purchases.

rnrn

The best option depends on your goals. Choose a home equity loan if you need a fixed amount and predictable payment. Choose a HELOC if you need flexible access to funds over time.

rnrn

Before borrowing, compare lenders and review the full cost carefully.

rn