Tuesday, October 06

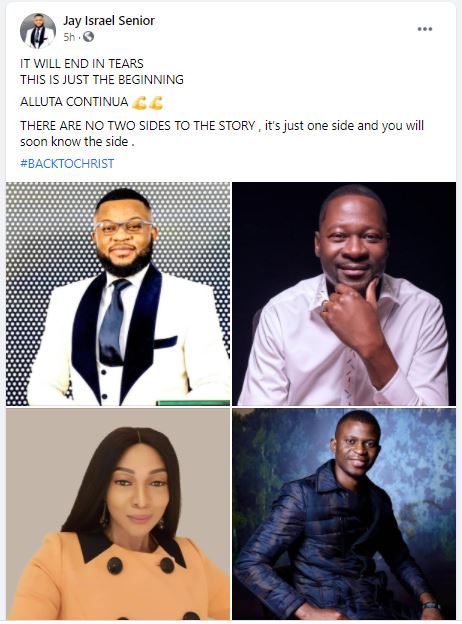
Jay Israel Declares It Will End In Tears For Makandiwa & Chari

Jay Isreal, the Pastor who conspired with Blessing Muzvongi, a long time Makandiwa tormentor has finally spoken. He has said he will talk in 2021 as he wants to focus on celebrating his 28th birthday.

On the issue of the video, Jay says there are no two sides of the coin and it will end in tears.

Related Story

In the latest episode of the ‘Battle of Churches’, Prophet Emmanuel’s stable seems to have drawn the last punch on the on-going skirmish the two ‘men of God’ found themselves in.

The two Zimbabwean church leaders found themselves embroiled in the ‘spiritual’ warfare that has seen them going back and forth, throwing jabs over each other’s “spiritual flaws”.

Emmanuel Makandiwa’s church has responded to Pastor Jay Israel’s claims that the UFCI leader had a second wife and was extorting his church members.

This after the self-confessed fake prophet, Jay Israel came forward to the South African CRL Rights Commission with an explosive testimony on how he and many other pastors and prophets ran churches as businesses by manipulating people and extorting money from them.

Events leading to the recent drama are such that Jacob Dube, who is popularly known by his church members as Pastor Jay Israel was ratted by his former Public Relations Advisor Thabisa Ralawe to the police and human rights commission for fraud and manipulating his congregants into sponsoring his lavish lifestyle.

It seems the self-styled fake prophet did not want to go down alone, but with a myriad of his fellow businessmen cum prophets.

Working in cahoots with Emmanuel Makandiwa’s ‘tormentor’, Blessing Mashangwa, Jay Israel announced on his Facebook page that he wanted to expose Makandiwa’s fakeness and his shenanigans.

Blessing Mashangwa made headlines a few years back when together with her (then) husband Hupenyu Mashangwa after they sued Prophet Emmanuel Makandiwa over alleged false prophecies.

They then demanded a massive $6.5 million from the United Family International Church, but unfortunately, they walked away with nothing as fraud allegations against the Makandiwas were dismissed last year after the High Court said the claims were false, frivolous and vexatious.

Her name has once again popped up, this time claiming that she was once in an intimate relationship with Emmanuel Makandiwa and was a second wife before their nasty fight.

And that was what Jay Israel sought to expose, a week ago in his Facebook live.

But Makandiwa’s stable claims he failed to do so because of threats they made to the self-styled fake prophet and his lady friend, Blessing Mashangwa.

In an hour-long Facebook live, Makandiwa’s stable – through Evidence Chari claim they illegally sourced evidence that Jay Israel and Blessing were working together to come up with a lie they intended to expose on Facebook.

The said evidence contains an audio and video recordings of the two, J Israel and Blessing in a lounge, planning on how they wanted to expose Makandiwa.

  • Share:

Info News

Product Liability Class Action Lawsuit: Defective Product Claims

product liability class action, defective product lawsuit, product defect lawyer, dangerous product class action, consumer product lawsuit, recall lawsuit attorney

rnrn

Product Liability Class Action Lawsuit: Defective Product Claims

rnrn

When a product fails, one customer may ask for a refund. But when the same defect affects thousands of customers, a product liability class action lawsuit may follow.

rnrn

These cases may involve vehicles, appliances, electronics, medical devices, household products, baby products, food, cosmetics, tools, or other consumer goods.

rnrn

A product liability class action can help consumers seek compensation, repairs, replacements, refunds, or safety changes.

rnrn

What Is a Product Liability Class Action?

rnrn

A product liability class action is a lawsuit involving a product that allegedly has a common defect affecting many people.

rnrn

The defect may involve:

rnrn

Design flaw
rnManufacturing defect
rnFailure to warn
rnFalse advertising
rnPremature failure
rnSafety hazard
rnWarranty violation
rnHidden defect

rnrn

The key issue is whether the defect is common across the class.

rnrn

Common Product Defect Examples

rnrn

Product class actions may involve:

rnrn

Cars with defective parts
rnAppliances that fail early
rnElectronics with battery problems
rnContaminated products
rnFaulty medical devices
rnUnsafe children’s products
rnDefective home equipment
rnMisleading product claims
rnWarranty coverage disputes

rnrn

Not every recall creates a lawsuit, and not every lawsuit involves a recall.

rnrn

What Evidence Should Consumers Keep?

rnrn

If you believe a product is defective, save:

rnrn

Proof of purchase
rnReceipts
rnWarranty documents
rnPhotos
rnVideos
rnRepair records
rnCustomer service emails
rnProduct packaging
rnSerial numbers
rnModel numbers
rnRecall notices
rnMedical bills if injured
rnReplacement costs

rnrn

Evidence can help show when you bought the product, what happened, and what damages you experienced.

rnrn

What Can a Product Class Action Settlement Provide?

rnrn

Depending on the case, settlement benefits may include:

rnrn

Cash refunds
rnRepairs
rnReplacement products
rnExtended warranties
rnReimbursement for repairs
rnSafety inspections
rnRecall support
rnProduct credits
rnWarning label changes

rnrn

The settlement terms depend on the case.

rnrn

Defective Product Injury Claims

rnrn

Some product cases involve only economic loss, such as paying for a product that failed early.

rnrn

Others involve physical injury. Injury claims may be more individualized and may require separate legal review.

rnrn

If you were seriously injured by a product, speak with a product liability attorney before signing a class action release.

rnrn

Warranty Claims

rnrn

Many product class actions involve warranties.

rnrn

A company may be accused of:

rnrn

Refusing warranty coverage
rnConcealing known defects
rnSelling products with short useful life
rnMisrepresenting durability
rnCharging for repairs that should be covered

rnrn

Warranty law can vary by state.

rnrn

Product Recalls and Lawsuits

rnrn

A recall can be important evidence, but it does not automatically mean every consumer has the same legal claim.

rnrn

If a product is recalled, follow official safety instructions. Keep all recall documents.

rnrn

Questions to Ask a Lawyer

rnrn

Ask:

rnrn

Is the defect common?
rnAre other consumers affected?
rnIs there a recall?
rnWhat law applies?
rnDo I need repair records?
rnShould I keep the product?
rnCould I have an individual injury claim?
rnWhat rights would I give up in a settlement?

rnrn

Final Thoughts

rnrn

A product liability class action lawsuit may help consumers recover money or force companies to fix widespread defects.

rnrn

If a product failed, caused damage, or did not perform as advertised, keep records and check whether others experienced the same issue.

rnrn

A pattern of harm is what can turn a product complaint into a class action case.

rn

SEO Meta Title Credit Repair vs Credit Counseling: Compare Your Options

When credit problems become stressful, two options often appear in search results: credit repair and credit counseling. They sound similar, but they are not the same service. Credit repair focuses on disputing inaccurate, incomplete, or unverifiable information on credit reports. Credit counseling focuses on budgeting, debt repayment, and financial education. Knowing the difference can help you avoid scams and choose the right help.

Credit repair companies often advertise help with removing negative items from credit reports. Legitimate credit repair is based on your legal right to dispute inaccurate information. If a late payment, collection, account balance, personal detail, or account status is wrong, you can dispute it with the credit bureaus and the company that furnished the information.

However, accurate negative information usually cannot be removed simply because it hurts your score. Late payments, collections, bankruptcies, and charge-offs may remain on credit reports for legally allowed periods if they are accurate. Be cautious with any company that promises a specific score increase, guaranteed removals, or a new credit identity.

Credit counseling is different. A nonprofit credit counseling agency can review income, expenses, debts, and goals. Counselors may help build a budget, explain credit reports, suggest repayment strategies, and discuss whether a debt management plan makes sense. A debt management plan may consolidate payments through the counseling agency and sometimes reduce interest rates or fees with participating creditors.

Credit counseling can be useful when the main problem is debt affordability. If you are making minimum payments, falling behind, or using one card to pay another, a counselor can help create a structured plan. Credit repair alone will not solve unaffordable debt.

Credit repair can be useful when the main problem is inaccurate reporting. For example, an account that does not belong to you, a debt listed twice, an incorrect late payment, a paid account still shown as unpaid, or outdated information may be disputable. You can file disputes yourself for free, but some people hire help because they do not want to manage the paperwork.

Before paying for credit repair, understand your rights. In the United States, credit repair companies must follow federal rules, including restrictions on misleading claims and upfront fees. You should receive a written contract, cancellation rights, and clear information about what the company will do. If a company pressures you, asks you to lie, tells you to dispute everything, or suggests using a different Social Security number, walk away.

A strong credit rebuilding plan often includes both cleanup and behavior changes. Start by pulling credit reports from the major bureaus. Review personal information, open accounts, closed accounts, collections, public records, inquiries, balances, and payment history. Highlight anything inaccurate and gather supporting documents.

Next, pay every current bill on time. Payment history is a major scoring factor. Set up reminders or autopay for minimum payments. Then focus on credit utilization, which is the percentage of available revolving credit being used. Lower balances can help improve scores over time.

Avoid opening too many new accounts at once. New inquiries and new accounts can lower scores temporarily. Instead, build a steady pattern: pay on time, reduce balances, keep older accounts in good standing, and monitor reports for errors.

If you have no active credit, a secured credit card or credit-builder loan may help, but fees and terms matter. Choose products from reputable banks or credit unions and avoid high-fee cards that drain your budget.

The right choice depends on the root problem. Choose credit repair if the issue is inaccurate reporting. Choose credit counseling if the issue is debt management, budgeting, or missed payments. Use both if you have errors and unaffordable debt. Most importantly, avoid anyone promising instant results. Real credit improvement takes accurate reporting, consistent payments, lower debt, and time.