Sunday, October 18

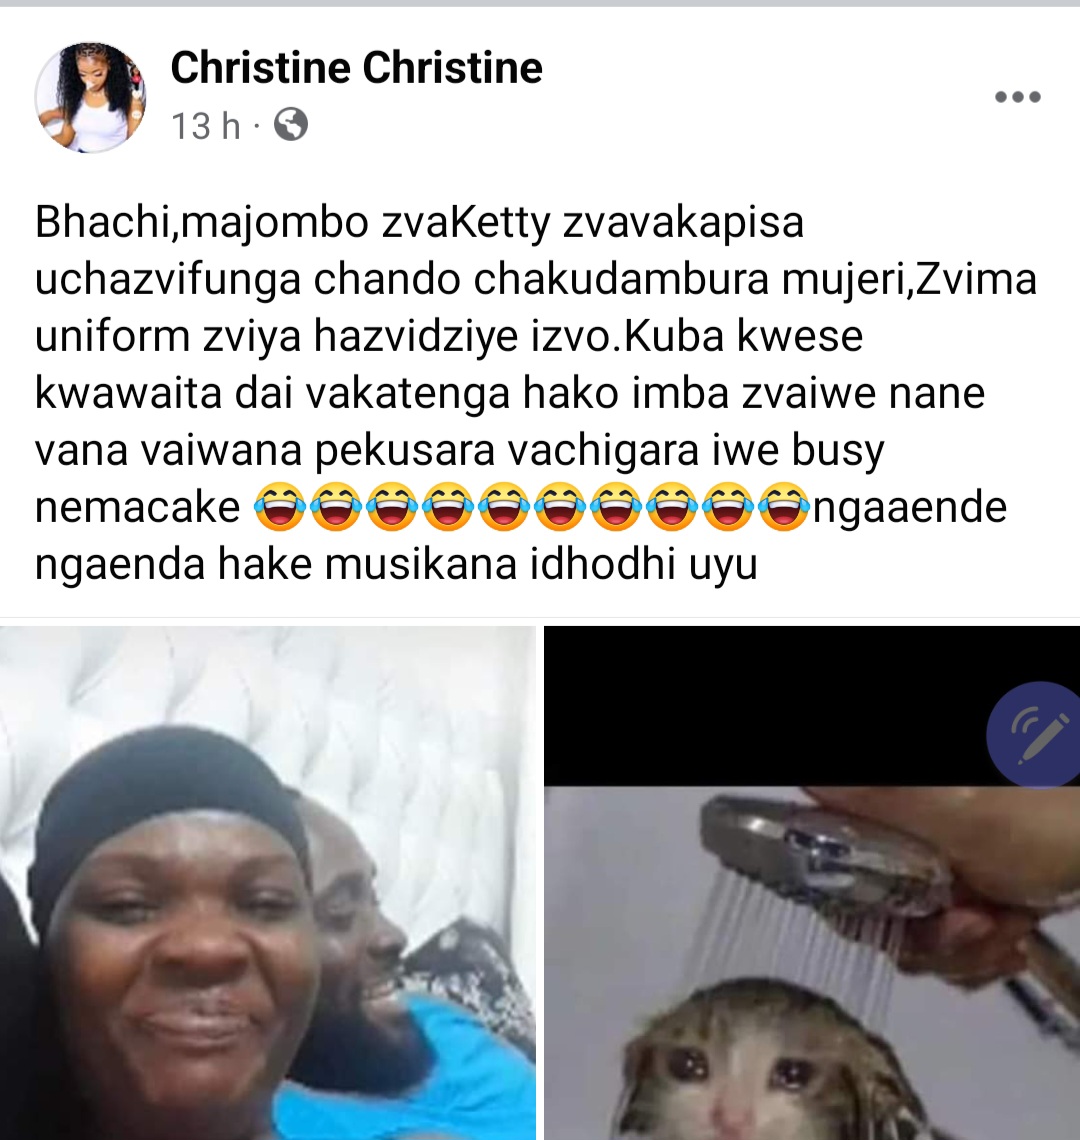
Felistas Bhachi Nemajombo ZvaKetty Zvawakapisa Uchazvifunga Chando Chakudambura Muchikurubhi

Bhachi,majombo zvaKetty zvavakapisa uchazvifunga chando chakudambura mujeri,Zvima uniform zviya hazvidziye izvo.Kuba kwese kwawaita dai vakatenga hako imba zvaiwe nane vana vaiwana pekusara vachigara iwe busy nemacake 😂😂😂😂😂😂😂😂😂😂ngaaende ngaenda hake musikana idhodhi uyu

  • Share:

Info News

Mortgage Refinance Guide: Costs, Rates, and Break-Even Math


A lower mortgage rate sounds attractive, but refinancing is not always a guaranteed win. A refinance replaces your current mortgage with a new loan, and that new loan usually comes with closing costs, a new term, new paperwork, and sometimes a reset payoff timeline. The right question is not simply, Can I get a lower rate? The better question is, Will this refinance improve my finances after all costs are included?

The most common reason to refinance is to lower the interest rate. A lower rate can reduce the monthly payment and total interest over time. However, closing costs can include lender fees, appraisal fees, title fees, recording fees, credit report fees, prepaid taxes, prepaid insurance, and points. Some lenders advertise no-closing-cost refinancing, but the costs may be rolled into the loan balance or covered through a higher rate.

The break-even point is one of the most important calculations. Divide the total refinance cost by the monthly savings. If closing costs are $4,000 and the refinance saves $200 per month, the break-even point is 20 months. If you plan to stay in the home longer than that, the refinance may make sense. If you expect to sell or move before then, the savings may never catch up.

Loan term matters. Refinancing from a 30-year mortgage into a new 30-year mortgage can lower the payment but may extend debt far into the future. That can increase total interest even with a lower rate. Some homeowners choose a 15-year or 20-year refinance to pay off the home faster, but the payment may be higher. Others choose a new 30-year term for cash-flow relief. The best choice depends on monthly budget, retirement timeline, and long-term goals.

A cash-out refinance allows a homeowner to borrow more than the current mortgage balance and receive the difference in cash. People use cash-out refinancing for home improvements, debt consolidation, education, or emergency reserves. This can be useful when the numbers work, but it also increases the mortgage balance and puts the home at risk if payments become unaffordable.

Refinancing from an adjustable-rate mortgage to a fixed-rate mortgage can also be smart when payment stability matters. Adjustable rates may start lower but can change later based on the loan terms. A fixed rate can provide predictability, especially for homeowners who plan to stay long term.

Credit score, home equity, income, debt-to-income ratio, property type, and appraisal value can all affect refinance options. A stronger credit profile and more equity may qualify for better rates. If the home value has increased, refinancing may also help remove private mortgage insurance if requirements are met.

Points deserve careful review. Discount points are upfront fees paid to reduce the interest rate. Buying points can make sense if you plan to keep the loan long enough to recover the cost through lower payments. If you may move, sell, or refinance again soon, paying points may not be worthwhile.

Before applying, gather the current mortgage statement, homeowners insurance details, property tax information, income documents, credit information, and an estimate of home value. Ask lenders for loan estimates using the same loan type and term so comparisons are fair.

Questions to ask include: What is the APR? What are total closing costs? Are costs paid upfront or rolled into the loan? What is the new loan balance? What is the break-even point? Are there prepayment penalties? How long will underwriting take? Does the rate lock have a fee? What happens if the appraisal comes in low?

Refinancing can be a powerful financial move when it lowers total costs, improves stability, removes mortgage insurance, shortens the term, or supports a smart cash-flow plan. It can be a mistake when it only lowers the payment by extending debt or adding costs that never pay off. Run the numbers before signing.

Medical Malpractice Lawyer: When a Medical Mistake May Become a Legal Claim

medical malpractice lawyer, medical malpractice attorney, doctor negligence lawyer, hospital malpractice lawyer, surgical error lawyer, medical negligence claim

rnrn

Medical Malpractice Lawyer: When a Medical Mistake May Become a Legal Claim

rnrn

Medical care does not always lead to the result a patient hopes for. But a bad outcome is not automatically medical malpractice.

rnrn

Medical malpractice usually involves a health care provider failing to meet the accepted standard of care, causing injury or harm.

rnrn

These cases are complex, expensive, and heavily defended. That is why people often need a medical malpractice lawyer to evaluate whether a claim exists.

rnrn

What Is Medical Malpractice?

rnrn

Medical malpractice may happen when a doctor, nurse, hospital, surgeon, pharmacist, or other provider acts negligently and causes harm.

rnrn

Examples may include:

rnrn

Surgical errors
rnDelayed diagnosis
rnMisdiagnosis
rnMedication mistakes
rnBirth injuries
rnAnesthesia errors
rnFailure to monitor
rnFailure to order proper tests
rnEmergency room mistakes
rnHospital-acquired complications
rnFailure to obtain informed consent

rnrn

Not every mistake becomes a lawsuit. The mistake must usually cause legally recognized harm.

rnrn

What Must Be Proven?

rnrn

A medical malpractice claim often requires proof of:

rnrn

Provider-patient relationship
rnApplicable medical standard of care
rnBreach of that standard
rnCausation
rnDamages

rnrn

In many cases, expert medical testimony is required.

rnrn

Why Medical Malpractice Cases Are Hard

rnrn

Medical malpractice cases are difficult because:

rnrn

Medicine is complex
rnBad outcomes can happen without negligence
rnExpert witnesses may be needed
rnHospitals fight claims aggressively
rnMedical records are technical
rnState laws may require special procedures
rnDeadlines can be shorter than other injury claims

rnrn

Some states require certificates, affidavits, or expert reports before or soon after filing.

rnrn

Common Medical Malpractice Claims

rnrn

Misdiagnosis or Delayed Diagnosis

rnrn

A patient may claim the provider failed to diagnose a condition that another reasonably careful provider would have identified.

rnrn

Surgical Error

rnrn

This may involve wrong-site surgery, retained objects, nerve injury, or avoidable complications.

rnrn

Medication Error

rnrn

Medication mistakes may involve wrong drug, wrong dose, dangerous interactions, or failure to review allergies.

rnrn

Birth Injury

rnrn

Birth injury cases may involve harm to the baby or mother during pregnancy, labor, delivery, or post-delivery care.

rnrn

Failure to Monitor

rnrn

Hospitals and providers may be responsible if they fail to monitor a patient after surgery, medication, or emergency treatment.

rnrn

What Evidence Matters?

rnrn

Evidence may include:

rnrn

Medical records
rnTest results
rnImaging
rnPrescription records
rnHospital notes
rnDischarge instructions
rnSecond opinions
rnExpert reviews
rnTimeline of symptoms
rnBills
rnLost wage records
rnPhotos
rnCommunication with providers

rnrn

Medical records are critical. A lawyer can help obtain and review them.

rnrn

When Should You Contact a Medical Malpractice Lawyer?

rnrn

Consider legal help if:

rnrn

A provider’s error caused serious injury
rnA diagnosis was dangerously delayed
rnSurgery went wrong
rnMedication caused severe harm
rnA baby was injured during birth
rnA loved one died unexpectedly after medical care
rnA hospital refuses to answer questions
rnAnother doctor said something went wrong
rnYou suffered permanent harm

rnrn

Because deadlines may be strict, do not delay.

rnrn

What Compensation May Be Available?

rnrn

Depending on state law and the facts, damages may include:

rnrn

Medical bills
rnFuture medical care
rnLost wages
rnLoss of earning capacity
rnPain and suffering
rnDisability
rnHome care
rnRehabilitation
rnWrongful death damages

rnrn

Some states limit certain damages in medical malpractice cases.

rnrn

Final Thoughts

rnrn

A medical malpractice lawyer can help determine whether a bad medical outcome was caused by negligence.

rnrn

These cases require careful review, medical evidence, expert support, and legal strategy.

rnrn

If you believe a medical mistake caused s

rn