HARARE – A leaked confidential report from the Zimbabwe Reserve Bank’s Financial Intelligence Unit (FIU) has revealed that businessman Wicknell Chivhayo sought approval to withdraw up to US $20 million in cash every month through Ecobank, claiming the money was needed to pay Chinese suppliers for a government ICT contract.
The FIU memorandum, dated 13 December 2024, shows that Ecobank had approached the regulator to authorise the extraordinary withdrawals on behalf of three companies owned by Chivhayo.
According to the document seen by The Zimbabwe Mail, “the Financial Intelligence Unit (FIU) received applications from Ecobank for authority to make monthly cash withdrawals of USD 20 million … all owned by Mr. Wicknell Chivhayo.”
When asked to provide supply contracts to verify the source of funds, Chivhayo flatly refused, arguing that the agreements were confidential. Instead, he requested a private meeting so he could present the paperwork in person.
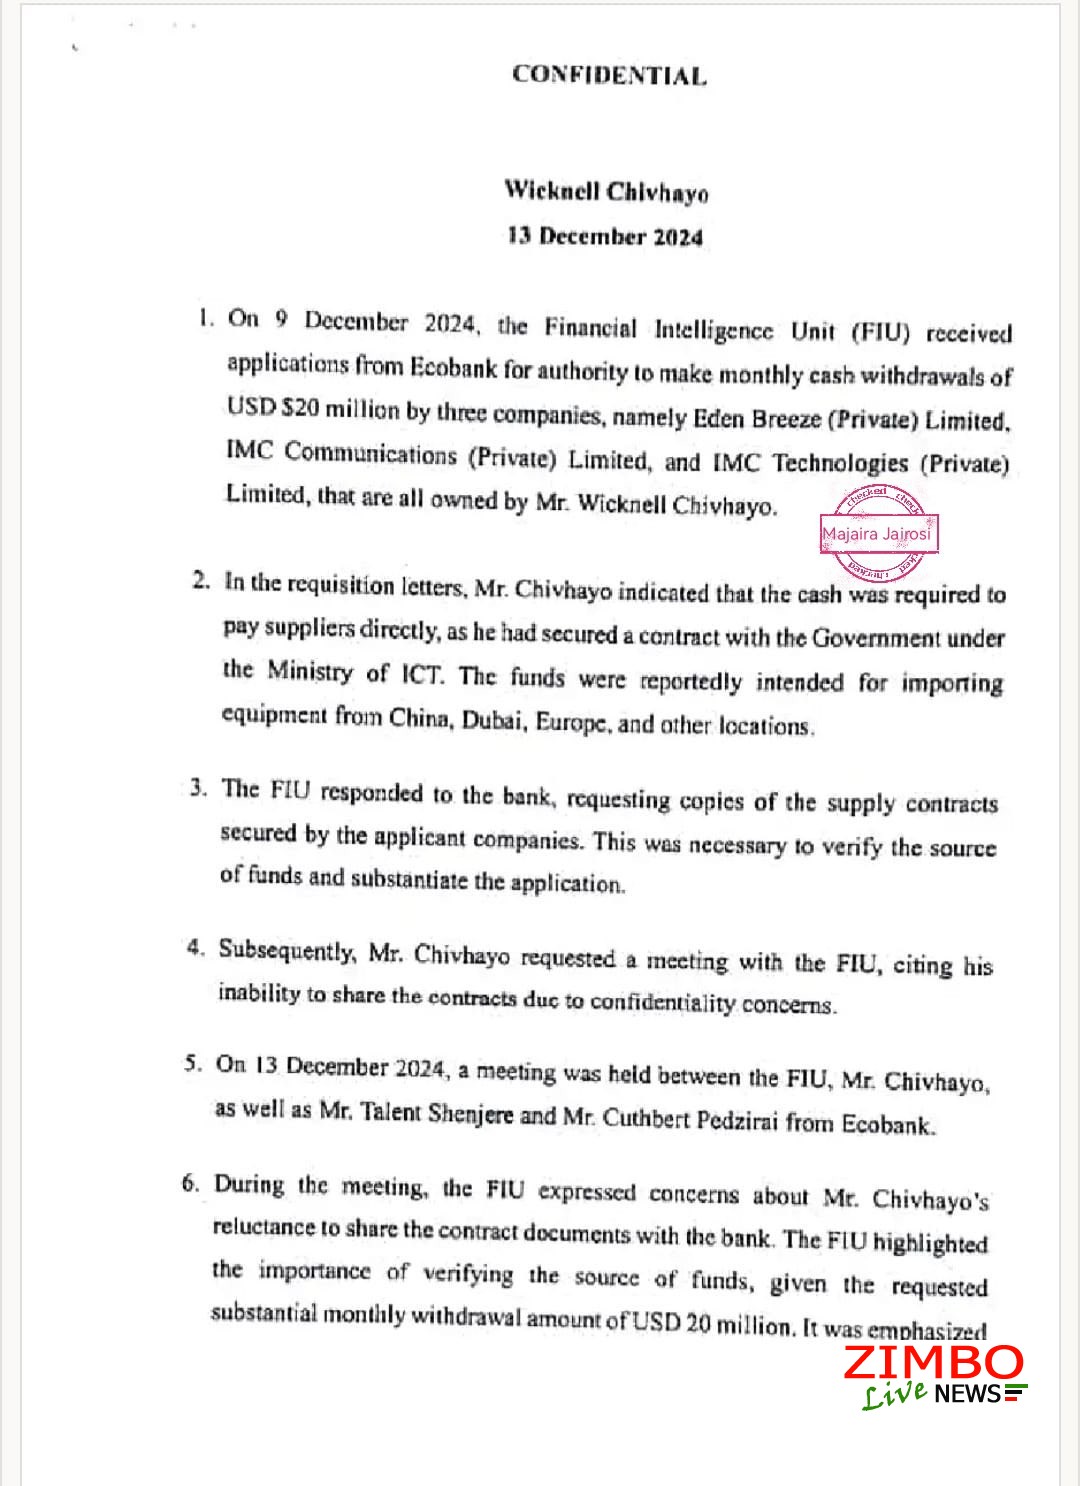
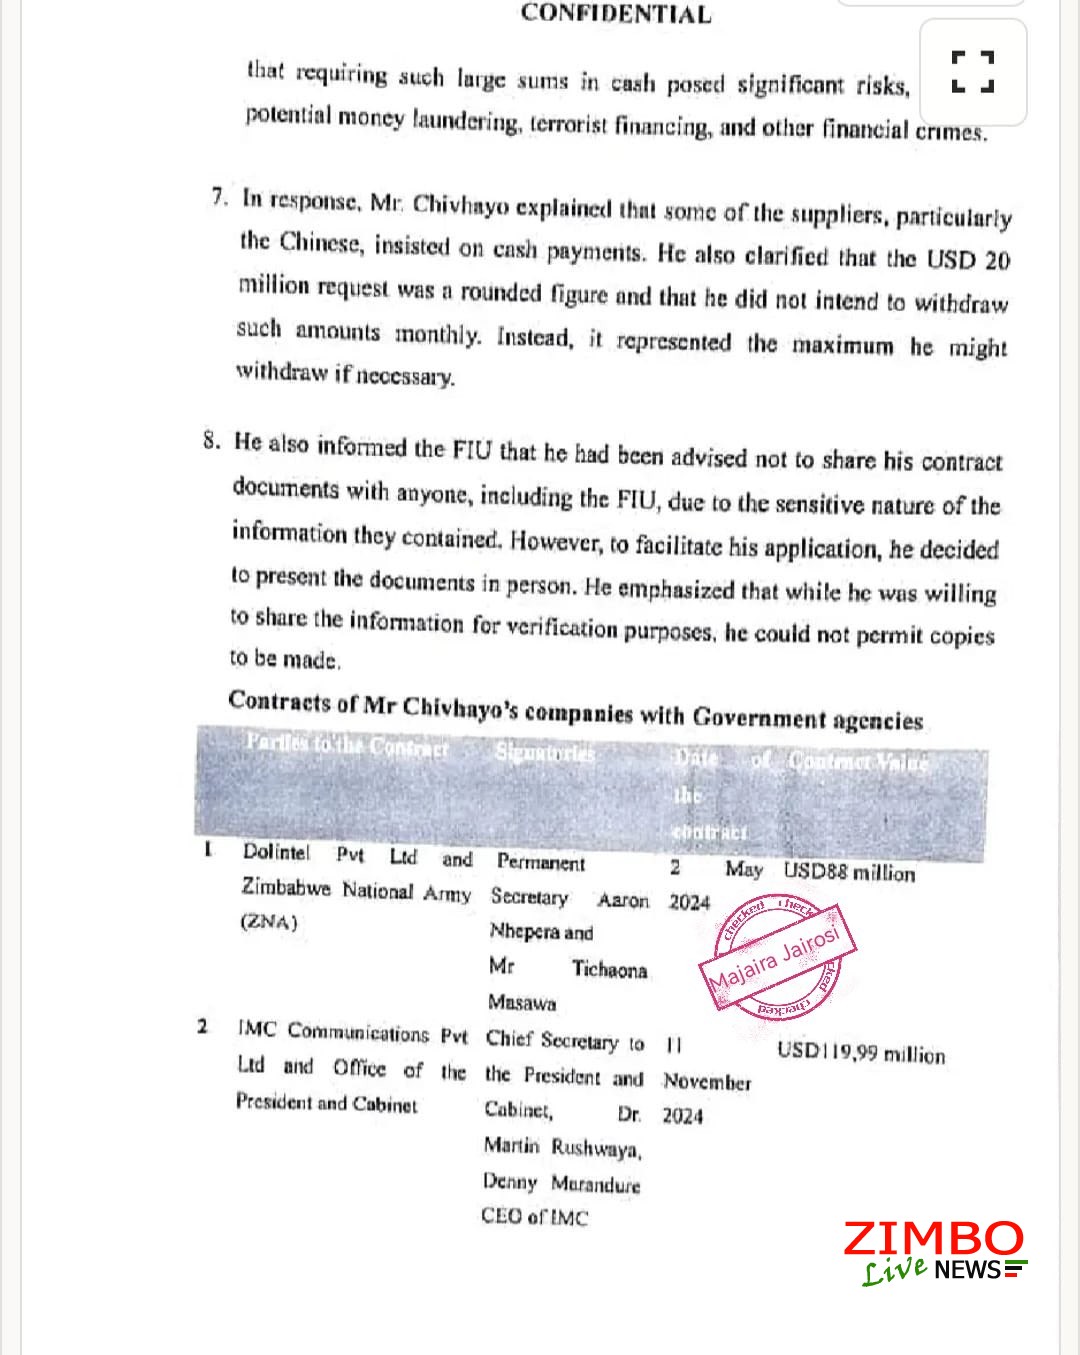
At a session held on 13 December with FIU officials and Ecobank representatives, he insisted that some Chinese suppliers demanded cash and that the US $20 million request merely represented the maximum he might ever need to withdraw rather than an amount he intended to take each month.
The document also records FIU concerns that such vast cash movements posed “significant risks of potential money laundering, terrorist financing, and other financial crimes.” Chivhayo maintained that he could not permit copies of the contracts to be made, though he was willing to allow regulators to view them during a face-to-face meeting.
For pro-democracy critics, the revelation underscores the opacity and privilege that characterise Zimbabwe’s political economy. The leaked memo points to multimillion-dollar state contracts linked to Chivhayo’s firms and highlights how politically connected businessmen continue to leverage government deals for personal gain.
Zimbabwe tourism packages
As one opposition-aligned economist put it, this episode offers “yet another reminder that public contracts are treated as private piggy banks for those close to power,” deepening public mistrust of a system already strained by corruption and economic hardship.
Info News
Best Business Credit Cards for Small Business Owners
The best business credit cards can help small business owners manage expenses, earn rewards, and separate business spending from personal spending. If you use your card carefully, it can also improve cash flow and make bookkeeping easier.
rnBusiness credit cards are especially useful for owners who travel, buy inventory, pay for ads, or make regular operating purchases. Instead of using a personal card, a business card keeps transactions organized and may come with better tools for tracking spending. That can save time at tax season and make financial reporting easier.
rnWhen choosing a card, look at rewards structure, annual fees, interest rates, and extra perks. Some cards offer cashback, while others reward travel, office spending, or advertising purchases. The best option depends on where your business spends the most.
rnYou should also review the card’s credit requirements. Some cards are easier to qualify for than others, and newer businesses may need to start with simpler options before moving up to premium cards. A business card should support your operations without creating unnecessary debt.
rnIf you plan to carry a balance, pay close attention to the APR. A rewards card is only valuable if the interest does not outweigh the benefits. For many owners, the smartest strategy is to pay the balance in full whenever possible and use the rewards as a bonus.
rnSome business cards also include tools for employee cards, expense tracking, purchase protection, and travel insurance. These extras may be useful if your team makes frequent purchases or if your business requires travel.
rnThe best business credit card is the one that matches your spending habits, keeps your finances organized, and gives you useful rewards without hidden costs.
rn
What Is a GLP-1 Weight Loss Program?
GLP-1 stands for glucagon-like peptide-1, a hormone that helps regulate appetite, blood sugar, and digestion. GLP-1 medications work by:
rnrn
rn - Reducing hunger
rn - Helping you feel full longer
rn - Slowing digestion
rn - Lowering cravings
rn - Supporting steady fat loss
rn
rnrn
Popular GLP-1 medications include:
rnrn
rn - Wegovy
rn - Ozempic
rn - Mounjaro
rn - Zepbound
rn - Semaglutide
rn - Tirzepatide
rn
rnrn
These medications became extremely popular because users reported dramatic weight loss results compared to traditional diet programs.
rnrn
Why Insurance Often Refuses to Pay
rnrn
Many people are shocked when they discover their insurance company will not cover GLP-1 medications for weight loss.
rnrn
Common reasons include:
rnrn
rn - Weight loss exclusions in insurance plans
rn - Prior authorization requirements
rn - High medication costs
rn - BMI restrictions
rn - Employer plan limitations
rn
rnrn
Without insurance, monthly costs can range from $900 to over $1,500 for brand-name medications.
rnrn
That’s why affordable telehealth GLP-1 programs have become one of the fastest-growing healthcare industries online.
rnrn
rn


