Tuesday, September 22

ZRP Seeks Information On Brutal Mine Assault Video Went Viral On Social Media

Following a video that went viral on social media, the Zimbabwe Republic Police (ZRP) has appealed for information that leads to the identification and arrest of the suspects who were involved in a brutal assault on an unidentified man beside a raging fire.

The incident appears to have taken place at a mining site. iHarare is unable to show the video on its family platform due to its graphic and violent nature.
As seen in the video, the unidentified man is assaulted with a heated iron rod  from a nearby fire in an effort to get him to reveal information concerning some property that was allegedly stolen in yet to be verified circumstances.

The ZRP took to their Twitter page and wrote:

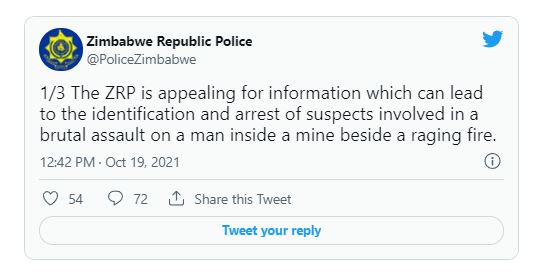
“The ZRP is appealing for information which can lead to the identification and arrest of suspects involved in a brutal assault on a man inside a mine beside a raging fire.

“As seen in the video which has gone viral on social media, the suspects go on to assault the man with an iron rod infused in fire while in the process asking him to reveal information on property alleged stolen in yet to be verified circumstances.

“Anyone with information to contact National Complaints Desk on (0242) 703631/WhatsApp on 0712800107 or Hre Operations on (0242) 748836 or Byo Operations on (0292) 273547

Below are some responses to the Tweet:
@Alfafa22385237 wrote:
The problem with @PoliceZimbabwe is very very big. Those people you are calling ,”involved in brutal assault” are serving officers. They are hired to do so___i don’t if this is what you call piece job or side hustle. Particularly those CIDs and CIOs they are abusing powers,hired.
@MrOppressed1 wrote:
Thanks for your quick reaction
@TafadzwaNkomo
Thank you for your reassuring efforts. Those barbarians should rot in jail
Recently, a private school teacher was nabbed when a video of him brutally assaulting a student emerged on social. He was arraigned before the courts where he was convicted and ordered to perform 630 hours of community service at Parirenyatwa Group of Hospitals.


Following a video that went viral on social media, the Zimbabwe Republic Police (ZRP) has appealed for information that leads to the identification and arrest of the suspects who were involved in a brutal assault on an unidentified man beside a raging fire.

The incident appears to have taken place at a mining site. iHarare is unable to show the video on its family platform due to its graphic and violent nature.
As seen in the video, the unidentified man is assaulted with a heated iron rod  from a nearby fire in an effort to get him to reveal information concerning some property that was allegedly stolen in yet to be verified circumstances.

The ZRP took to their Twitter page and wrote:

“The ZRP is appealing for information which can lead to the identification and arrest of suspects involved in a brutal assault on a man inside a mine beside a raging fire

  • Share:

Info News

High-Yield Savings Accounts: Where to Invest Safely and Grow Your Money

If you’re looking for a safe place to grow your money without taking big risks, a high-yield savings account is one of the smartest options available today. Unlike traditional savings accounts that offer very low interest, high-yield accounts provide better returns while still keeping your money easily accessible. For many people, they strike the perfect balance between security and growth.

rnrn

In today’s uncertain economy, more individuals are moving their money into high-interest savings accounts to protect their cash while earning passive income. Whether you’re building an emergency fund, saving for a home, or just trying to make your money work harder, understanding how these accounts work can help you make better financial decisions.

rnrn

What Is a High-Yield Savings Account?

rnrn

A high-yield savings account is a type of bank account that offers a higher interest rate compared to standard savings accounts. These accounts are typically offered by online banks, which can afford to pay better rates because they have lower operating costs than traditional brick-and-mortar banks.

rnrn

The interest you earn is usually expressed as APY (annual percentage yield), which shows how much your money can grow over time. Even a small difference in APY can significantly impact your savings in the long run.

rnrn

Why More People Are Choosing High-Yield Savings Accounts

rnrn

One of the biggest reasons people switch to high-yield savings accounts is simple: better returns without added risk. Unlike stocks or crypto investments, your money is not exposed to market volatility.

rnrn

Another major benefit is liquidity. You can access your money when you need it, making these accounts ideal for emergency funds or short-term savings goals.

rnrn

There’s also peace of mind. Most high-yield savings accounts in the U.S. are insured by the Federal Deposit Insurance Corporation (FDIC), which protects your deposits up to certain limits. This means your money remains safe even if the bank faces issues.

rnrn

How Much Can You Earn?

rnrn

The amount you earn depends on the interest rate and how much you deposit. Compared to traditional accounts that may offer almost no interest, high-yield accounts can provide significantly better returns over time.

rnrn

For example, keeping a steady balance in a high-yield account allows your money to grow through compound interest—meaning you earn interest not just on your initial deposit, but also on the interest you’ve already earned.

rnrn

While it won’t make you rich overnight, it’s one of the safest ways to grow your savings consistently.

rnrn

What to Look for in a High-Yield Savings Account

rnrn

Not all accounts are the same, so it’s important to compare your options carefully. Here are a few key things to consider:

rnrn

1. Interest Rate (APY)

rnrn

Look for competitive rates, but also check if they are variable or fixed.

rnrn

2. Fees

rnrn

Some accounts charge monthly maintenance fees that can eat into your earnings. Ideally, choose a no-fee account.

rnrn

3. Minimum Balance Requirements

rnrn

Some banks require a minimum deposit to open or maintain the account.

rnrn

4. Accessibility

rnrn

Make sure the account allows easy transfers and withdrawals when needed.

rnrn

5. Bank Reputation

rnrn

Choose a trusted bank with strong customer reviews and reliable service.

rnrn

High-Yield Savings vs Other Investment Options

rnrn

High-yield savings accounts are often compared to other ways of growing money. While they don’t offer the high returns of stocks or real estate, they provide unmatched safety.

rnrn

Stocks: Higher returns but higher risk
rnCrypto: Very volatile and unpredictable
rnReal Estate: Long-term growth but requires large capital
rnSavings Accounts: Low risk, steady growth

rnrn

For many people, a high-yield savings account is a foundation—something you use alongside other investments.

rnrn

Best Uses for a High-Yield Savings Account

rnrn

These accounts are ideal for specific financial goals:

rnrn

Emergency funds
rnShort-term savings (vacations, large purchases)
rnDown payment for a home
rnBackup cash for unexpected expenses

rnrn

Because your money is safe and accessible, it’s perfect for situations where you don’t want to take risks.

rnrn

Common Mistakes to Avoid

rnrn

One common mistake is leaving money in a low-interest account without realizing better options exist. Over time, this can cost you a significant amount in lost earnings.

rnrn

Another mistake is chasing the highest rate without checking fees or conditions. A slightly lower rate with no fees can sometimes be a better deal.

rnrn

Also, avoid treating a savings account like a checking account. Frequent withdrawals can limit your growth and may come with restrictions.

rnrn

How to Get Started

rnrn

Opening a high-yield savings account is simple. Most banks allow you to apply online in just a few minutes. You’ll need basic information such as your ID, Social Security number, and an initial deposit.

rnrn

Once your account is set up, consider automating transfers from your checking account. This helps you build your savings consistently without thinking about it.

rnrn

Final Thoughts

rnrn

A high-yield savings account is one of the easiest and safest ways to grow your money. It won’t replace high-risk investments, but it plays an important role in any smart financial strategy.

rnrn

By choosing the right account, staying consistent with your savings, and avoiding unnecessary fees, you can build a strong financial foundation over time. In a world full of risky options, sometimes the smartest move is the one that protects your money while still helping it grow.

rnrn


rnrn

Financial professionals recommend using FDIC-insured banks, trusted financial institutions, and certified financial planning strategies when choosing savings accounts to ensure safety, reliability, and steady long-term growth.

rn

SEO Meta Title Health Insurance for Self-Employed: Plan Comparison Guide

Self-employed workers face a different health insurance challenge than employees with a company plan. Freelancers, consultants, rideshare drivers, small business owners, real estate agents, and independent contractors must compare coverage, costs, networks, and tax issues on their own. The best plan is not always the cheapest monthly premium. It is the plan that fits your health needs, budget, doctors, prescriptions, and risk tolerance.

Start with the total yearly cost, not just the premium. The monthly premium is the amount you pay to keep coverage active, but it is only one part of the expense. You also need to review the deductible, copays, coinsurance, out-of-pocket maximum, prescription costs, and whether your preferred doctors are in network. A low premium plan can be expensive if you need frequent care and the deductible is high.

Plan networks matter. Health maintenance organization plans may have lower premiums but may require you to use a narrower network and choose a primary care doctor. Preferred provider organization plans may offer more flexibility but often cost more. Exclusive provider organization plans and point-of-service plans have their own rules. Before enrolling, search the insurer's current provider directory and confirm directly with important doctors because directories can change.

Prescription coverage can make or break a plan. Review the formulary, which is the insurer's list of covered drugs. Check whether your medications are generic, preferred brand, non-preferred brand, or specialty tier. Also look for prior authorization, step therapy, and quantity limits. A plan with a lower premium can become costly if a key medication is not covered well.

If you rarely visit the doctor and mainly want protection against major medical bills, a higher deductible plan may be worth considering. Some high-deductible plans can be paired with a health savings account if they meet specific rules. A health savings account may offer tax advantages, but eligibility and contribution limits can change, so verify current rules with a qualified tax professional or official sources.

If you expect surgery, pregnancy care, ongoing prescriptions, specialist visits, physical therapy, or regular mental health care, a higher premium plan with lower out-of-pocket costs may be smarter. The best comparison is to estimate your likely yearly medical use and calculate what you would pay under each plan.

Self-employed people should also review subsidies and tax deductions. Depending on income and household size, marketplace plans may qualify for premium tax credits. Income estimates are important because overestimating or underestimating can affect costs and reconciliation at tax time. Self-employed health insurance deductions may also be available, but rules depend on your business structure, profit, other coverage access, and tax situation.

Do not ignore dental and vision coverage. Marketplace medical plans may not include adult dental or vision benefits. If those services matter to you, compare standalone plans or discount programs. Also review whether children need pediatric dental coverage.

Short-term health plans, health care sharing ministries, and limited benefit plans may look attractive because of lower monthly costs, but they may not cover pre-existing conditions, essential health benefits, prescriptions, maternity care, mental health, or major claims the way comprehensive health insurance does. Read exclusions carefully before choosing a nontraditional option.

Open enrollment deadlines are important. You usually need a qualifying life event to enroll outside the regular window. Examples may include losing other coverage, moving, marriage, divorce, birth, adoption, or certain income changes. Rules vary, so check official marketplace guidance for your state.

When comparing plans, make a simple worksheet with columns for premium, deductible, out-of-pocket maximum, primary care copay, specialist copay, urgent care, emergency room, prescription tiers, network type, key doctors, key medications, and estimated annual cost. This turns a confusing decision into a side-by-side comparison.

Health insurance is a financial planning decision as much as a medical decision. Self-employed workers need coverage that protects their health and their business income. A plan that keeps care accessible can prevent a medical issue from becoming a financial crisis.