Friday, October 30

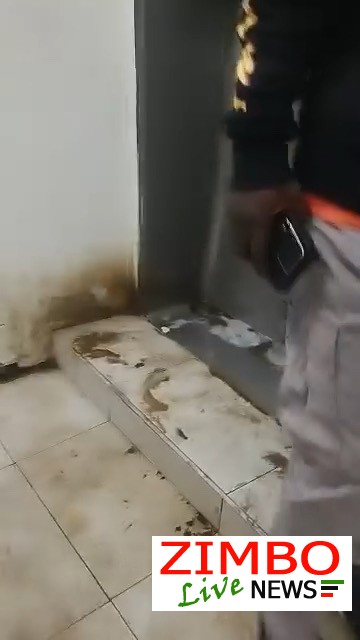
Video Re Toilet Yeku Rufaro Stadium Mashura

A video shared by Makomborero Mutimukulu which was taken at Rufaro Stadium shows toilets flooded with a mixture of urine and water, forcing people to step through the dirty water to access the facilities, raising serious hygiene concerns at one of the country’s major football venues.
 

  • Share:

Info News

Can Credit Repair Companies Really Remove Collections?

Credit repair advertisements are everywhere.

rnrn

“Boost your credit score fast.”

rnrn

“Remove collections instantly.”

rnrn

“Fix bad credit now.”

rnrn

Sounds amazing, right?

rnrn

But many people eventually wonder something important.

rnrn

Can credit repair companies really remove collections?

rnrn

The answer is more complicated than most advertisements make it seem.

rnrn

Some collection accounts can be challenged successfully. Others remain permanently difficult to remove.

rnrn

Understanding how the process actually works can save you money, stress, and unrealistic expectations.

rnrn

What Collection Accounts Do to Your Credit Score

rnrn

Collections can seriously damage credit scores.

rnrn

Especially when accounts remain unpaid.

rnrn

Lenders often see collections as signs of financial risk.

rnrn

That may affect:

rnrn
    rn
  • Loan approvals
  • rn
  • Mortgage applications
  • rn
  • Car financing
  • rn
  • Credit card offers
  • rn
  • Insurance pricing
  • rn
  • Apartment applications
  • rn
rnrn

Even small collections can create major problems.

rnrn

What Credit Repair Companies Actually Do

rnrn

Many people assume credit repair companies have special legal powers.

rnrn

They do not.

rnrn

Most legitimate companies simply:

rnrn
    rn
  • Review credit reports
  • rn
  • Identify inaccurate information
  • rn
  • Dispute questionable accounts
  • rn
  • Communicate with credit bureaus
  • rn
  • Negotiate with creditors
  • rn
rnrn

Consumers can legally perform many of these steps themselves.

rnrn

That surprises a lot of people.

rnrn

When Collection Accounts Can Be Removed

rnrn

This is the part many companies avoid explaining clearly.

rnrn

Collections usually get removed only under specific situations.

rnrn

Incorrect Information

rnrn

If a collection contains inaccurate details, it may qualify for removal.

rnrn

Examples include:

rnrn
    rn
  • Wrong balances
  • rn
  • Incorrect dates
  • rn
  • Identity errors
  • rn
  • Duplicate accounts
  • rn
  • Fraudulent debts
  • rn
rnrn

Credit bureaus must investigate disputed information.

rnrn

Lack of Verification

rnrn

Debt collectors must verify debts when challenged.

rnrn

If they fail to provide proper documentation, accounts may sometimes be removed.

rnrn

But this does not happen automatically.

rnrn

Pay-for-Delete Agreements

rnrn

Some collection agencies agree to remove accounts after payment.

rnrn

This is called a pay-for-delete arrangement.

rnrn

Not all agencies allow this.

rnrn

And some major creditors refuse entirely.

rnrn

What Credit Repair Companies Cannot Legally Do

rnrn

This is extremely important.

rnrn

No legitimate company can legally remove accurate negative information simply because you want it gone.

rnrn

That includes:

rnrn
    rn
  • Legitimate late payments
  • rn
  • Valid collections
  • rn
  • Accurate defaults
  • rn
  • Real repossessions
  • rn
  • Correct bankruptcies
  • rn
rnrn

If a company guarantees instant deletion of accurate debts, that’s a major warning sign.

rnrn

Warning Signs of Credit Repair Scams

rnrn

The credit repair industry attracts many bad actors.

rnrn

Be cautious if companies:

rnrn
    rn
  • Demand large upfront fees
  • rn
  • Promise guaranteed score increases
  • rn
  • Tell you to create a new identity
  • rn
  • Instruct you to lie on applications
  • rn
  • Claim they can erase all bad credit
  • rn
rnrn

Those tactics may create legal problems.

rnrn

How Long Collections Stay on Credit Reports

rnrn

Most collections remain on credit reports for up to seven years.

rnrn

However, their impact may decrease over time.

rnrn

Newer collections typically damage scores more heavily than older ones.

rnrn

Paying collections may also improve lending opportunities in some situations.

rnrn

DIY Credit Repair vs Hiring Professionals

rnrn

Some people successfully dispute collections themselves.

rnrn

Others prefer professional assistance because the process becomes time-consuming.

rnrn

A good credit repair company may help organize disputes and communication more efficiently.

rnrn

But consumers should understand what they are paying for.

rnrn

Other Ways to Improve Credit Faster

rnrn

Removing collections is only one piece of the puzzle.

rnrn

Strong credit improvement strategies often include:

rnrn
    rn
  • Making on-time payments
  • rn
  • Lowering credit card balances
  • rn
  • Avoiding unnecessary hard inquiries
  • rn
  • Keeping older accounts open
  • rn
  • Monitoring credit reports regularly
  • rn
rnrn

Consistent habits matter more than quick tricks.

rnrn

Why Credit Repair Keywords Have High CPC

rnrn

Credit repair leads are extremely valuable to:

rnrn
    rn
  • Financial service companies
  • rn
  • Lenders
  • rn
  • Debt consolidation firms
  • rn
  • Credit monitoring providers
  • rn
  • Personal finance platforms
  • rn
rnrn

That strong commercial intent drives aggressive advertising competition.

rnrn

Final Takeaway

rnrn

Credit repair companies can sometimes help remove collection accounts, but only under specific circumstances.

rnrn

Accurate negative information usually cannot legally disappear overnight.

rnrn

The best results often come from realistic expectations, careful financial habits, and understanding your legal rights during the credit dispute process.

rnrn

If something sounds too good to be true in the credit repair industry, it usually is.

rnrn

FAQ

rnrn

Can paying a collection remove it from my credit report?

rnrn

Not automatically. Some agencies may agree to pay-for-delete arrangements, but many do not.

rnrn

Are credit repair companies legitimate?

rnrn

Some are legitimate, but consumers should research carefully because scams exist in the industry.

rnrn

How long do collections stay on credit reports?

rnrn

Most collections remain for up to seven years.

rnrn

Can I dispute collections myself?

rnrn

Yes. Consumers have the legal right to dispute inaccurate information directly with credit bureaus.

rnrn

Do paid collections still affect credit scores?

rnrn

They may still affect scores, though some scoring models weigh paid collections differently.

rn

High-Yield Savings Accounts: Where to Invest Safely and Grow Your Money

If you’re looking for a safe place to grow your money without taking big risks, a high-yield savings account is one of the smartest options available today. Unlike traditional savings accounts that offer very low interest, high-yield accounts provide better returns while still keeping your money easily accessible. For many people, they strike the perfect balance between security and growth.

rnrn

In today’s uncertain economy, more individuals are moving their money into high-interest savings accounts to protect their cash while earning passive income. Whether you’re building an emergency fund, saving for a home, or just trying to make your money work harder, understanding how these accounts work can help you make better financial decisions.

rnrn

What Is a High-Yield Savings Account?

rnrn

A high-yield savings account is a type of bank account that offers a higher interest rate compared to standard savings accounts. These accounts are typically offered by online banks, which can afford to pay better rates because they have lower operating costs than traditional brick-and-mortar banks.

rnrn

The interest you earn is usually expressed as APY (annual percentage yield), which shows how much your money can grow over time. Even a small difference in APY can significantly impact your savings in the long run.

rnrn

Why More People Are Choosing High-Yield Savings Accounts

rnrn

One of the biggest reasons people switch to high-yield savings accounts is simple: better returns without added risk. Unlike stocks or crypto investments, your money is not exposed to market volatility.

rnrn

Another major benefit is liquidity. You can access your money when you need it, making these accounts ideal for emergency funds or short-term savings goals.

rnrn

There’s also peace of mind. Most high-yield savings accounts in the U.S. are insured by the Federal Deposit Insurance Corporation (FDIC), which protects your deposits up to certain limits. This means your money remains safe even if the bank faces issues.

rnrn

How Much Can You Earn?

rnrn

The amount you earn depends on the interest rate and how much you deposit. Compared to traditional accounts that may offer almost no interest, high-yield accounts can provide significantly better returns over time.

rnrn

For example, keeping a steady balance in a high-yield account allows your money to grow through compound interest—meaning you earn interest not just on your initial deposit, but also on the interest you’ve already earned.

rnrn

While it won’t make you rich overnight, it’s one of the safest ways to grow your savings consistently.

rnrn

What to Look for in a High-Yield Savings Account

rnrn

Not all accounts are the same, so it’s important to compare your options carefully. Here are a few key things to consider:

rnrn

1. Interest Rate (APY)

rnrn

Look for competitive rates, but also check if they are variable or fixed.

rnrn

2. Fees

rnrn

Some accounts charge monthly maintenance fees that can eat into your earnings. Ideally, choose a no-fee account.

rnrn

3. Minimum Balance Requirements

rnrn

Some banks require a minimum deposit to open or maintain the account.

rnrn

4. Accessibility

rnrn

Make sure the account allows easy transfers and withdrawals when needed.

rnrn

5. Bank Reputation

rnrn

Choose a trusted bank with strong customer reviews and reliable service.

rnrn

High-Yield Savings vs Other Investment Options

rnrn

High-yield savings accounts are often compared to other ways of growing money. While they don’t offer the high returns of stocks or real estate, they provide unmatched safety.

rnrn

Stocks: Higher returns but higher risk
rnCrypto: Very volatile and unpredictable
rnReal Estate: Long-term growth but requires large capital
rnSavings Accounts: Low risk, steady growth

rnrn

For many people, a high-yield savings account is a foundation—something you use alongside other investments.

rnrn

Best Uses for a High-Yield Savings Account

rnrn

These accounts are ideal for specific financial goals:

rnrn

Emergency funds
rnShort-term savings (vacations, large purchases)
rnDown payment for a home
rnBackup cash for unexpected expenses

rnrn

Because your money is safe and accessible, it’s perfect for situations where you don’t want to take risks.

rnrn

Common Mistakes to Avoid

rnrn

One common mistake is leaving money in a low-interest account without realizing better options exist. Over time, this can cost you a significant amount in lost earnings.

rnrn

Another mistake is chasing the highest rate without checking fees or conditions. A slightly lower rate with no fees can sometimes be a better deal.

rnrn

Also, avoid treating a savings account like a checking account. Frequent withdrawals can limit your growth and may come with restrictions.

rnrn

How to Get Started

rnrn

Opening a high-yield savings account is simple. Most banks allow you to apply online in just a few minutes. You’ll need basic information such as your ID, Social Security number, and an initial deposit.

rnrn

Once your account is set up, consider automating transfers from your checking account. This helps you build your savings consistently without thinking about it.

rnrn

Final Thoughts

rnrn

A high-yield savings account is one of the easiest and safest ways to grow your money. It won’t replace high-risk investments, but it plays an important role in any smart financial strategy.

rnrn

By choosing the right account, staying consistent with your savings, and avoiding unnecessary fees, you can build a strong financial foundation over time. In a world full of risky options, sometimes the smartest move is the one that protects your money while still helping it grow.

rnrn


rnrn

Financial professionals recommend using FDIC-insured banks, trusted financial institutions, and certified financial planning strategies when choosing savings accounts to ensure safety, reliability, and steady long-term growth.

rn