Tuesday, October 13

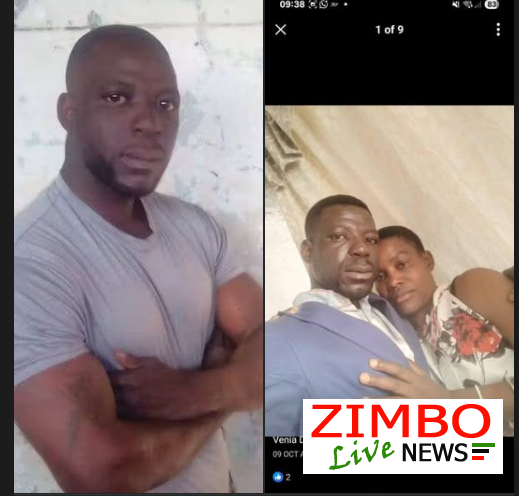
Veina Dumbu Anotsvaga Mushure Mekuponda Musikana kuMwenezi

Ndokumbirawo mundibatsire kuposter nyaya iri kundirwadza. Ndinemuzukuru wangu aipondwa neboyfriend yake, murume anonzi Veina Dumbu, uyo akabva atiza mushure mekuuraya mwana. Pari zvino, vari kumba vatori nechitunha mumba vachimirira mapurisa kuti vauye kuzotora nyaya iyi. Zvaitika izvi zviri kunzi zvakaitika kuMwenezi, kunzvimbo inonzi Kuchivingo, musi wa 17/11/2025, uye mhuri yave kurwadziwa zvikuru nekurasikirwa nemwana avaika. Tiri kukumbira rubatsiro rwenyu kuti nyaya iyi isvike kune veruzhinji kuitira kuti murume uyu abatwe nekukurumidza.

  • Share:

Info News

Personal Injury Lawyer Questions Before Hiring

After an accident, choosing a personal injury lawyer can feel overwhelming. You may be dealing with medical appointments, missed work, insurance calls, vehicle repairs, pain, and uncertainty about what happens next. A lawyer can help with claim strategy, evidence, deadlines, negotiations, and litigation, but not every attorney is the right fit for every case.

The first question is experience. Ask whether the attorney has handled cases similar to yours. A car accident case is different from a trucking accident, medical malpractice claim, workplace third-party claim, defective product case, or premises liability case. Similar case experience can help the lawyer understand evidence, expert witnesses, insurance tactics, and likely challenges.

Next, ask who will actually handle the file. In some firms, the lawyer you meet may not be the person managing daily communication. Paralegals, case managers, associates, and investigators may all be involved. That is normal, but you should know who your main contact will be and how often you will receive updates.

Fees are important. Many personal injury lawyers work on a contingency fee, meaning they are paid a percentage of the recovery if money is obtained. Ask what percentage applies, whether it changes if a lawsuit is filed, and how case expenses are handled. Expenses may include filing fees, medical records, depositions, expert witnesses, investigation, and trial exhibits. Ask whether expenses are deducted before or after the attorney fee and whether you owe expenses if there is no recovery.

Ask about the strength and weakness of your case. A trustworthy lawyer should not promise a guaranteed result. They should discuss liability, damages, insurance limits, prior injuries, medical documentation, comparative fault, witness issues, and possible defenses. If a lawyer only tells you what you want to hear, be cautious.

Evidence can determine the outcome of a claim. Ask what evidence should be gathered immediately. This may include accident reports, photographs, video footage, witness statements, medical records, employer wage records, vehicle data, inspection records, maintenance records, or property incident reports. Some evidence can disappear quickly, so early action matters.

Medical treatment is another key topic. Personal injury claims often depend on documented injuries, treatment consistency, diagnosis, prognosis, and how the injury affects daily life. Follow medical advice and keep records of appointments, prescriptions, therapy, restrictions, and out-of-pocket expenses. Do not exaggerate, but do not minimize symptoms either.

Ask how the attorney evaluates settlement offers. A settlement should consider medical bills, future care, lost income, reduced earning capacity, pain and suffering, property damage, permanent impairment, and other legally recognized damages. The exact rules vary by state and case type. The attorney should explain the factors, not just give a quick number.

Timeline is another area to discuss. Some claims settle in months, while others take much longer, especially if injuries are serious or liability is disputed. A lawyer may recommend waiting until you reach maximum medical improvement before settlement so future medical needs are clearer. Settling too early can be risky because you usually release claims permanently.

Communication expectations should be clear. Ask how quickly calls or emails are returned, whether the firm uses a client portal, and what updates you will receive. A good lawyer-client relationship requires trust, responsiveness, and organized documentation.

You should also ask whether the lawyer is prepared to file a lawsuit if necessary. Many cases settle, but the willingness and ability to litigate can affect negotiation leverage. Ask about trial experience, recent results, and how the firm prepares cases.

This article is general information, not legal advice. Personal injury laws, deadlines, damages, and fault rules vary by state. Speak with a licensed attorney in your jurisdiction to understand your rights. The best lawyer for your case is someone with relevant experience, clear communication, transparent fees, and a realistic plan for proving your claim.

SEO Meta Title Credit Repair vs Credit Counseling: Compare Your Options

When credit problems become stressful, two options often appear in search results: credit repair and credit counseling. They sound similar, but they are not the same service. Credit repair focuses on disputing inaccurate, incomplete, or unverifiable information on credit reports. Credit counseling focuses on budgeting, debt repayment, and financial education. Knowing the difference can help you avoid scams and choose the right help.

Credit repair companies often advertise help with removing negative items from credit reports. Legitimate credit repair is based on your legal right to dispute inaccurate information. If a late payment, collection, account balance, personal detail, or account status is wrong, you can dispute it with the credit bureaus and the company that furnished the information.

However, accurate negative information usually cannot be removed simply because it hurts your score. Late payments, collections, bankruptcies, and charge-offs may remain on credit reports for legally allowed periods if they are accurate. Be cautious with any company that promises a specific score increase, guaranteed removals, or a new credit identity.

Credit counseling is different. A nonprofit credit counseling agency can review income, expenses, debts, and goals. Counselors may help build a budget, explain credit reports, suggest repayment strategies, and discuss whether a debt management plan makes sense. A debt management plan may consolidate payments through the counseling agency and sometimes reduce interest rates or fees with participating creditors.

Credit counseling can be useful when the main problem is debt affordability. If you are making minimum payments, falling behind, or using one card to pay another, a counselor can help create a structured plan. Credit repair alone will not solve unaffordable debt.

Credit repair can be useful when the main problem is inaccurate reporting. For example, an account that does not belong to you, a debt listed twice, an incorrect late payment, a paid account still shown as unpaid, or outdated information may be disputable. You can file disputes yourself for free, but some people hire help because they do not want to manage the paperwork.

Before paying for credit repair, understand your rights. In the United States, credit repair companies must follow federal rules, including restrictions on misleading claims and upfront fees. You should receive a written contract, cancellation rights, and clear information about what the company will do. If a company pressures you, asks you to lie, tells you to dispute everything, or suggests using a different Social Security number, walk away.

A strong credit rebuilding plan often includes both cleanup and behavior changes. Start by pulling credit reports from the major bureaus. Review personal information, open accounts, closed accounts, collections, public records, inquiries, balances, and payment history. Highlight anything inaccurate and gather supporting documents.

Next, pay every current bill on time. Payment history is a major scoring factor. Set up reminders or autopay for minimum payments. Then focus on credit utilization, which is the percentage of available revolving credit being used. Lower balances can help improve scores over time.

Avoid opening too many new accounts at once. New inquiries and new accounts can lower scores temporarily. Instead, build a steady pattern: pay on time, reduce balances, keep older accounts in good standing, and monitor reports for errors.

If you have no active credit, a secured credit card or credit-builder loan may help, but fees and terms matter. Choose products from reputable banks or credit unions and avoid high-fee cards that drain your budget.

The right choice depends on the root problem. Choose credit repair if the issue is inaccurate reporting. Choose credit counseling if the issue is debt management, budgeting, or missed payments. Use both if you have errors and unaffordable debt. Most importantly, avoid anyone promising instant results. Real credit improvement takes accurate reporting, consistent payments, lower debt, and time.