Sunday, October 11

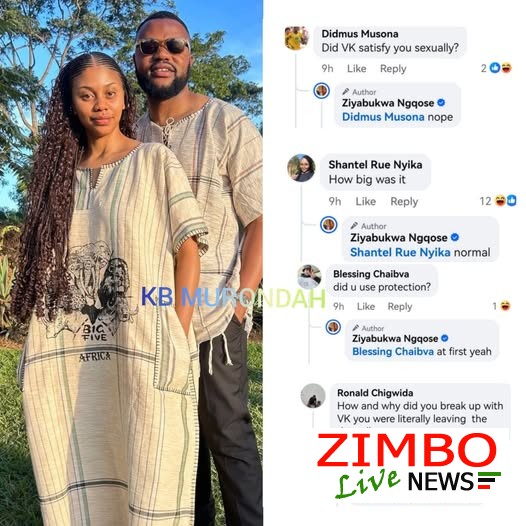
South African Influencer Ziya Exposes Shocking Allegations Against VK LionHeart Anedora & Ayindirova

Social media is in uproar following explosive claims made by South African influencer Ziya Ngqose, who has publicly accused Zimbabwean social media personality VK LionHeart of mistreatment during their alleged past relationship. In a series of emotional posts, Ziya claimed that VK repeatedly humiliated her, emotionally abused her, and constantly made degrading remarks meant to destroy her confidence. She alleged that instead of offering support, VK allegedly mocked her and used intimidation and physical aggression during heated arguments.

Ziya further claimed that VK often compared her unfairly to other women and attempted to shame her body, despite her insisting she was completely normal and confident in herself. According to her, the relationship was marked by control, verbal attacks, and moments of violence that left her feeling broken and silenced. These allegations have sparked widespread debate online, with many users calling for accountability while others urge both parties to address the matter responsibly. As of now, VK LionHeart has not issued a detailed response, but the story continues to dominate timelines across Zimbabwean and South African social media platforms.

  • Share:

Info News

Best Term Life Insurance Policies for Families

Term life insurance is one of the simplest ways to protect your family financially if something unexpected happens. It provides coverage for a set period, which makes it a practical choice for families who want affordable protection during the years they need it most.
rnMany families choose term life because it can offer a large amount of coverage at a lower monthly cost than permanent life insurance. That is especially useful if you are paying a mortgage, raising children, or trying to replace income for a spouse or partner. The main goal is to make sure your family would have enough support if you were no longer there.
rnWhen comparing policies, focus on coverage amount, term length, and insurer reliability. A policy should be large enough to cover living expenses, debts, childcare, and future costs such as college or mortgage payments. The right term length usually matches your biggest financial responsibilities.
rnIt is also smart to compare riders and policy features. Some policies offer options like accelerated death benefits or conversion privileges, which can add flexibility later. Even though these extras may not matter right away, they can become important as your family’s needs change.
rnHealth and age play a major role in pricing. In many cases, younger and healthier applicants get lower premiums. That is why it often makes sense to buy coverage before health issues appear or before your family’s financial needs increase.
rnA good term life policy should be easy to understand and simple to maintain. You want a plan that gives your family peace of mind without forcing you into complicated features you do not need. For most families, clarity and affordability matter more than anything else.
rnIf you are comparing policies for the first time, think about what your family would need if your income stopped tomorrow. That question can help you choose the right coverage amount and avoid buying too little protection.
rnThe best term life insurance policy is the one that fits your budget today while protecting your family’s future.

rnrn


rn

Mortgage Refinance Guide: Costs, Rates, and Break-Even Math


A lower mortgage rate sounds attractive, but refinancing is not always a guaranteed win. A refinance replaces your current mortgage with a new loan, and that new loan usually comes with closing costs, a new term, new paperwork, and sometimes a reset payoff timeline. The right question is not simply, Can I get a lower rate? The better question is, Will this refinance improve my finances after all costs are included?

The most common reason to refinance is to lower the interest rate. A lower rate can reduce the monthly payment and total interest over time. However, closing costs can include lender fees, appraisal fees, title fees, recording fees, credit report fees, prepaid taxes, prepaid insurance, and points. Some lenders advertise no-closing-cost refinancing, but the costs may be rolled into the loan balance or covered through a higher rate.

The break-even point is one of the most important calculations. Divide the total refinance cost by the monthly savings. If closing costs are $4,000 and the refinance saves $200 per month, the break-even point is 20 months. If you plan to stay in the home longer than that, the refinance may make sense. If you expect to sell or move before then, the savings may never catch up.

Loan term matters. Refinancing from a 30-year mortgage into a new 30-year mortgage can lower the payment but may extend debt far into the future. That can increase total interest even with a lower rate. Some homeowners choose a 15-year or 20-year refinance to pay off the home faster, but the payment may be higher. Others choose a new 30-year term for cash-flow relief. The best choice depends on monthly budget, retirement timeline, and long-term goals.

A cash-out refinance allows a homeowner to borrow more than the current mortgage balance and receive the difference in cash. People use cash-out refinancing for home improvements, debt consolidation, education, or emergency reserves. This can be useful when the numbers work, but it also increases the mortgage balance and puts the home at risk if payments become unaffordable.

Refinancing from an adjustable-rate mortgage to a fixed-rate mortgage can also be smart when payment stability matters. Adjustable rates may start lower but can change later based on the loan terms. A fixed rate can provide predictability, especially for homeowners who plan to stay long term.

Credit score, home equity, income, debt-to-income ratio, property type, and appraisal value can all affect refinance options. A stronger credit profile and more equity may qualify for better rates. If the home value has increased, refinancing may also help remove private mortgage insurance if requirements are met.

Points deserve careful review. Discount points are upfront fees paid to reduce the interest rate. Buying points can make sense if you plan to keep the loan long enough to recover the cost through lower payments. If you may move, sell, or refinance again soon, paying points may not be worthwhile.

Before applying, gather the current mortgage statement, homeowners insurance details, property tax information, income documents, credit information, and an estimate of home value. Ask lenders for loan estimates using the same loan type and term so comparisons are fair.

Questions to ask include: What is the APR? What are total closing costs? Are costs paid upfront or rolled into the loan? What is the new loan balance? What is the break-even point? Are there prepayment penalties? How long will underwriting take? Does the rate lock have a fee? What happens if the appraisal comes in low?

Refinancing can be a powerful financial move when it lowers total costs, improves stability, removes mortgage insurance, shortens the term, or supports a smart cash-flow plan. It can be a mistake when it only lowers the payment by extending debt or adding costs that never pay off. Run the numbers before signing.