Tuesday, October 06

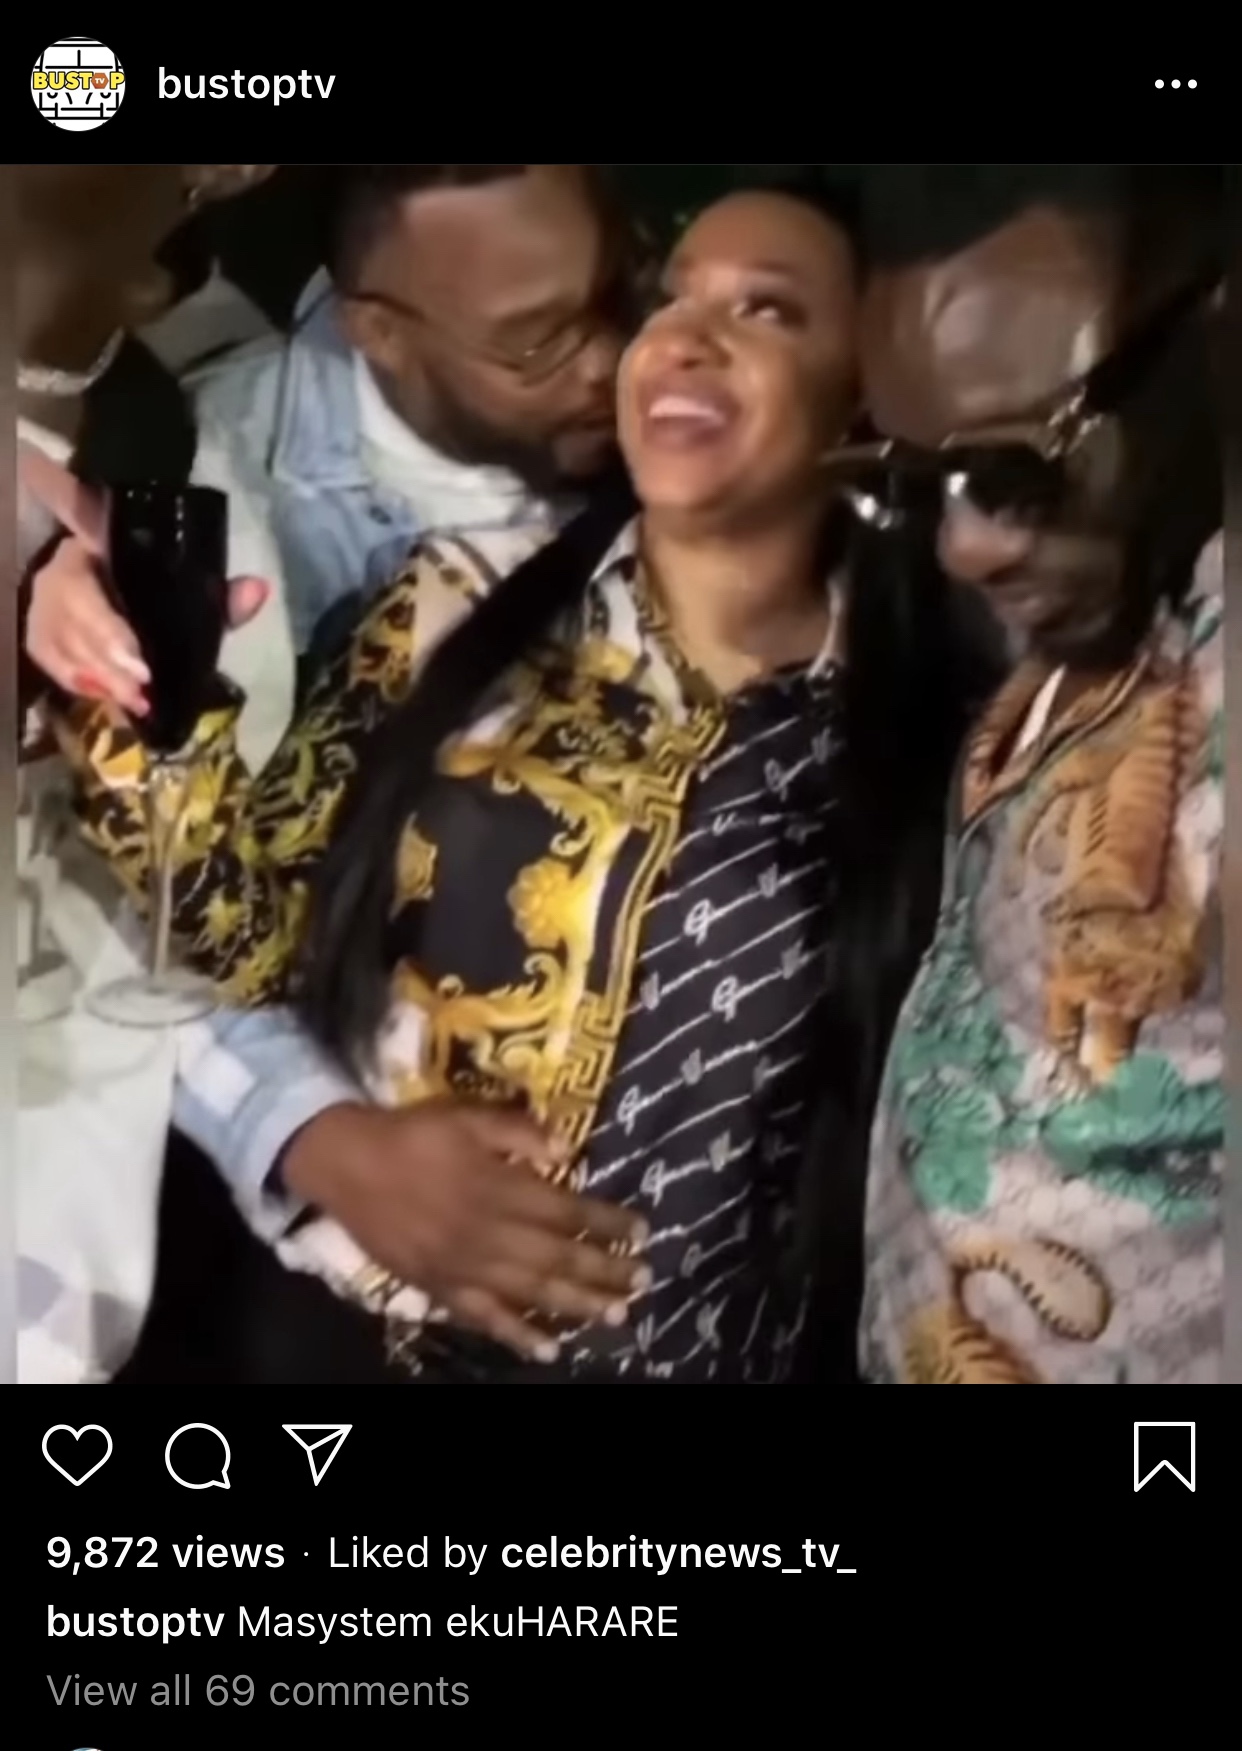
Pokello Birthday Party With Ginimbi & Enzo Ishall

Pokello celebrated her birthday in style and she parties with Zimbabwes top celebrities which included Ginimbi Enzo Ishall and many more of Zimbabwes top socialites. Pokello and her friends parties till the early hours of the morning. See video below.


  • Share:

Info News

Personal Injury Lawyer Questions Before Hiring

After an accident, choosing a personal injury lawyer can feel overwhelming. You may be dealing with medical appointments, missed work, insurance calls, vehicle repairs, pain, and uncertainty about what happens next. A lawyer can help with claim strategy, evidence, deadlines, negotiations, and litigation, but not every attorney is the right fit for every case.

The first question is experience. Ask whether the attorney has handled cases similar to yours. A car accident case is different from a trucking accident, medical malpractice claim, workplace third-party claim, defective product case, or premises liability case. Similar case experience can help the lawyer understand evidence, expert witnesses, insurance tactics, and likely challenges.

Next, ask who will actually handle the file. In some firms, the lawyer you meet may not be the person managing daily communication. Paralegals, case managers, associates, and investigators may all be involved. That is normal, but you should know who your main contact will be and how often you will receive updates.

Fees are important. Many personal injury lawyers work on a contingency fee, meaning they are paid a percentage of the recovery if money is obtained. Ask what percentage applies, whether it changes if a lawsuit is filed, and how case expenses are handled. Expenses may include filing fees, medical records, depositions, expert witnesses, investigation, and trial exhibits. Ask whether expenses are deducted before or after the attorney fee and whether you owe expenses if there is no recovery.

Ask about the strength and weakness of your case. A trustworthy lawyer should not promise a guaranteed result. They should discuss liability, damages, insurance limits, prior injuries, medical documentation, comparative fault, witness issues, and possible defenses. If a lawyer only tells you what you want to hear, be cautious.

Evidence can determine the outcome of a claim. Ask what evidence should be gathered immediately. This may include accident reports, photographs, video footage, witness statements, medical records, employer wage records, vehicle data, inspection records, maintenance records, or property incident reports. Some evidence can disappear quickly, so early action matters.

Medical treatment is another key topic. Personal injury claims often depend on documented injuries, treatment consistency, diagnosis, prognosis, and how the injury affects daily life. Follow medical advice and keep records of appointments, prescriptions, therapy, restrictions, and out-of-pocket expenses. Do not exaggerate, but do not minimize symptoms either.

Ask how the attorney evaluates settlement offers. A settlement should consider medical bills, future care, lost income, reduced earning capacity, pain and suffering, property damage, permanent impairment, and other legally recognized damages. The exact rules vary by state and case type. The attorney should explain the factors, not just give a quick number.

Timeline is another area to discuss. Some claims settle in months, while others take much longer, especially if injuries are serious or liability is disputed. A lawyer may recommend waiting until you reach maximum medical improvement before settlement so future medical needs are clearer. Settling too early can be risky because you usually release claims permanently.

Communication expectations should be clear. Ask how quickly calls or emails are returned, whether the firm uses a client portal, and what updates you will receive. A good lawyer-client relationship requires trust, responsiveness, and organized documentation.

You should also ask whether the lawyer is prepared to file a lawsuit if necessary. Many cases settle, but the willingness and ability to litigate can affect negotiation leverage. Ask about trial experience, recent results, and how the firm prepares cases.

This article is general information, not legal advice. Personal injury laws, deadlines, damages, and fault rules vary by state. Speak with a licensed attorney in your jurisdiction to understand your rights. The best lawyer for your case is someone with relevant experience, clear communication, transparent fees, and a realistic plan for proving your claim.

SEO Meta Title Car Insurance Quotes: Compare Coverage and Save

Car insurance quotes can look simple at first glance, but two policies with the same monthly price can offer very different protection. One may include stronger liability limits, rental reimbursement, roadside assistance, accident forgiveness, or better uninsured motorist coverage. Another may look cheaper because it has a high deductible, low limits, or fewer coverage options. To avoid overpaying or buying weak coverage, compare quotes line by line.

Start with liability coverage. Liability insurance helps pay for injuries or property damage you cause to others in a covered accident. Most states require a minimum amount, but minimum coverage can be too low after a serious crash. Medical bills, vehicle repairs, legal defense, and judgments can rise quickly. When comparing quotes, look at bodily injury liability per person, bodily injury liability per accident, and property damage liability.

Next, review collision and comprehensive coverage. Collision coverage may help repair or replace your vehicle after a covered crash, regardless of who was at fault. Comprehensive coverage may help with theft, vandalism, hail, fire, falling objects, and certain weather-related damage. If you have a loan or lease, your lender may require both. If your vehicle is older and paid off, you can compare the cost of keeping physical damage coverage against the value of the car and your ability to replace it.

Uninsured and underinsured motorist coverage is often overlooked. It may help if another driver causes an accident and has no insurance or not enough insurance. In some states, this coverage can also apply to hit-and-run situations. Because not every driver carries strong limits, this coverage can be important even for careful drivers.

Medical payments coverage or personal injury protection may help with medical costs after an accident. The names and rules vary by state. Some states require personal injury protection, while others make it optional. If you already have health insurance, you may still want to understand how deductibles, passengers, lost wages, and claim handling work under your auto policy.

Deductibles are another major price factor. A higher deductible can lower the premium, but it also means you pay more out of pocket when filing a claim. Choose a deductible you could realistically pay after an accident. Saving a few dollars per month may not be worth it if the deductible would create financial stress.

Discounts can make a big difference, but they are not the same at every company. Ask about safe driver discounts, multi-policy discounts, multi-car discounts, good student discounts, defensive driving courses, low mileage programs, telematics programs, anti-theft devices, paperless billing, and paid-in-full discounts. Telematics can reward safe driving, but it may also use driving data such as speed, braking, mileage, and time of day. Read the details before enrolling.

When shopping, collect at least three quotes using the same coverage limits and deductibles. If one quote is much cheaper, ask why. It may exclude something important or use a different coverage level. Also check the insurer's claims reputation, customer service, financial strength, mobile app experience, and local agent availability.

Be careful with the phrase full coverage. It is not a standard legal term. People often use it to mean liability plus comprehensive and collision, but it may not include rental car coverage, gap insurance, roadside assistance, original equipment manufacturer parts, or high liability limits. Instead of asking for full coverage, specify the coverage types and limits you want.

Your personal situation also affects pricing. Insurers may consider your driving record, location, vehicle type, mileage, coverage history, age, claims history, and sometimes credit-based insurance scores where allowed. Because pricing models differ, the cheapest insurer for one driver may not be cheapest for another.

Review your policy after major life changes. Moving, buying a car, paying off a loan, adding a teen driver, getting married, changing jobs, or driving fewer miles can affect your coverage and premium. You should also compare rates before renewal because loyalty does not always guarantee the best price.

The goal is not simply to find the cheapest car insurance quote. The goal is to find a policy that balances price, protection, claim service, and peace of mind. A strong comparison process can help you avoid coverage gaps while still keeping the premium under control.