Saturday, November 07

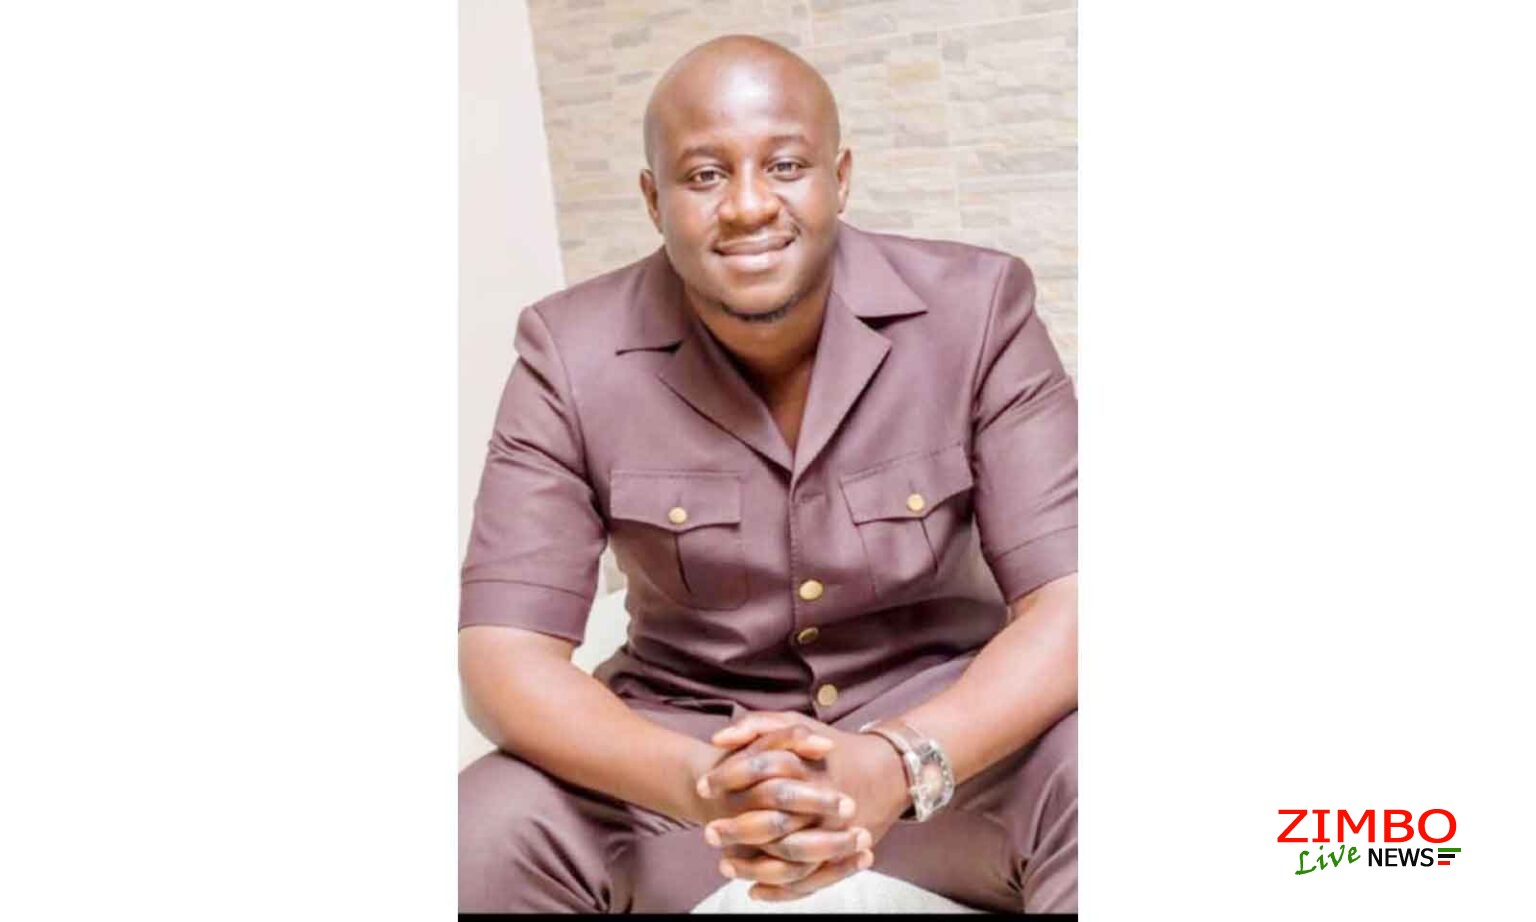
Mbinga Brendon Chirawu Akaponda Brother Yake 33-year-old Gideon Chirawu

A MAN is being accused of stabbing and killing his brother after a dispute, which is said to have started at a farm in Banket, last week.

Brendon and Gideon Chirawu, two brothers from Greystone Park in Harare, were involved in the dispute, which escalated and resulted in the death of one of the brothers. Brendon is accused of stabbing Gideon, leading to his death.

According to sources, after Gideon collapsed, Brendon attempted mouth-to-mouth resuscitation, while waiting for an ambulance.

He is said to have transported Gideon to a hospital but Gideon died before being admitted at a medical facility in Borrowdale.

He was 33.

National police spokesperson Commissioner Paul Nyathi could not be reached for comment at the time of going to print.

No comment, too, could be obtained from the family of the two brothers. 

However, H-Metro can reveal that Brendon was arrested and detained at Borrowdale Police Station before being taken to Banket for further management of the case.

The incident had left Greystone Park residents in shock.

One of the Greystone Park residents, Trynos Kamudyariwa, described Gideon as a good and quiet man.

“We have been saddened by the loss of Gideon. He was so loving and very quiet, and we were shocked by the incident that led to his death,” Kamudyariwa said.

  • Share:

Info News

SEO Meta Title Debt Consolidation Loans: Pros, Cons, and Comparison Tips

Debt consolidation can sound like an easy solution: combine several debts into one payment and possibly lower the interest rate. For some borrowers, that can be helpful. For others, it only moves debt around while the balance continues to grow. The difference depends on the loan terms, fees, spending habits, income stability, and payoff discipline.

A debt consolidation loan is usually a personal loan used to pay off credit cards, medical bills, store cards, payday loans, or other unsecured debts. After the old balances are paid, the borrower makes one fixed monthly payment to the new lender. The main appeal is simplicity. One due date, one payment, and one payoff timeline can make budgeting easier.

The biggest potential benefit is a lower interest rate. Credit cards often charge variable rates that can rise over time. A fixed-rate personal loan may offer a predictable payment and a defined end date. If the new loan has a lower rate and you avoid new debt, consolidation can reduce interest costs and speed up payoff.

However, the monthly payment is not the only number to review. A longer repayment term can lower the monthly payment while increasing total interest paid. For example, stretching debt over several years may feel easier each month but cost more overall. Always compare total repayment, not just the payment amount.

Fees matter too. Some lenders charge origination fees, late fees, returned payment fees, or prepayment penalties. An origination fee may be deducted from the loan amount, which means you receive less money than expected. Compare the annual percentage rate because it includes certain finance charges and gives a better apples-to-apples view than the interest rate alone.

Credit score impact can go in different directions. Applying for a loan may create a hard inquiry. Opening a new account can reduce the average age of credit. However, paying down credit card balances may improve credit utilization, which can help some borrowers over time. The biggest factor remains making on-time payments.

The main risk is running up the old credit cards again. If you consolidate balances and continue using cards without a budget, you may end up with the consolidation loan plus new credit card debt. Before taking a loan, create a spending plan and decide whether to close cards, lower limits, or keep cards open but unused.

Not everyone qualifies for a low rate. Lenders may review credit score, income, debt-to-income ratio, employment history, payment history, and existing balances. Borrowers with stronger credit often receive better terms. If the offers are high-interest, consolidation may not save money.

Alternatives include a balance transfer credit card, nonprofit credit counseling, a debt management plan, negotiating with creditors, budgeting changes, side income, or a structured debt snowball or debt avalanche method. Balance transfers may offer promotional rates, but fees and deadlines matter. Missing the promotional payoff date can lead to higher interest.

Before choosing any offer, write down every debt: creditor, balance, interest rate, minimum payment, due date, and payoff priority. Then compare three scenarios: keeping current payments, using a consolidation loan, and using another strategy. A simple spreadsheet can reveal whether consolidation truly saves money.

Ask lenders these questions: Is the rate fixed or variable? What is the APR? Are there origination fees? Is there a prepayment penalty? What is the total repayment amount? When are funds sent? Can the lender pay creditors directly? What happens if I miss a payment? Are there hardship options?

Debt consolidation works best when it is part of a larger debt payoff plan. The loan should create a clear path out of debt, not a temporary break from the pressure. If the payment fits the budget, the rate is lower, and the borrower stops adding new balances, consolidation can be a useful tool. If not, it may delay the real problem.

SEO Meta Title Credit Repair vs Credit Counseling: Compare Your Options

When credit problems become stressful, two options often appear in search results: credit repair and credit counseling. They sound similar, but they are not the same service. Credit repair focuses on disputing inaccurate, incomplete, or unverifiable information on credit reports. Credit counseling focuses on budgeting, debt repayment, and financial education. Knowing the difference can help you avoid scams and choose the right help.

Credit repair companies often advertise help with removing negative items from credit reports. Legitimate credit repair is based on your legal right to dispute inaccurate information. If a late payment, collection, account balance, personal detail, or account status is wrong, you can dispute it with the credit bureaus and the company that furnished the information.

However, accurate negative information usually cannot be removed simply because it hurts your score. Late payments, collections, bankruptcies, and charge-offs may remain on credit reports for legally allowed periods if they are accurate. Be cautious with any company that promises a specific score increase, guaranteed removals, or a new credit identity.

Credit counseling is different. A nonprofit credit counseling agency can review income, expenses, debts, and goals. Counselors may help build a budget, explain credit reports, suggest repayment strategies, and discuss whether a debt management plan makes sense. A debt management plan may consolidate payments through the counseling agency and sometimes reduce interest rates or fees with participating creditors.

Credit counseling can be useful when the main problem is debt affordability. If you are making minimum payments, falling behind, or using one card to pay another, a counselor can help create a structured plan. Credit repair alone will not solve unaffordable debt.

Credit repair can be useful when the main problem is inaccurate reporting. For example, an account that does not belong to you, a debt listed twice, an incorrect late payment, a paid account still shown as unpaid, or outdated information may be disputable. You can file disputes yourself for free, but some people hire help because they do not want to manage the paperwork.

Before paying for credit repair, understand your rights. In the United States, credit repair companies must follow federal rules, including restrictions on misleading claims and upfront fees. You should receive a written contract, cancellation rights, and clear information about what the company will do. If a company pressures you, asks you to lie, tells you to dispute everything, or suggests using a different Social Security number, walk away.

A strong credit rebuilding plan often includes both cleanup and behavior changes. Start by pulling credit reports from the major bureaus. Review personal information, open accounts, closed accounts, collections, public records, inquiries, balances, and payment history. Highlight anything inaccurate and gather supporting documents.

Next, pay every current bill on time. Payment history is a major scoring factor. Set up reminders or autopay for minimum payments. Then focus on credit utilization, which is the percentage of available revolving credit being used. Lower balances can help improve scores over time.

Avoid opening too many new accounts at once. New inquiries and new accounts can lower scores temporarily. Instead, build a steady pattern: pay on time, reduce balances, keep older accounts in good standing, and monitor reports for errors.

If you have no active credit, a secured credit card or credit-builder loan may help, but fees and terms matter. Choose products from reputable banks or credit unions and avoid high-fee cards that drain your budget.

The right choice depends on the root problem. Choose credit repair if the issue is inaccurate reporting. Choose credit counseling if the issue is debt management, budgeting, or missed payments. Use both if you have errors and unaffordable debt. Most importantly, avoid anyone promising instant results. Real credit improvement takes accurate reporting, consistent payments, lower debt, and time.