Thursday, October 15

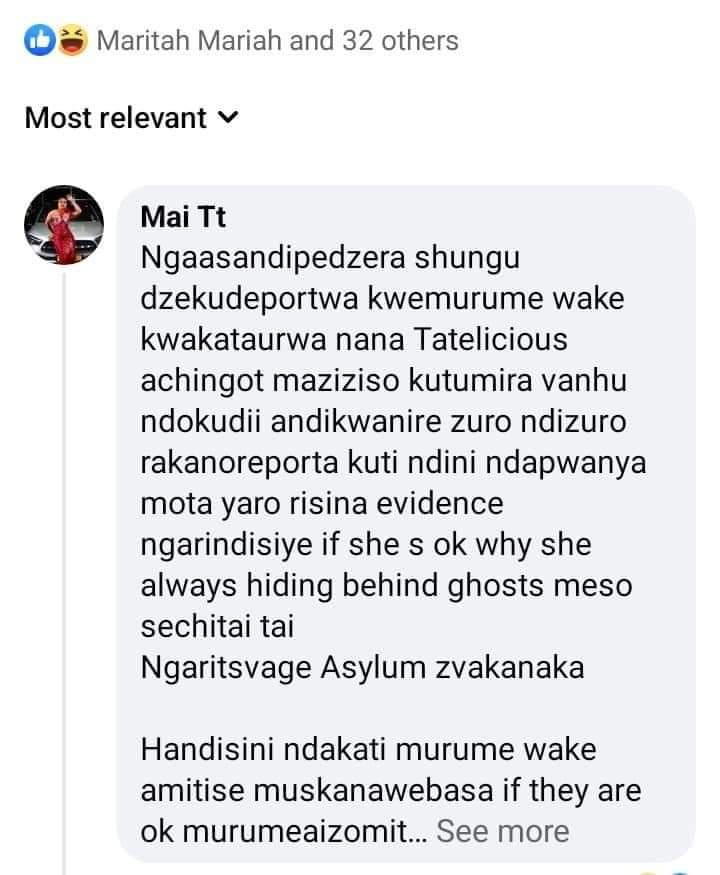
Chikiti Chichituka Madamboss Usandipedzere Shungu Dzeku Depotwa Kwa Ngoni Ku Germany Urimbwa Unehutzinye Otukirira

Mai micky isu tinotaura second hand information munhu akataura izvi nditatelicious enda munoudza iye tatelicous musatipedzere hasha .Asi kunyepa here kuti vaka depotwa?? Tell all your snakes to stay away from cats and we stay away from you.


Muzvibate vasikana ! Im very peaceful today sisi mai micky.Snake inodenha yobvapo yoti anzi stay away from my family kkkk ari OK kupi... Kuzviudza kuti ndakapenga zvinyoka dzikamai imi then zvikiti todzikamawo...Izvezvi akati vakuhurira murume ari kudii kumuendera. Ngoni wacho haana here ku depotwa. 3 years no go Europe.

  • Share:

Info News

Term vs Whole Life Insurance: Compare Costs and Coverage

Life insurance can protect a family from financial hardship if a wage earner, caregiver, or business owner passes away. The challenge is choosing the right type of policy. Two of the most common options are term life insurance and whole life insurance. Both can provide a death benefit, but they work differently, cost differently, and fit different planning goals.

Term life insurance is designed to last for a specific period, such as 10, 20, or 30 years. If the insured person dies during the term and the policy is active, the beneficiary receives the death benefit. If the term ends and the policy is not renewed or converted, coverage ends. Because term life does not usually build cash value, it is often more affordable than permanent life insurance for the same death benefit.

Term life can make sense when the main need is temporary protection. Parents may choose a term that lasts until children are grown, a mortgage is paid down, or college costs are no longer a concern. Business partners may use term life to support a buy-sell agreement during key growth years. A family with a tight budget may choose term insurance because it can provide a larger death benefit for a lower premium.

Whole life insurance is a type of permanent life insurance. It is designed to last for the insured person's lifetime as long as required premiums are paid. Whole life policies can build cash value over time. The cash value may be borrowed against or accessed under certain conditions, but loans and withdrawals can reduce the death benefit and may have tax consequences. Whole life premiums are usually much higher than term life premiums for the same initial death benefit.

Whole life can make sense for people who want lifetime coverage, predictable premiums, estate planning support, or a policy that includes cash value. It may also appeal to people who have already built a strong emergency fund, retirement savings, and basic protection, and who want another long-term planning tool. However, it is not automatically better simply because it lasts longer.

The right choice depends on the purpose of the coverage. If the goal is replacing income while children are young, covering a mortgage, or protecting a spouse during working years, term life may be enough. If the goal is lifetime estate liquidity, legacy planning, or long-term coverage that does not expire, whole life may be worth comparing.

Premiums should be reviewed carefully. A policy is only useful if you can keep it active. Buying an expensive permanent policy and later canceling it can be costly. Before choosing whole life, compare how the same dollars could be used for term coverage, retirement contributions, debt payoff, emergency savings, or other goals. This is not an either-or decision for everyone; some people use term life for large temporary needs and a smaller permanent policy for lifelong needs.

Underwriting is another factor. Insurers may review age, health history, medication, family history, lifestyle, driving record, occupation, hobbies, and sometimes medical exam results. Younger and healthier applicants often qualify for lower premiums, but each company evaluates risk differently. If you have a medical condition, an independent broker may help compare multiple insurers.

When comparing quotes, look beyond the premium. Ask whether the policy is level term or renewable term, whether it can be converted to permanent coverage, how long the premium is guaranteed, whether riders are included, and what happens if payments are missed. For whole life, ask for an in-force illustration, guaranteed values, non-guaranteed assumptions, surrender charges, loan interest, and how dividends are handled if applicable.

Common riders include waiver of premium, accelerated death benefit, child term rider, and guaranteed insurability. Riders can add flexibility, but they can also increase cost. Only add riders that solve a clear need.

Life insurance is not just a product; it is a financial safety plan. Start by estimating how much money your family would need for housing, debt, childcare, education, final expenses, and income replacement. Then compare policy types around that need. A licensed insurance professional or financial planner can help you evaluate options based on your state, budget, tax situation, and family goals.

Home Security Systems in 2026: The Complete Guide to Protecting Your Home and Family

Introduction: Why Home Security Is More Important Than Ever

rnrn

Home security systems have become an essential part of modern living. With rising concerns about property crime, package theft, and personal safety, homeowners are actively searching for the best home security systems to protect their families and assets. Advances in smart technology have made it easier than ever to monitor your home from anywhere in the world.

rnrn

Searches like “home security systems near me” and “best smart security cameras” are high CPC because users are often ready to purchase. Whether you live in a city or a rural area, investing in a reliable security system can significantly reduce risk and provide peace of mind.

rnrn
rn

What Is a Home Security System?

rnrn

A home security system is a network of devices designed to detect and prevent unauthorized access to your property. These systems typically include cameras, motion detectors, alarms, and smart locks that work together to monitor your home.

rnrn

Modern systems are often connected to mobile apps, allowing homeowners to receive real-time alerts and control devices remotely. This level of convenience and control has made smart security solutions increasingly popular.

rnrn
rn

Key Components of a Modern Security System

rnrn

A comprehensive home security setup usually includes:

rnrn
    rn
  • Security Cameras: Indoor and outdoor cameras provide video surveillance
  • rn
  • Motion Sensors: Detect movement and trigger alerts
  • rn
  • Door and Window Sensors: Monitor entry points
  • rn
  • Smart Locks: Allow remote access control
  • rn
  • Alarm Systems: Sound alerts during unauthorized entry
  • rn
rnrn

These components work together to create a layered security approach.

rnrn
rn

Benefits of Installing a Home Security System

rnrn

Installing a home security system offers multiple advantages:

rnrn
    rn
  • Crime Deterrence: Visible cameras discourage intruders
  • rn
  • Remote Monitoring: Check your home anytime from your smartphone
  • rn
  • Emergency Alerts: Receive notifications for suspicious activity
  • rn
  • Insurance Discounts: Some providers offer reduced premiums
  • rn
rnrn

These benefits make home security a valuable investment.

rnrn
rn

Smart Home Integration

rnrn

Modern security systems often integrate with smart home devices such as voice assistants and lighting systems. This allows homeowners to automate routines, such as turning lights on when motion is detected.

rnrn

Integration enhances convenience while improving overall security effectiveness.

rnrn
rn

How to Choose the Best Home Security System

rnrn

When selecting a system, consider:

rnrn
    rn
  • Ease of installation
  • rn
  • Monthly monitoring costs
  • rn
  • Video quality
  • rn
  • Storage options
  • rn
  • Customer support
  • rn
rnrn

Keywords like “best home security system 2026” attract high-intent buyers, making this niche highly profitable.

rnrn
rn

DIY vs Professional Installation

rnrn

DIY systems are cost-effective and easy to install, while professionally installed systems offer advanced features and monitoring services.

rnrn

Choosing the right option depends on your budget and security needs.

rnrn
rn

Common Mistakes to Avoid

rnrn
    rn
  • Placing cameras in ineffective locations
  • rn
  • Ignoring software updates
  • rn
  • Using weak passwords
  • rn
  • Not testing the system regularly
  • rn
rnrn

Avoiding these mistakes ensures maximum protection.

rnrn
rn

Future Trends in Home Security

rnrn

The future of home security includes:

rnrn
    rn
  • AI-powered surveillance
  • rn
  • Facial recognition technology
  • rn
  • Smart neighborhood monitoring
  • rn
  • Integration with renewable energy systems
  • rn
rnrn

These innovations will make homes safer and more efficient.

rnrn
rn

FAQ

rnrn

Are home security systems worth it?
rnYes, they significantly reduce the risk of theft and provide peace of mind.

rnrn

Do security cameras work without Wi-Fi?
rnSome systems offer local storage, but Wi-Fi enhances functionality.

rnrn
rn

Security Insight

rnrn

Searches like “best home security systems” and “smart home security cameras” attract high CPC traffic because users are ready to invest in safety solutions.

rnrn
rn

Important Information

rnrn

This content is for informational purposes only and not professional advice.

rn